AI Data Center Debt Raises Refinancing Pressure
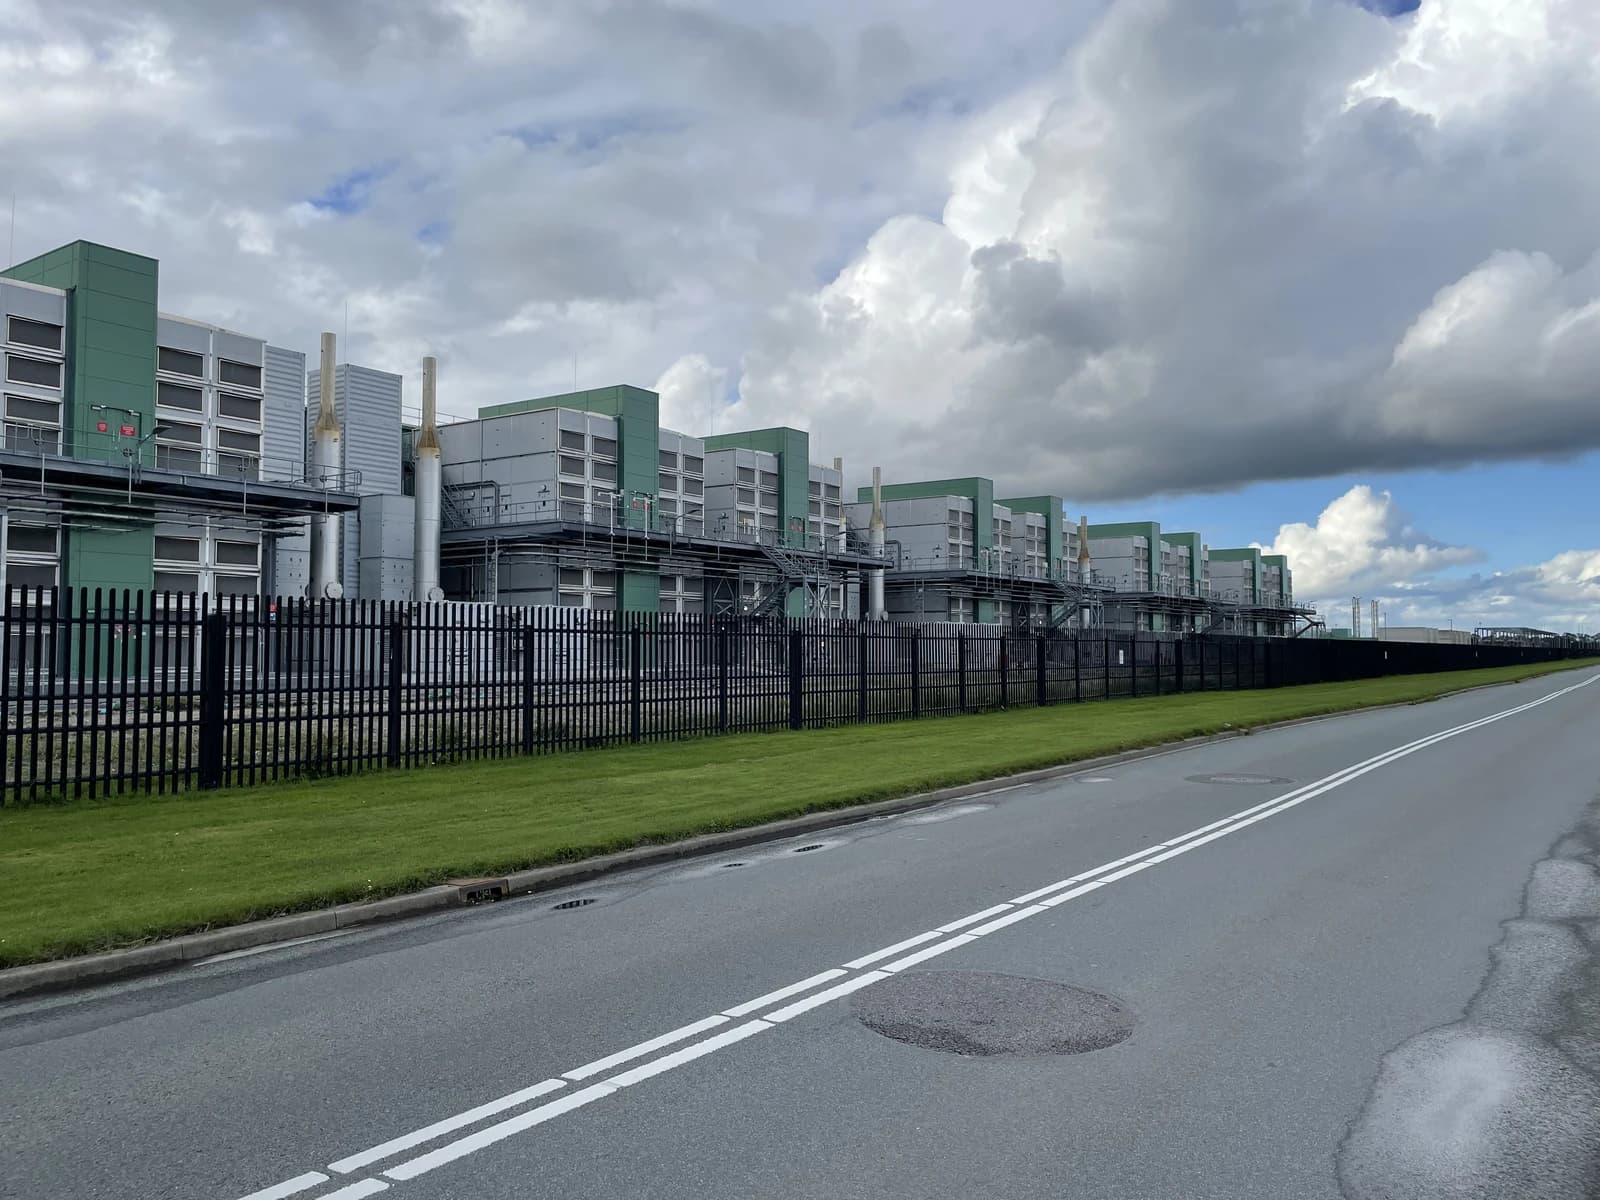
The AI buildout is becoming a refinancing story as roughly $18 billion of data center debt tied to the sector starts to matter more than the hype around chip demand and cloud growth.
That matters because the economics of artificial intelligence are shifting from pure expansion to financing discipline. If capex slows, cash flows have to do more of the heavy lifting, and companies that have leaned on debt to fund warehouses of GPUs and power-hungry data centers could face tighter margins, higher interest expense and more pressure from lenders.
Oracle is at the center of that squeeze, but it is not alone. Microsoft and Amazon are still pouring money into cloud and AI infrastructure, and both have told investors in filings that their capital and operational investments are complex, globally spread and dependent on generating enough cash flow to fund them. Nvidia, meanwhile, has disclosed $36 billion of commitments tied to AI cloud arrangements, underscoring how much of the sector’s growth story now rests on long-dated spending promises.
The market backdrop is not helping. The 10-year Treasury yield was forecast around 4.992%, keeping borrowing costs elevated even after recent easing, while high-yield credit spreads were sitting near 267 basis points. That combination makes refinancing more expensive just as the industry’s infrastructure debt is coming due, and it raises the odds that weaker borrowers will have to pay up, extend maturities or slow new projects.
Investors care because the AI trade has been priced on the assumption that hyperscalers and their suppliers can keep spending aggressively without damaging returns. That assumption is looking less clean. Oracle’s debt pressure is the clearest warning sign, but the wider read-through is that the next leg of AI spending may favor companies with fortress balance sheets and punish those relying on leverage to chase market share.
Shares of Nvidia and Microsoft were firmer in recent trade, while Amazon also bounced, but the bigger test is whether earnings and capex guidance can keep justifying the infrastructure boom. The next catalyst is the upcoming round of cloud spending updates and any sign that refinancing costs are forcing a more cautious pace of data center expansion.
| Entity | Gains | Losses |
|---|---|---|
| Cash-rich hyperscalers | ▲Funding flexibility | ▼None immediate |
| Levered data center borrowers | ▲Access to capital if refinanced | ▼Higher interest expense |
| Nvidia and chip suppliers | ▲Continued AI infrastructure demand | ▼Slower order growth if capex cools |
| Bondholders/lenders | ▲Higher coupons and spreads | ▼Credit risk if cash flows weaken |