AirTrunk lines up $1.6 billion loan before Singapore REIT
Blackstone-owned AirTrunk is lining up a $1.6 billion loan ahead of a planned Singapore REIT listing, a move that could tap deep private credit demand while setting the stage for one of the region’s most closely watched data-center monetizations.
The timing matters. Data centers remain the hottest infrastructure asset class in global capital markets, but they are also capital-hungry businesses that need constant funding for land, power, cooling and expansion. By refinancing before the listing, AirTrunk and Blackstone can lower execution risk, sharpen the asset’s balance sheet and potentially improve pricing for the REIT vehicle by showing lenders and equity investors that the platform can stand on its own.
For Blackstone, the deal is another sign it knows how to recycle capital out of AI-era infrastructure at the right point in the cycle. AirTrunk is the type of asset institutions want exposure to: contracted cash flows, secular cloud and AI demand, and a footprint in Asia-Pacific markets where supply remains tight. A successful loan and listing would reinforce the case that large data-center portfolios can be packaged, levered and listed much like prime logistics or rental housing — except with much faster growth.
The broader backdrop is still supportive. U.S. 10-year Treasury yields are near 4.95%, while Fed funds sit around 3.63%, a reminder that financing costs remain elevated versus the easy-money era. Yet data-center owners have kept borrowing because the demand curve is steep enough to absorb higher rates, especially for assets tied to AI compute. That is why the public-market read-through matters: if AirTrunk can raise debt and then list a Singapore REIT successfully, it could reopen a pipeline of similar transactions across the region.
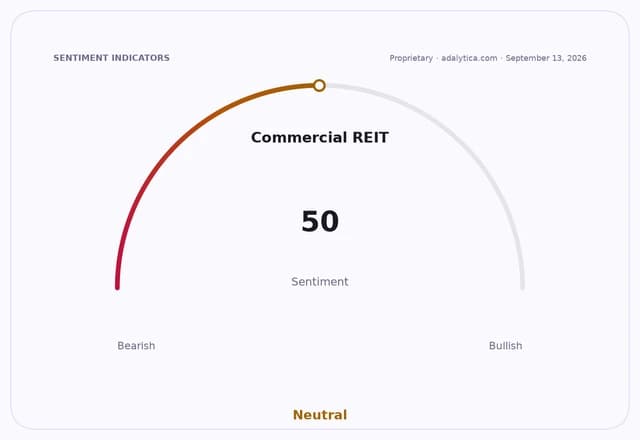
Investors should see this as a second-order play on the AI buildout. The obvious winners are the operators and landlords; the deeper opportunity sits with lenders, power suppliers, cooling specialists and listed data-center REITs that can capture the capex wave without bearing full development risk. Blackstone’s stake in AirTrunk is the headline, but the real story is that institutional money still wants long-duration infrastructure cash flows, even at today’s cost of capital.
If the financing closes and the listing lands well, expect more Asian data-center portfolios to be monetized through REIT structures, giving investors another way to buy the AI infrastructure boom before it is fully priced in.
| Entity | Gains | Losses |
|---|---|---|
| Blackstone / AirTrunk | ▲Capital recycling; higher valuation potential | ▼Execution risk if listing disappoints |
| Lenders / private credit | ▲Large asset-backed loan fees | ▼Refinancing risk if markets tighten |
| Singapore REIT investors | ▲Access to AI infrastructure cash flows | ▼Valuation pressure if yields rise |
| Public data-center rivals | ▲Sector re-rating support | ▼Need to match capex and financing pace |