Amazon AWS AI spending and profit test
Amazon’s scale in cloud and artificial intelligence is becoming a key investment test for the market, with the company leaning on AWS, its own Trainium chips and a growing stack of AI services just as rivals and customers pour record sums into infrastructure.
That matters because Amazon is not just another big tech spender. It is the largest revenue generator among the megacap technology names, the biggest hyperscaler by footprint and one of the few companies trying to control more of the AI value chain, from custom silicon to cloud capacity to model access through Anthropic. In a market increasingly focused on who can fund AI growth without destroying returns, Amazon’s position gives it both an advantage and a higher bar to clear.
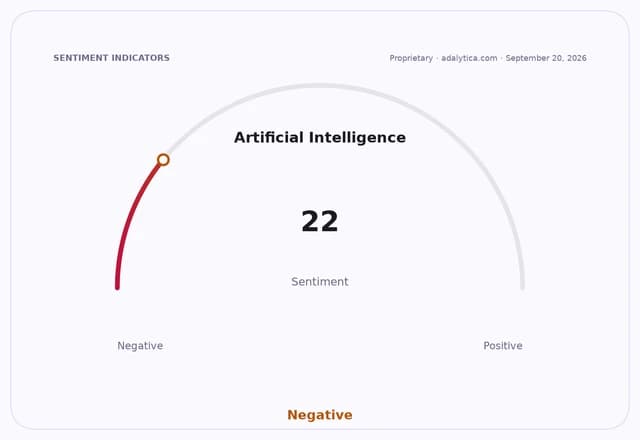
The investment case hinges on whether the company can turn that scale into durable profit growth. Amazon’s latest filings show capital expenditures running at tens of billions of dollars a quarter, with management saying most of the spending is tied to technology infrastructure and AWS expansion. That has kept Amazon at the center of the AI buildout, but it also raises the risk that near-term free cash flow and margins stay under pressure even if the strategic payoff comes later.
For investors, the significance is not just how much Amazon spends, but how efficiently it monetizes the spend. The company has spent years proving it can convert lower-cost infrastructure and logistics scale into operating leverage. AI changes that equation. Custom chips such as Trainium are meant to reduce dependence on Nvidia and improve economics over time, while AWS remains the main vehicle for selling AI compute to enterprise customers. If Amazon can show that AI demand is filling capacity and lifting revenue per dollar of capital deployed, the stock deserves a premium. If not, the market may start treating AWS as another capital-intensive utility with slower returns.
The broader competitive backdrop is getting tighter. Microsoft and Alphabet are also running heavy AI infrastructure budgets, and their shares have been whipsawed as investors alternate between excitement over AI demand and concern about spending intensity. Microsoft’s and Google’s latest trading patterns suggest that even market leaders are being judged less on growth alone and more on the return profile of their AI investments. That makes Amazon’s own execution more important, because it is competing not only with cloud peers but with Nvidia, whose chips remain central to the ecosystem and whose valuation depends on the same spending cycle.
Amazon’s broader AI strategy also extends beyond AWS. The company has been pushing AI features across consumer products and services, including Alexa+, while signaling caution about model deployment and safety. That slower, more controlled approach may appeal to enterprise buyers and regulators, but it also means Amazon is trying to win in a market where velocity often matters. The bull case is that Amazon’s breadth — retail, cloud, devices, logistics and now AI chips — creates multiple routes to monetization. The bear case is that the same breadth forces Amazon to keep spending across too many fronts before AI economics fully mature.
Technical indicators show the stock has been trying to digest those trade-offs rather than break away decisively. Amazon has recently been trading near its 50-day moving average and above its 200-day average, while momentum indicators have eased from earlier extremes, suggesting the market is waiting for clearer evidence that AI capital spending is converting into earnings power. Relative strength readings near neutral also point to a stock that is no longer being priced purely on narrative momentum.
The next catalyst is execution: AWS demand, AI service uptake, and whether Amazon can continue funding infrastructure without sacrificing cash generation. If the company proves it can do both, its scale in AI could justify wider operating margins and a stronger multiple. If capital intensity keeps rising faster than returns, investors may begin to question whether Amazon’s biggest advantage — its willingness to spend — is also becoming its biggest constraint.
| Entity | Gains | Losses |
|---|---|---|
| Amazon | ▲AI cloud scale and long-term moat | ▼Near-term free cash flow |
| Microsoft | ▲Enterprise AI demand growth | ▼Higher capital intensity |
| Alphabet | ▲TPU and cloud monetization | ▼Margin pressure from spending |
| Nvidia | ▲Ongoing chip demand | ▼Pricing power if custom silicon gains share |