American Express Platinum Card Faces Value Scrutiny
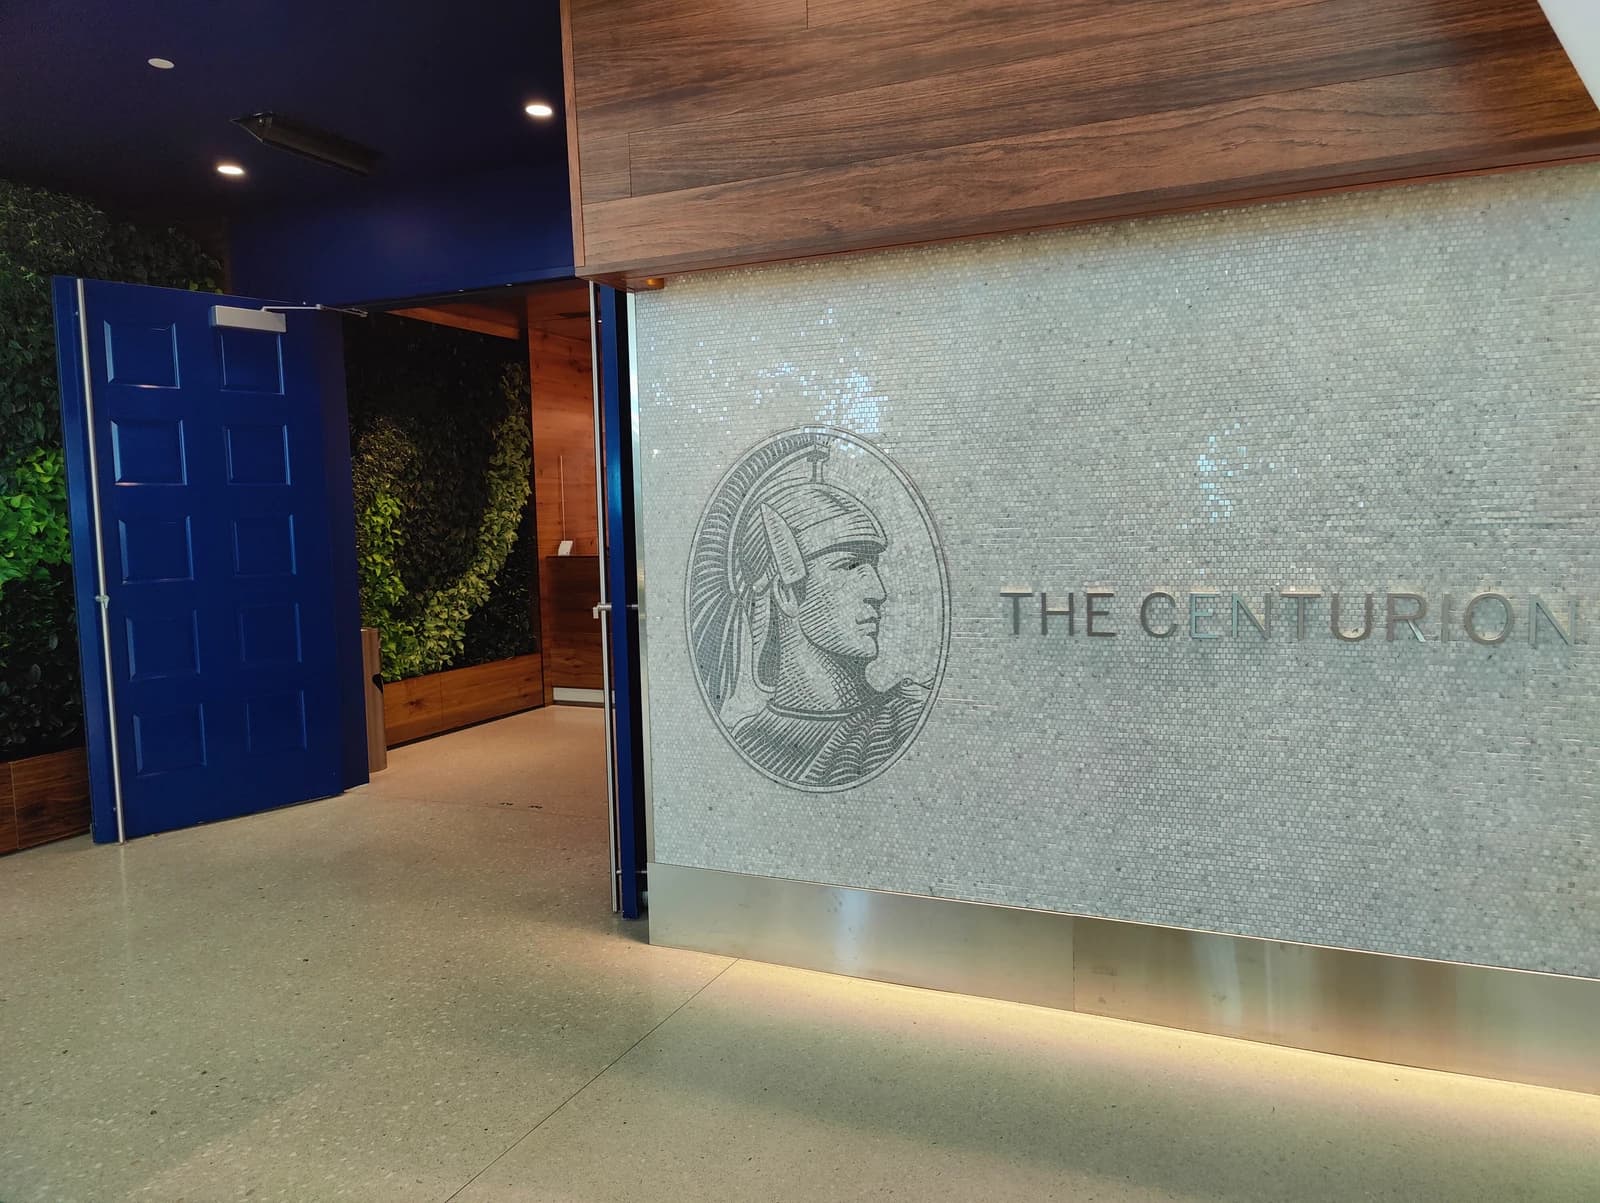
American Express’s Platinum Card is under renewed scrutiny as rivals raise fees, trim benefits and courts more price-sensitive cardholders, making the math behind premium rewards more important for consumers and investors alike.
The question is no longer whether the Platinum Card is luxurious, but whether its value proposition can survive a market where annual fees are climbing and perks are increasingly used to defend them. That matters because premium cards are one of the most profitable corners of consumer finance: issuers collect rich interchange revenue, annual fees and interest from a loyal customer base that tends to spend more and churn less. If cardholders decide the benefits no longer justify the price, the economics of the premium-card model can weaken quickly.
American Express sits at the center of that debate. Its Platinum Card remains one of the most recognizable status products in the market, but its high fee forces a simple calculation: does the value of travel credits, lounge access, statement credits and service perks exceed the cost of holding the card? In a period of higher living costs and more aggressive fee changes across the industry, that answer depends less on aspirational branding than on how frequently customers actually use the benefits.
The wider card market is moving in the same direction. Barclays has recently improved terms for credit and debit card holders, while Chase lifted a credit card fee by $100, underscoring how issuers are using pricing and benefits to defend margins and segment customers. Samsung has also launched a no-annual-fee card aimed at users who want rewards without the premium price tag. That split is important: issuers are simultaneously pushing high-end products harder while making lower-cost alternatives easier to find, which raises the pressure on American Express to prove that its premium stack is worth paying for.
For American Express investors, the issue goes beyond a single card. The company’s broader growth strategy relies on attracting affluent consumers and persuading them to keep paying for access and perks. That model has worked because premium customers generate strong spending volumes and are less likely to default than mass-market borrowers. But a sustained loss of perceived value would increase churn risk, slow fee growth and force the company either to add richer benefits or accept a weaker premium mix. Either path could weigh on margins.
The stock has reflected some of that caution. American Express shares closed at $327.78 on Sept. 14, below the 50-day moving average of $339.47, while the 14-day RSI sat at 36.6, suggesting the shares have lost some momentum after a stronger run earlier in the year. The technical picture is not decisive on its own, but it fits a market that is waiting for proof that premium-card demand can keep rising even as consumers become more selective about what they pay for.
A stronger bull case is that premium cardholders are sticky, affluent and more willing to pay for convenience, especially if they travel frequently and can extract more than the fee in benefits. The bear case is that the Platinum Card is increasingly vulnerable to “benefits fatigue,” where customers struggle to fully use the credits and begin to compare it directly with cheaper cards that offer simpler economics. In that scenario, the card’s prestige may remain intact even as its value proposition erodes.
For investors, the next test is whether American Express can continue to grow cardmember spending and fee revenue without forcing a trade-off between richer perks and lower economics. The answer will help determine whether premium cards remain a dependable engine of growth or become a more competitive, discount-driven market.
| Entity | Gains | Losses |
|---|---|---|
| American Express | ▲Higher fee revenue if value holds | ▼Churn risk if perks feel weaker |
| Premium cardholders | ▲Status and travel benefits | ▼Pressure to justify the fee |
| No-fee competitors | ▲Price-sensitive customers | ▼Harder to compete on perks |
| Investors | ▲Clarity on premium-card economics | ▼Margin risk if retention slips |