APR’s stock has doubled this year as investors bet the South Korean beauty maker can turn a September launch at Costco’s U.S. warehouses into a meaningful new growth engine.
APR stock rises on Costco U.S. launch
The move matters because Costco is not just another retailer. Its shelves can deliver instant scale, brand validation and repeat household exposure in the world’s largest consumer market. For APR, a successful debut would strengthen the case that K-beauty can move from niche import status to mainstream U.S. shelf space, potentially expanding margins and reducing dependence on a domestic market that is increasingly crowded.
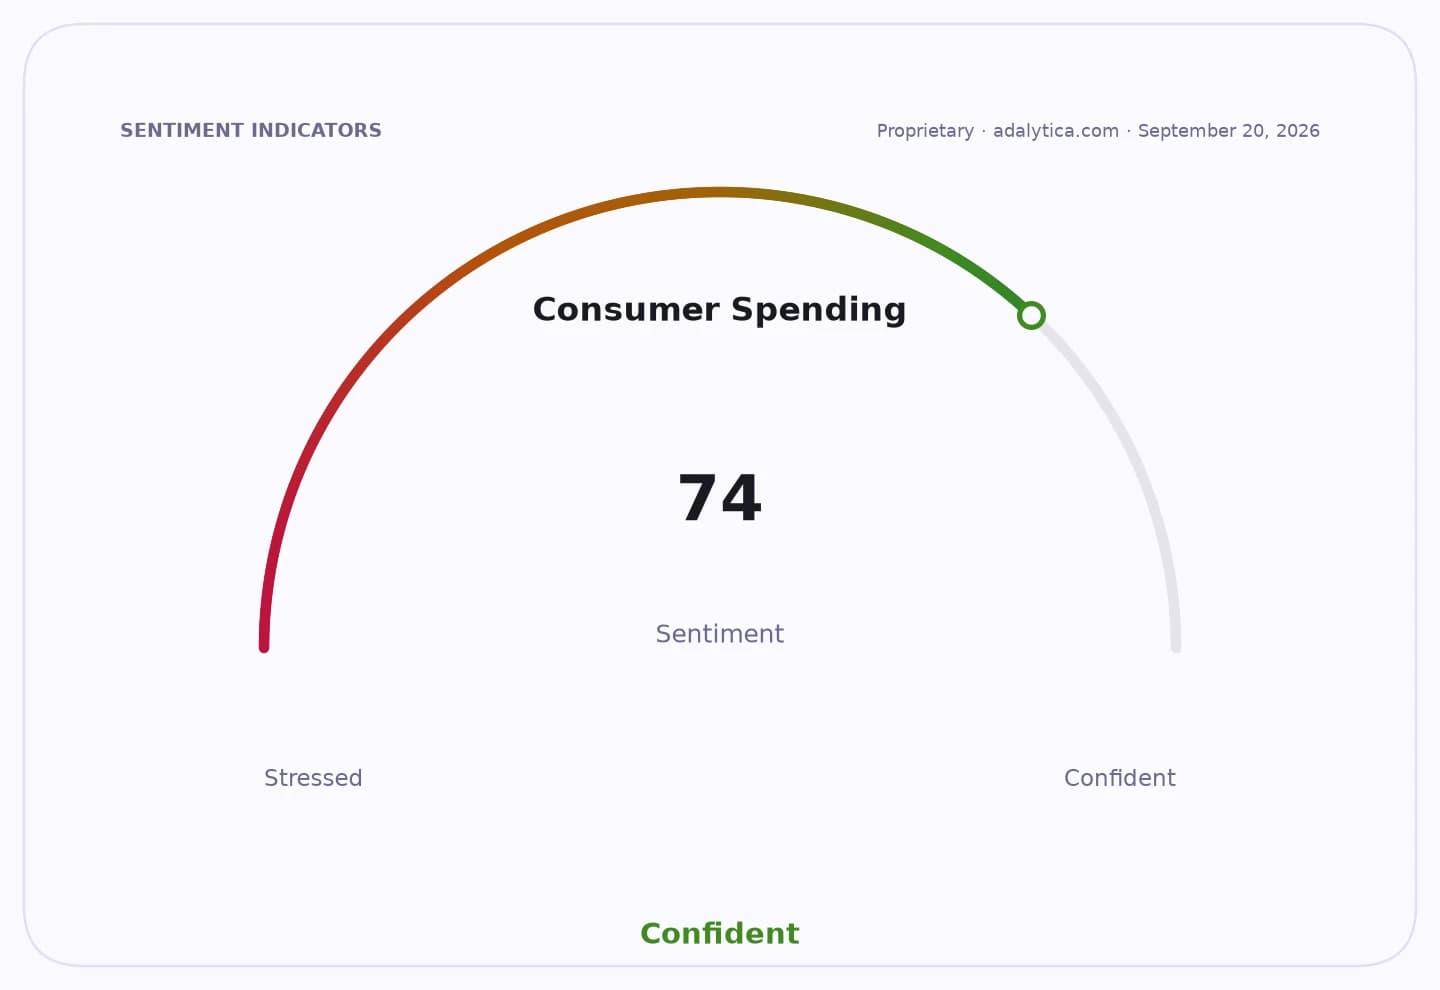
That is the economic logic behind the rally. Consumer appetite for premium beauty and wellness products remains resilient even as broader spending has wobbled, and the current Adalytica consumer spending snapshot shows elevated sentiment and awareness, suggesting shoppers are still willing to pay for discretionary “treat” categories. For Costco, the addition of a fast-growing K-beauty label fits its model of limited assortment and high inventory turnover, especially if the product can generate trial quickly and sustain replenishment.
APR’s valuation, however, now leaves less room for execution missteps. A 100% share gain implies the market is already discounting some combination of strong sell-through, channel expansion and brand momentum in the U.S. If demand underwhelms, or if warehouse distribution proves too narrow to move the needle, the stock could easily give back some of that premium. The bear case is that Costco provides visibility but not necessarily enough breadth to transform earnings at scale.
For investors, the key question is whether the Costco launch becomes a template for broader U.S. retail penetration or remains a one-off win. If APR can use the exposure to deepen brand recognition, the company could leverage a higher-profile channel into more wholesale and online opportunities. If not, the rally will look more like a sentiment trade around K-beauty enthusiasm than a durable rerating of fundamentals.
| Entity | Gains | Losses |
|---|---|---|
| APR | ▲U.S. scale and brand validation | ▼Higher expectations |
| Costco | ▲Fresh premium beauty traffic | ▼Shelf-space risk if sell-through slows |
| Existing K-beauty rivals | ▲Category visibility lifts | ▼Pressure from a fast-growing entrant |
| Investors long APR | ▲Momentum and expansion upside | ▼Valuation compression if launch disappoints |