Argentina targets Falklands oil firms with sanctions
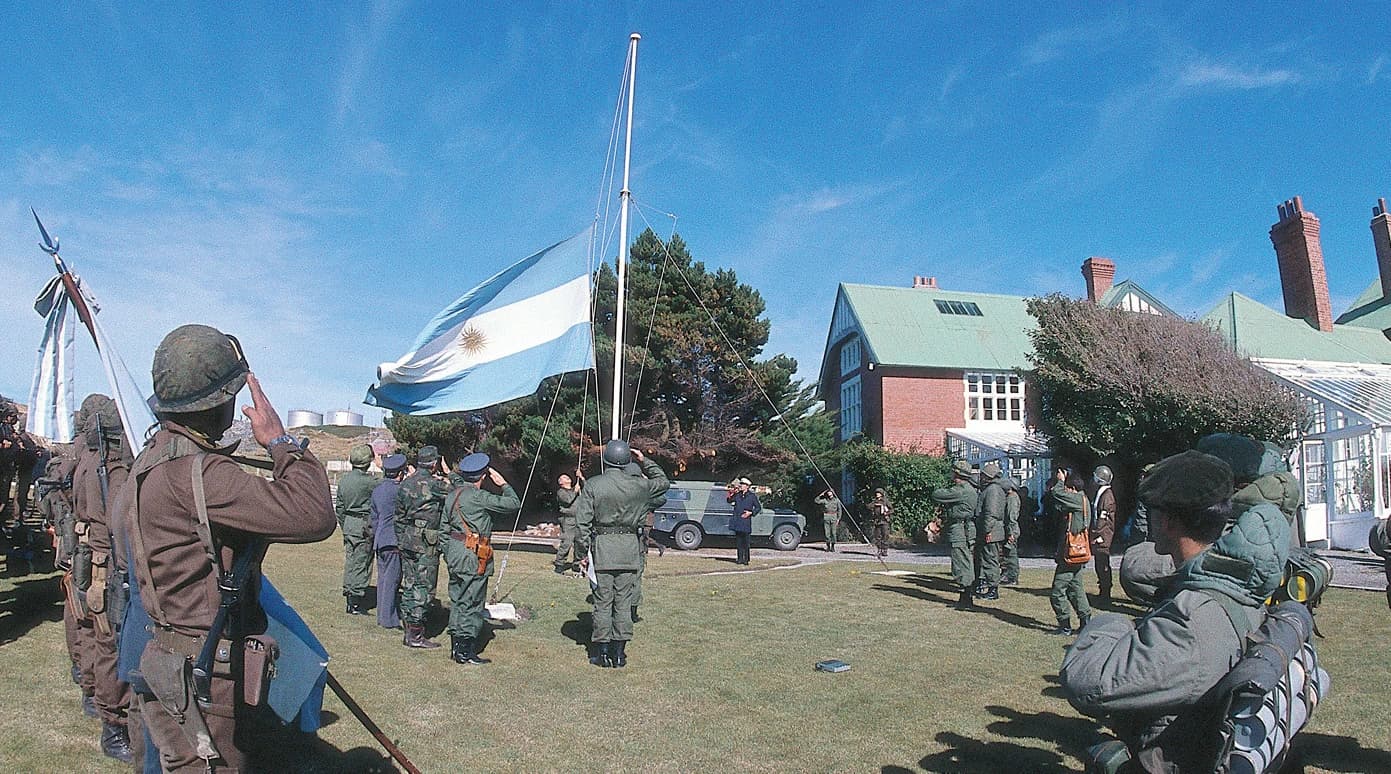
Argentina is escalating its long-running Falklands claim by threatening to expand sanctions on companies developing oil off the islands, a move that could complicate financing, contracting and supply chains for one of the basin’s most closely watched projects.
President Javier Milei said he would sign a decree to speed up penalties under a 2011 law and extend them beyond operators to shareholders, directors and suppliers, raising the cost of doing business in and with firms involved in the Sea Lion development. The announcement matters because it turns a political dispute into a direct commercial risk for companies with exposure to the North Falkland Basin, while also underscoring how sovereignty tensions can spill into project economics just as capital-intensive offshore work is moving forward.

The timing is important for investors because Sea Lion, led by Britain’s Rockhopper Exploration and Israel’s Navitas Petroleum, reached a final investment decision for phase one in December and is said to hold about 1.7 billion barrels of reserves. For a project that depends on outside capital, specialist contractors and a stable logistical chain, even measures that are legally contested can increase the discount rate applied by lenders and partners. That does not necessarily stop development, but it can raise funding costs, lengthen timelines and force counterparties to weigh commercial upside against political exposure.
Milei framed the sanctions as a defense of Argentine sovereignty and paired them with plans for a naval base in Tierra del Fuego, budget increases for the Defense Ministry and a broader sovereignty bill. Economically, that signals a desire to build infrastructure and institutional capacity in the far south, which could have secondary implications for shipping, defense spending and Argentina’s long-term claims over Antarctic logistics. For a country still trying to stabilize its economy, however, the immediate market relevance is less about near-term fiscal outlays than about the possibility of fresh friction with foreign investors at a moment when Argentina is trying to present itself as more open and rules-based.

The confrontation also reflects a shifting geopolitical backdrop. Milei pointed to comments by US President Donald Trump that cast doubt on Washington’s automatic support for Britain, suggesting Argentina sees a window to press its case. That is politically significant, though not a material change to the legal status of the islands, where the UK says sovereignty is settled and islanders voted overwhelmingly in 2013 to remain a British Overseas Territory. In market terms, the broader message is that diplomatic uncertainty can be as consequential as geology for frontier energy projects.
For listed names, the immediate read-through is asymmetric. Rockhopper and Navitas face the most obvious execution risk if Argentine pressure affects contractors, insurers or financing. By contrast, companies already insulated from the project or able to keep operations ring-fenced may see limited direct impact. BP’s price action in the context provided shows how energy shares can be swayed more by global crude dynamics than by a single regional flashpoint, but politically induced supply risk tends to matter whenever it intersects with offshore investment and maritime logistics.
The bull case for the project is that the sanctions have limited practical enforceability offshore and could prove mostly symbolic if the UK backs the development and capital remains available. The bear case is that even symbolic sanctions can chill counterparties and raise the price of doing business, especially in a jurisdiction where sovereign risk is already embedded in valuations. Investors will be watching whether Argentina follows through with enforcement, whether Britain responds, and whether lenders and service firms begin to demand a higher premium for Falklands exposure.
| Entity | Gains | Losses |
|---|---|---|
| Argentine government | ▲Sovereignty leverage | ▼Investor confidence |
| Rockhopper/Navitas | ▲None obvious | ▼Financing and execution risk |
| UK/Falklands authorities | ▲Diplomatic backing test | ▼Higher political friction |
| Contractors and suppliers | ▲Potential pricing power if risk rises | ▼Exposure to sanctions and delays |