Argentina decree raises Falklands project risk
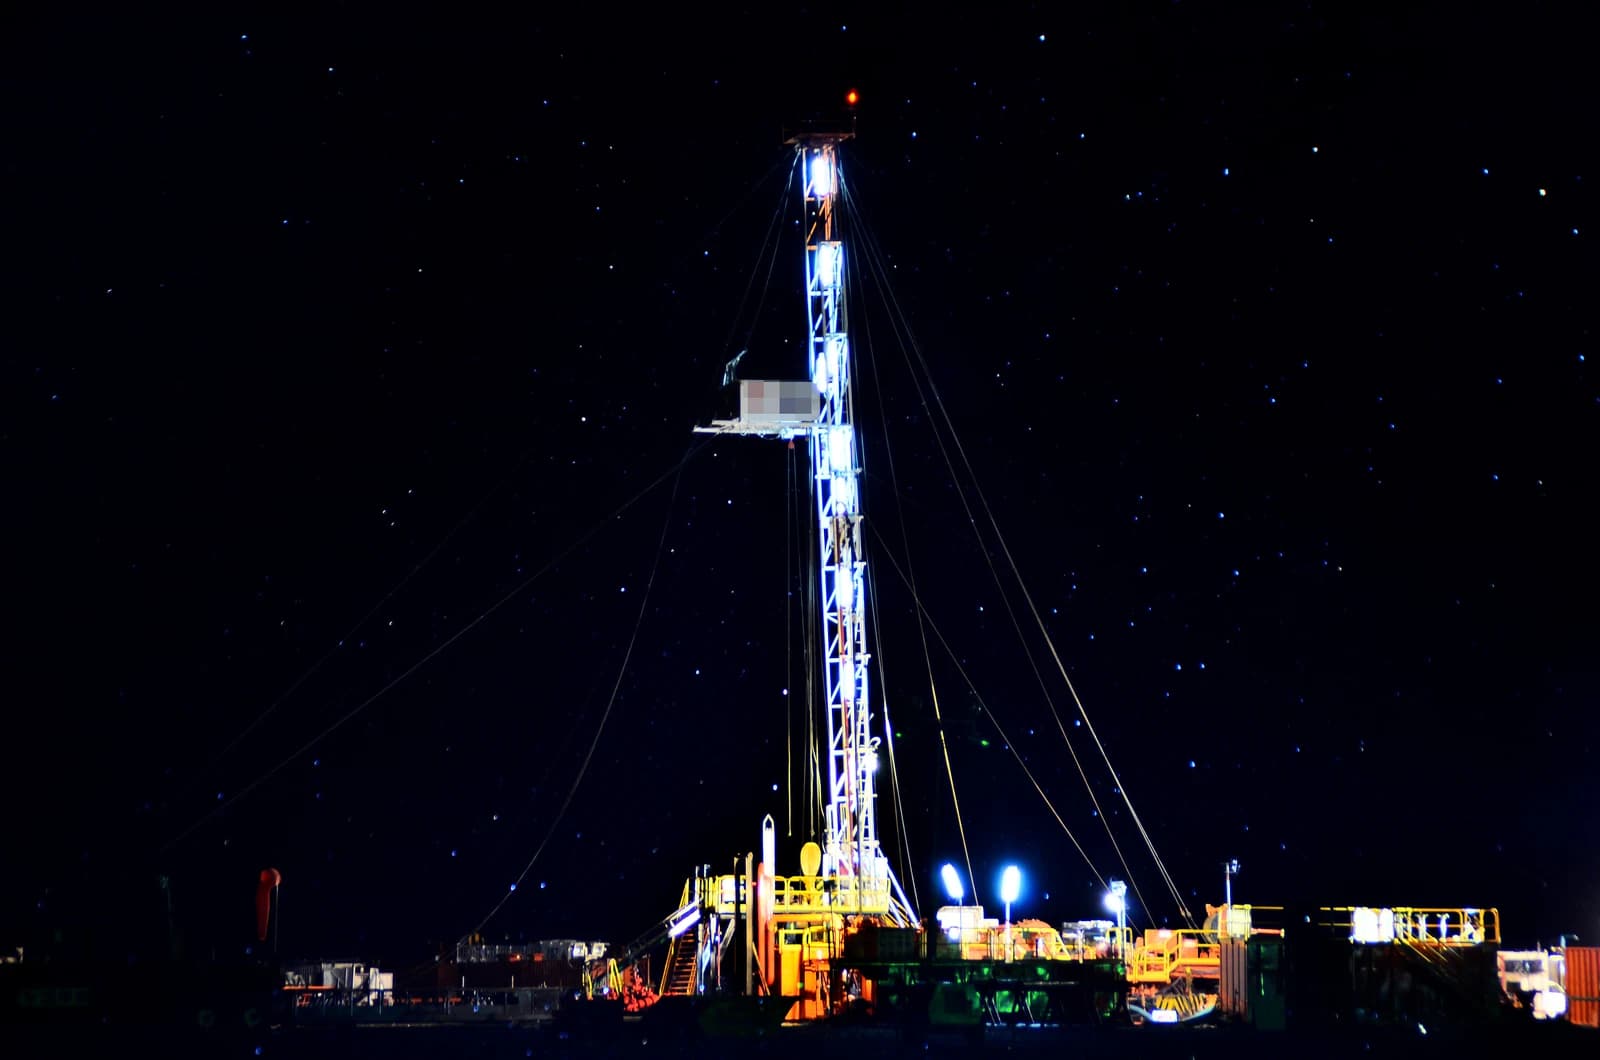
Argentina just raised the cost of doing business in the disputed Falkland Islands, and that matters because it tries to steer capital, contractors and financing toward Vaca Muerta instead of Sea Lion.
President Javier Milei’s decree, built on Argentina’s long-standing Malvinas law, goes beyond symbolism. By extending sanctions to suppliers, directors and shareholders tied to offshore activity in the islands, and by requiring new investors seeking tax breaks under the RIGI regime to certify they are not violating Argentina’s continental shelf rules, Buenos Aires is trying to turn sovereignty claims into a practical business filter. For investors, the message is simple: if you want access to Argentina’s more attractive onshore shale basin, you cannot casually help fund a rival offshore project in territory Buenos Aires says is illegally exploited.
That is why the immediate reaction from the oil-services complex matters more than the rhetoric. SLB, Halliburton, Baker Hughes and DLS Archer quickly said they were not participating in Sea Lion and would respect Argentine rules. Even if none had been publicly linked to the project before, their statements narrow the pool of global contractors willing to touch it. Offshore developments in the South Atlantic are already expensive; Vaca Muerta offers lower drilling costs, growing infrastructure and the promise of policy stability through RIGI. For a services company with Argentine exposure, the economic choice is hard to ignore.
The market has also noticed the political risk. Rockhopper Exploration shares fell in London and Navitas Petroleum slipped in Tel Aviv after the announcement, a reminder that legal disputes over reserves can hit valuations even when production is still years away. Sea Lion needs not just geology and capital, but a supply chain, insurers, partners and politically comfortable financiers. That makes it vulnerable to exactly the kind of squeeze Buenos Aires is attempting.
Still, investors should not overread the first reaction. Navitas and Rockhopper said they would continue operations and argued their licences remain valid under British backing. That is where the real test begins: whether Argentina enforces the decree beyond paper, and whether the rules on “providers” and “shareholders” are broad enough to bite. Buenos Aires has already declared Navitas clandestine before, with little material consequence, so credibility will depend on follow-through.
For long-term investors, the bigger story is competition for capital in Latin American energy. Vaca Muerta remains the more scalable, lower-cost basin, while Sea Lion faces rising geopolitical friction and a thinner contractor base. That does not make the Falklands project impossible, but it does make it more expensive and more fragile. If Argentina sustains this clamp, the winners are onshore shale players and service firms aligned with Vaca Muerta; the losers are Sea Lion backers, offshore suppliers and any investor who underestimated the political premium now attached to the Malvinas dispute. Worth watching, and for patient investors, the stronger long-term opportunity still looks like Argentina’s mainland energy boom.
| Entity | Gains | Losses |
|---|---|---|
| Vaca Muerta operators | ▲More contractor interest | ▼None |
| Sea Lion / Navitas / Rockhopper | ▲None | ▼Higher political risk |
| SLB / Halliburton / Baker Hughes | ▲Clearer compliance path | ▼Lost optionality offshore |
| Argentine state / RIGI projects | ▲Greater leverage | ▼Higher diplomatic friction |