Argentina reform push faces election timing risk
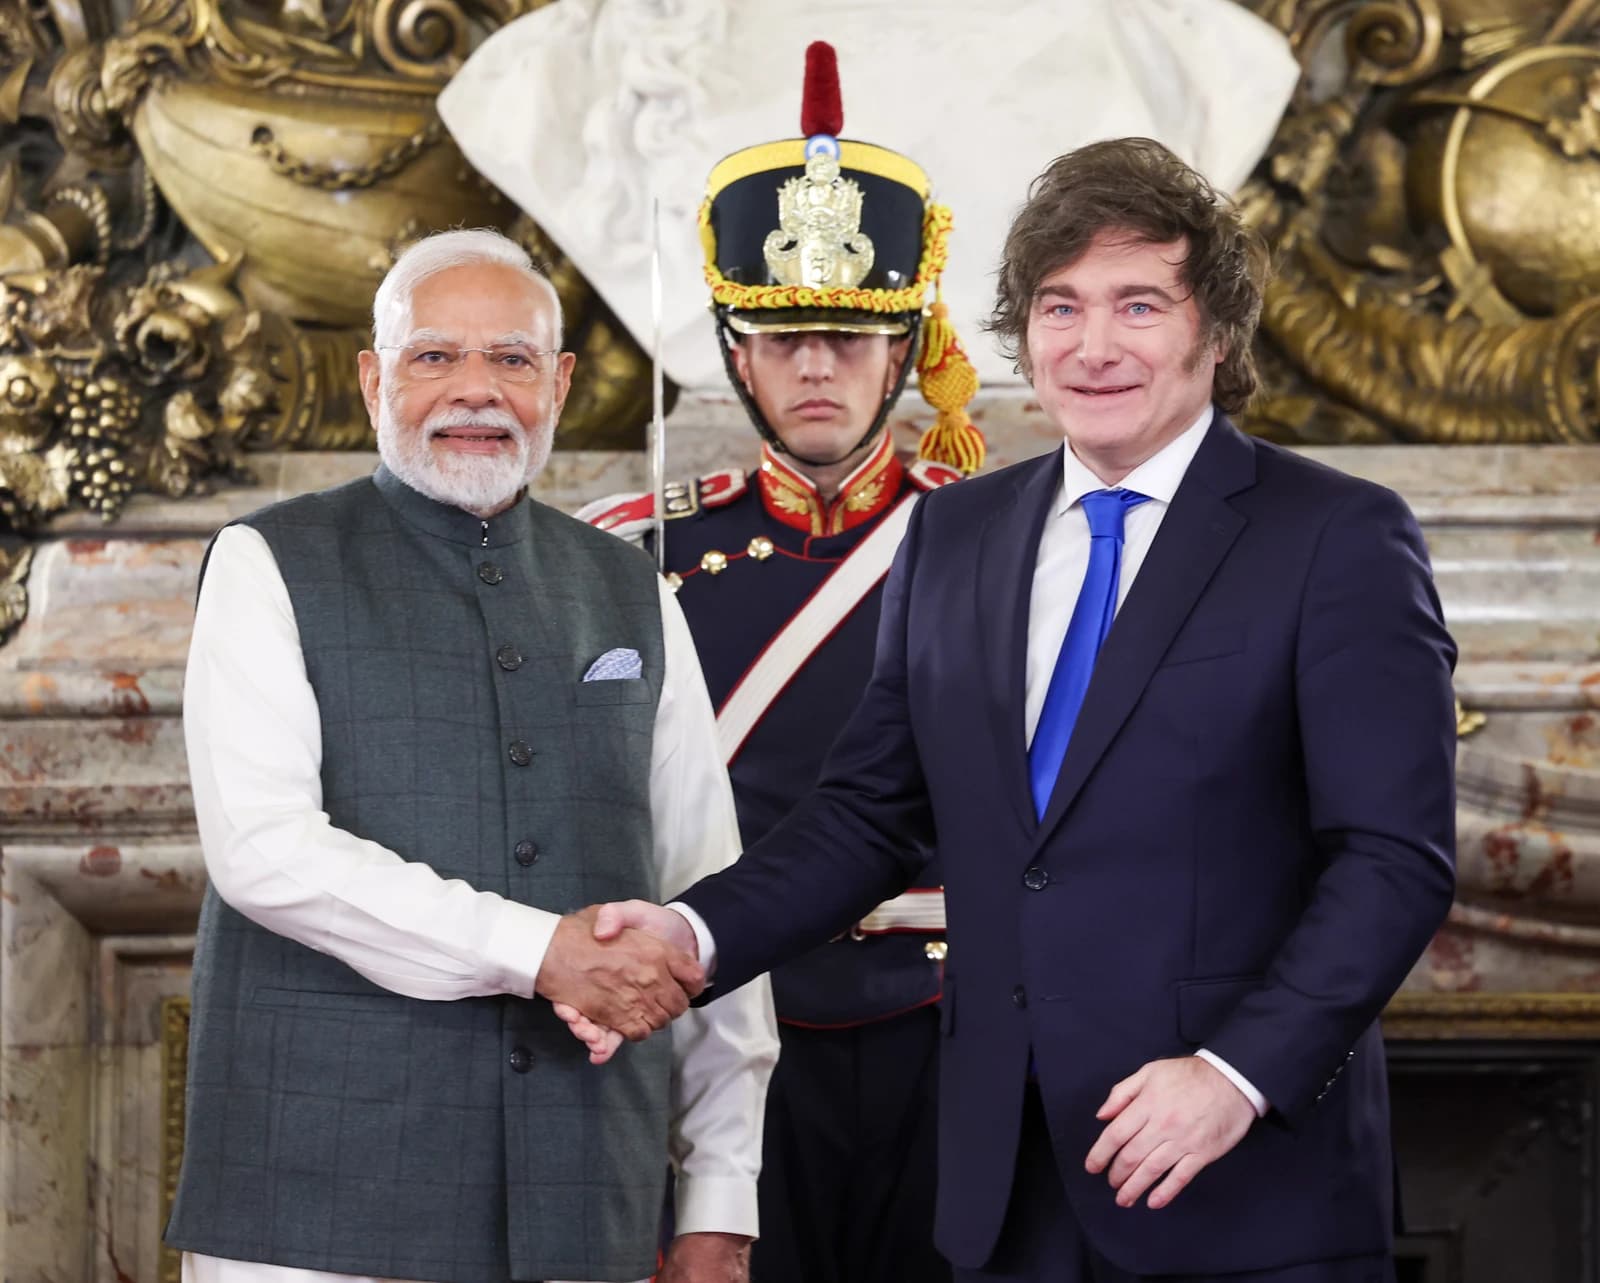
Argentina’s market-friendly pivot is opening doors in Washington, but the slower payoff from trade, patents, seeds and mining reform is colliding with a political calendar that may not give Javier Milei enough time to reap the economic gains.
That is the central risk now hanging over Milei’s plan: the government is trying to convert regulatory changes and foreign lobbying into investment, higher productivity and export growth, yet the benefits depend on negotiations and legislation that can take months or years. Investors, meanwhile, are being asked to price in a future that still looks heavily dependent on the outcome of the midterm political cycle and the durability of the president’s coalition.
The most immediate economic prize is with the United States. A delegation led by Jeffrey Goettman from the Office of the US Trade Representative pressed Argentine officials on whether Buenos Aires is actually delivering on commitments already made under the Trump administration. The talks covered patent cooperation, intellectual property and a raft of potential new measures that could ease market access for US companies. For Argentina, that matters because the country is trying to rebuild investment flows after years of controls and underinvestment. For Washington, it is about leverage: access to the world’s largest market remains a powerful incentive for a government that needs capital, technology and credibility.
The stakes are not abstract. Officials in Buenos Aires say Brazil produces 30% more soy per hectare than Argentina, a gap they blame in part on seed quality and weaker rules around royalties. On the government’s own calculation, lower farm productivity costs Argentina about $6 billion a year in exports. That is a meaningful drag for an economy that badly needs foreign currency, especially with industrial output and construction still under pressure and the growth outlook deteriorating. If productivity does not improve, the country’s strongest hard-currency earner remains capped even as the administration seeks a more open trade posture.
That is why the stalled seed law has become such a telling test case. The US Trade Representative’s office wants Argentina to move ahead with legislation that would settle disputes between seed companies and farm groups over royalty payments and exempt acreage. A deal would help modernize an agricultural sector that remains central to Argentina’s balance of payments. But any breakthrough would still have to survive domestic political resistance, which is where the calendar becomes a trap for Milei: legislation can outlast election cycles, while markets often do not.
The same time horizon problem runs through the government’s push to attract US investment into rare earths, a strategically important group of minerals used in electric vehicles, wind turbines and defense equipment. Washington wants to deepen involvement in Argentina’s deposits partly to keep China out of the sector, and local business figures such as José Luis Manzano are already positioning themselves. He hired a Washington lobbying firm to make the case for critical minerals, underscoring that the competition for the assets is not just commercial but geopolitical. For Argentina, rare earths could become a fresh source of export revenue and strategic relevance. For investors, they represent optionality — but only if the administration can keep policy stable long enough to unlock capital spending and permitting.
India’s push for easier pharmaceutical access points in the same direction. New Delhi wants Argentina to upgrade its status to facilitate drug imports, and economy minister Federico Sturzenegger has made cheaper imported medicines part of his deregulation agenda. That could help lower costs for consumers and the health system, but it also faces friction inside the bureaucracy, where reforms can be slowed by sectoral rules and ministerial turf battles. The benefit is clear: cheaper medicines would help household purchasing power and inflation dynamics. The risk is equally clear: if reforms are delayed, Milei’s promise of lower prices through competition remains more theoretical than immediate.
The domestic backdrop makes the timing more delicate. Argentina’s economy contracted in the second quarter after growing in the first, and July began badly with industrial output down 5% and construction down 4.6%. High-frequency data for August have not yet pointed to a rebound. If activity falls again in the third quarter, the economy would enter technical recession just as the government moves deeper into an election season. That would squeeze the administration’s room to maneuver, particularly if it tries to preserve fiscal discipline rather than loosen policy to buy a short-term rebound.
Markets are already balancing those tensions. Argentina-focused ETF ARGT has gained from its lows but remains only modestly above its 50-day moving average, with recent RSI readings near neutral and MACD momentum softening. That suggests investors are not pricing a clean breakout in confidence. Broader emerging-market ETF EEM has been steadier, while China-linked FXI has weakened, a reminder that Argentina’s story is still mostly a country-specific one rather than part of a broad risk-on wave. For portfolio managers, the near-term question is whether Milei’s reform pipeline can translate into hard investment commitments before economic weakness and electoral uncertainty dominate the narrative.
| Entity | Gains | Losses |
|---|---|---|
| Milei government | ▲Trade/investment upside | ▼Election-timeippage |
| US investors/exporters | ▲Better market access | ▼Policy delay risk |
| Argentine farmers | ▲Higher-yield seeds | ▼Royalty disputes |
| Local consumers | ▲Cheaper imports | ▼Slow reform gains |