Asian Stocks Mixed as Markets Await PMI Data
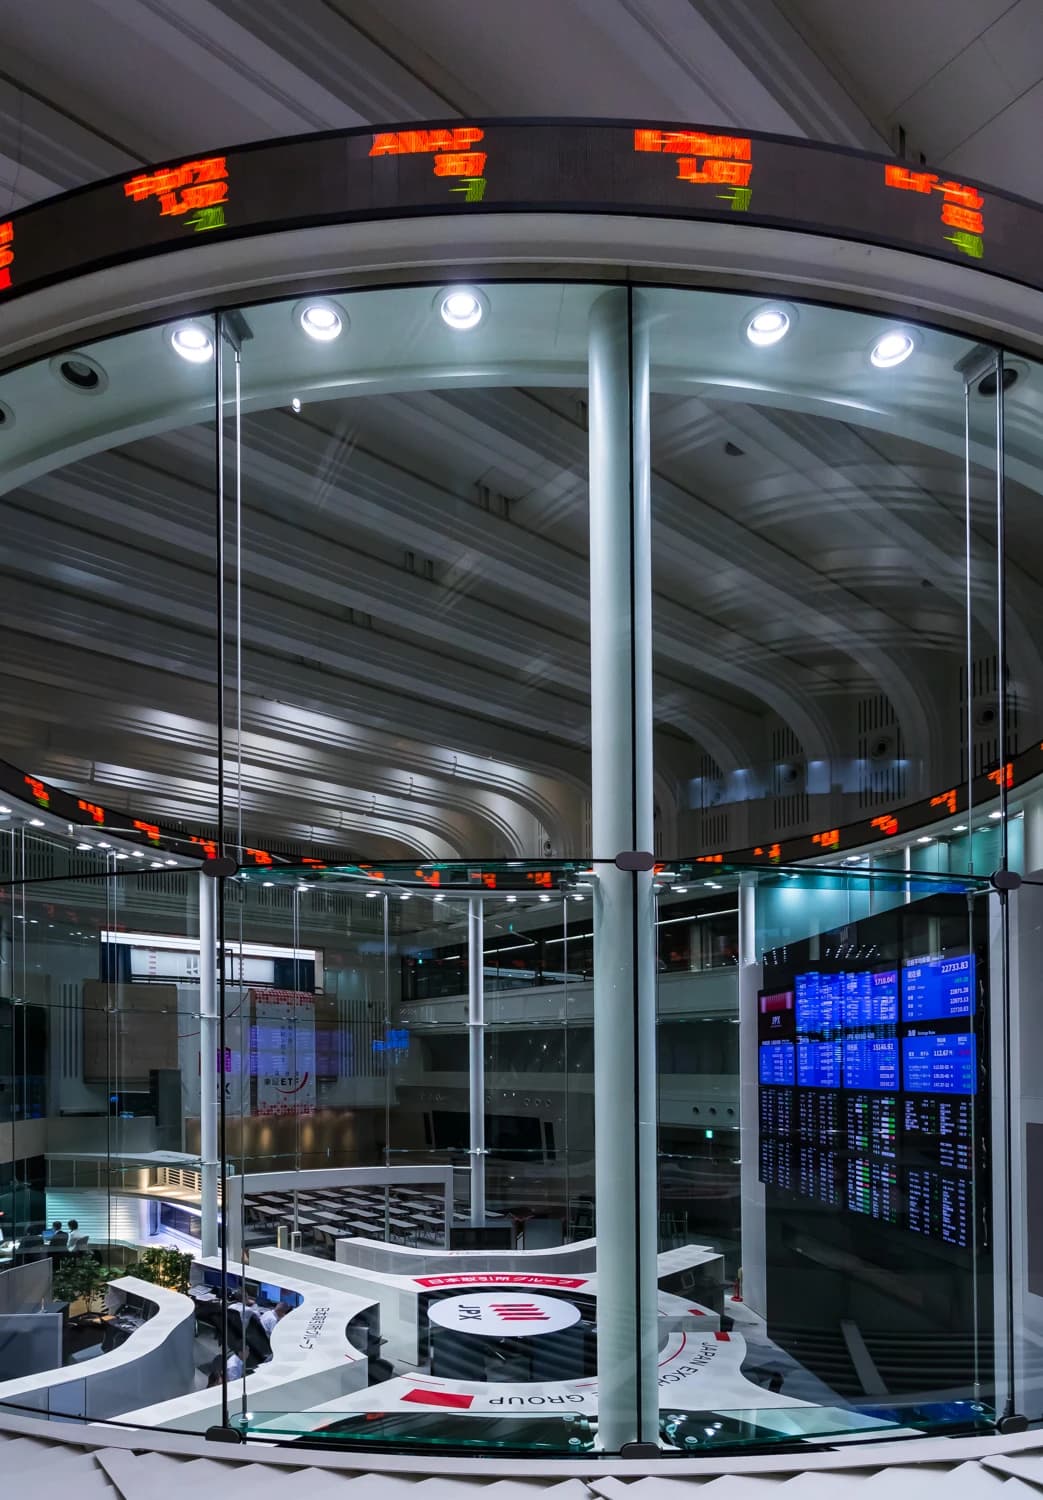
Asian equities were mixed and largely directionless while futures for Europe and Wall Street rose, as investors waited for PMI releases to test whether the global growth backdrop is stabilizing or losing momentum.
The market tone points to a pause rather than a pivot. In Asia, Tokyo slipped 0.17%, Taiwan fell 0.67% and Hong Kong was down 0.17%, while Seoul, Sydney, Shanghai, Mumbai and Singapore posted modest gains. That split screen fits a market that has already priced in a fair amount of optimism around policy easing and earnings resilience, but is now looking for macro confirmation before extending the rally.
The immediate driver is the currency and rates backdrop. A weaker dollar, trading near 157.35 yen and 1.16 against the euro, tends to pressure Japanese exporters by lowering the yen value of overseas earnings. That was evident in Tokyo, where TDK fell 2.43% and Panasonic dropped 2.28%, while even large cyclicals such as Sony and Mazda were softer. Toyota was unchanged. The move also reflects a broader market habit: when the dollar retreats, investors tend to reassess the earnings leverage built into export-heavy Asian indices.
Technology shares were another weak point across the region, underscoring how much of the recent advance has been driven by a narrow set of momentum names. Semiconductor stocks were mixed in Tokyo, with Disco, Screen Holdings and Advantest lower, offset by gains in Tokyo Electron, Sumco and Lasertec. That dispersion suggests investors are still willing to own structural chip winners, but are less inclined to chase the group as a whole without a clearer read on end-demand from electronics and industrial customers.
Commodity moves added a different signal. Brent’s decline and a 1.07% drop in WTI to $90.05 a barrel point to a softer energy tone, while European gas eased 1.23%. At the same time, gold jumped 2.65% to $4,423.27 an ounce and silver rose 3.25% to $65.77. That combination usually means markets are hedging: lower energy prices can help inflation-sensitive assets and consumers, but a rush into precious metals indicates demand for safety is still high. In Adalytica’s S&P 500 trade signals, sentiment remains at an “Extreme Fear” reading, reinforcing the idea that investors are not broadly confident even when index futures are firmer.
Bond markets also leaned toward caution. The 10-year Treasury yield and European sovereign yields moved lower, and Italy’s BTP-Bund spread widened slightly to 83.2 basis points, a still-comfortable level by historical standards. Falling yields usually support equities by easing discount-rate pressure, but they also reflect expectations that growth may not be accelerating enough to force a hawkish central-bank response. For investors, that leaves the market sensitive to the PMI data: a beat could revive the pro-cyclical trade, while a miss would strengthen the case for defensive positioning and further gains in rates-sensitive assets.
The broader narrative is that global markets are waiting for a macro catalyst after a fragmented session in Asia. Futures in Europe and the US are higher, but the move looks more like anticipation than conviction. If the PMI figures confirm resilience in services and a floor in manufacturing, cyclicals and exporters could recover. If they disappoint, the current mix of softer yields, firmer gold and weaker energy may prove to be the market’s real message: growth is slowing, and investors are quietly moving back toward safety.
| Entity | Gains | Losses |
|---|---|---|
| Gold and silver | ▲Safe-haven demand | ▼Risk appetite |
| Asian exporters | ▲Weaker if dollar falls | ▼Yen revenue translation |
| European and US futures | ▲PMI optimism | ▼Overnight Asia drift |
| Energy producers | ▲None from softer crude | ▼Oil and gas prices |