Brazil rare earths law tightens local control
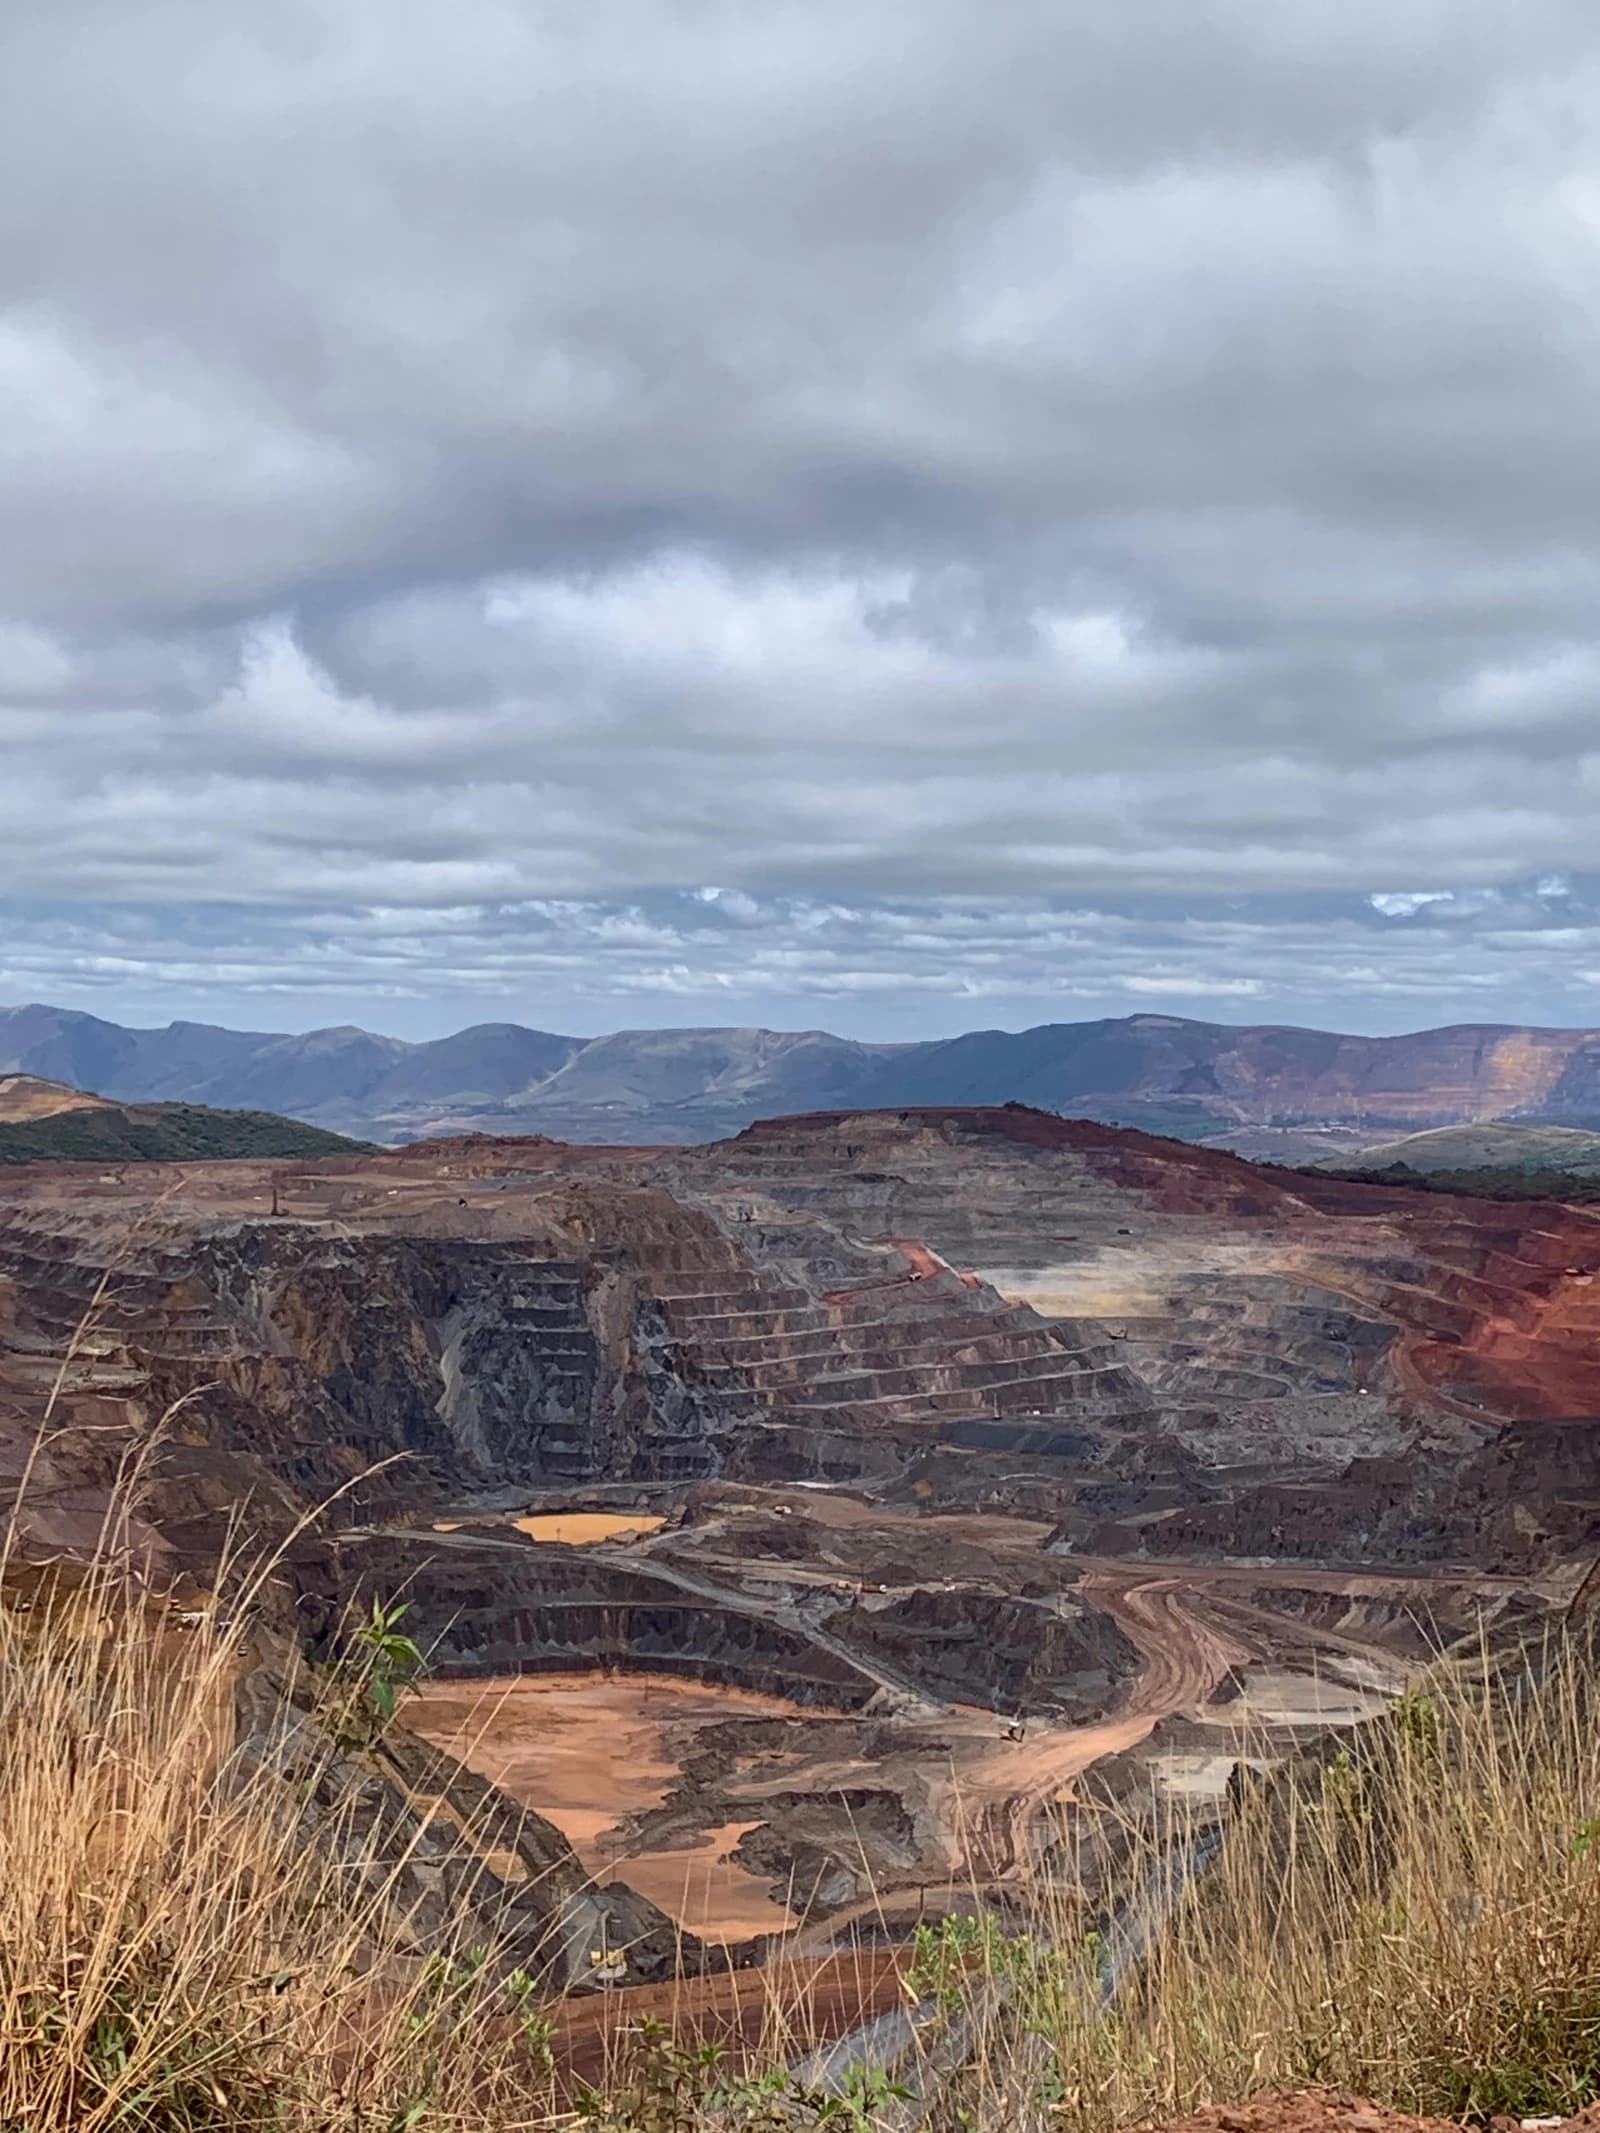
Brazil is moving to strengthen executive control over its rare earths sector, aiming to keep a tighter hand on a strategic supply chain that is increasingly central to electric vehicles, wind turbines and defense hardware.
The shift matters because Brazil holds the world’s second-largest rare earth reserves after China, but lacks the technology and processing capacity to turn that resource base into exportable value. By insisting on partnerships, technology transfer and domestic refining, President Luiz Inácio Lula da Silva is trying to capture more of the economic upside at home rather than letting Brazil remain a raw-material supplier.
That approach puts Brasília in the middle of a global scramble to diversify rare earth supply away from China, which dominates extraction and processing. U.S. companies and the Trump administration have shown interest in Brazilian assets, but the two countries’ trade ties have been strained by tariffs Washington imposed on Brazilian exports, complicating any deal flow and raising the political price of foreign participation.
For investors, the stakes are bigger than a policy tweak. Rare earths are a choke point for clean energy, autos and weapons systems, so any move that changes who controls Brazilian deposits, how quickly permits move and where refining takes place can reshape valuations across miners, processors and magnet makers. The development also reinforces the premium on companies with downstream separation and processing know-how, not just mine access.
The law passed with support from Lula-aligned lawmakers and part of the opposition, underscoring rare earths’ status as a national-industrial policy issue ahead of Brazil’s presidential race. Eduardo Braga, the bill’s rapporteur, said Brazil needs partnerships that ensure “technology transfer for the Brazilian nation,” a sign the government wants strategic investors but on tighter local-content terms.
Shares of U.S.-listed rare earth names have already been volatile as traders price in policy support and supply-chain de-risking. MP Materials, Newmont and Uranium Energy Corp have all seen sharp swings in recent months, with conventional technical indicators such as RSI and the 50-day and 200-day moving averages showing the sector remains highly momentum-driven and sensitive to headlines around policy, pricing and China export controls.
The next catalyst is how aggressively Brazil turns the new framework into licensing, joint ventures and processing rules, and whether foreign miners and U.S. industrial buyers are willing to accept more stringent local control in exchange for access to one of the world’s most important undeveloped rare earth endowments.
| Entity | Gains | Losses |
|---|---|---|
| Brazil government | ▲More control, more local value-add | ▼Less policy flexibility |
| Foreign investors | ▲Access to reserves, if accepted | ▼Tighter tech-transfer terms |
| China | ▲Faces more supply diversification | ▼Potentially weaker dominance |
| Rare earth miners/processors | ▲New project pipeline | ▼Higher execution and policy risk |