Canada bonds hold up as global yields rise
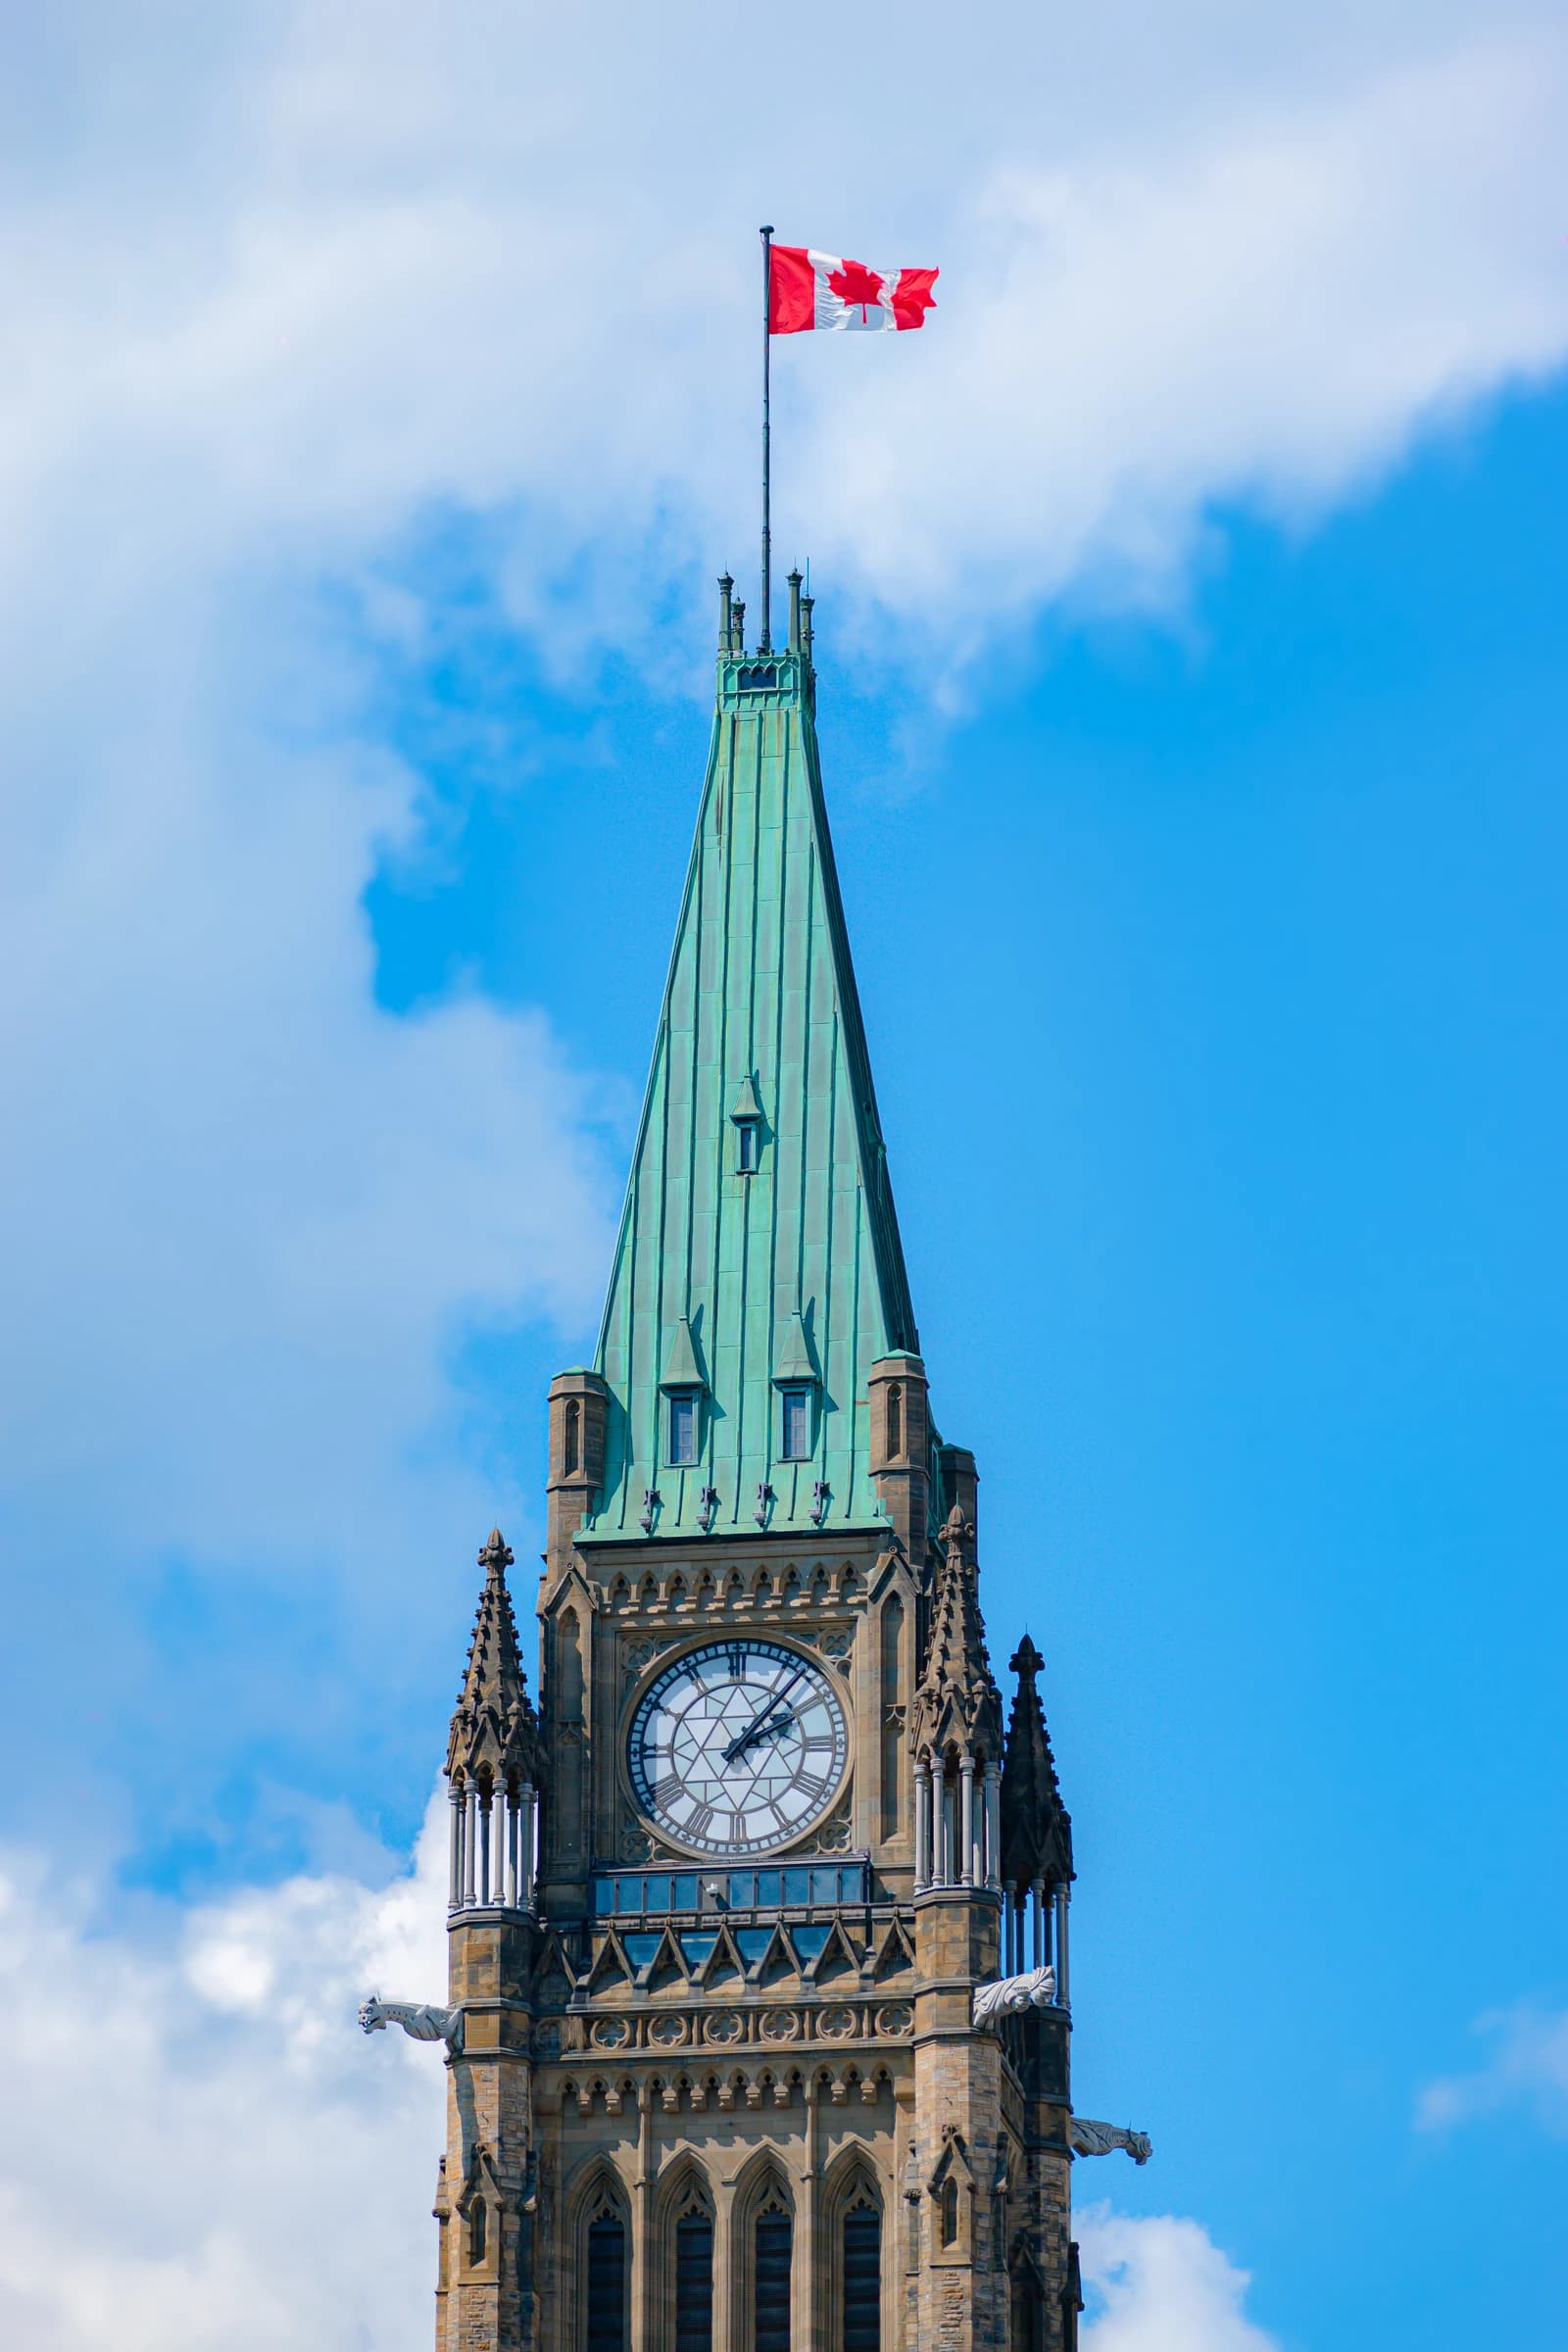
Canada’s finance minister is arguing that the country can withstand a global bond selloff because foreign investors are still buying its debt, keeping borrowing costs well below those in the United States even as long-term yields jump worldwide.
The message matters because sovereign funding costs are increasingly shaping fiscal policy, currency moves and equity valuations. In a market where 30-year U.S. Treasury yields have climbed to about 5.27%, Canada’s 30-year yield was 4.15% on Tuesday afternoon in New York, leaving a spread that is wider than the roughly 70-basis-point discount Canadian long bonds have averaged to Treasuries over the past decade. For Ottawa, that relative resilience gives the government more room to issue debt to finance infrastructure and housing without being forced immediately into a harsher tightening of spending.
Finance Minister Francois-Philippe Champagne said investor confidence is supported by Canada’s fiscal choices, including reduced expenses and higher revenues, as he attended Group of 20 meetings in North Carolina. Statistics Canada said foreign investors bought a record C$80.8 billion of Canadian government bonds in the second quarter, an important buffer at a time when markets are re-pricing sovereign risk across developed economies.
That demand is helping keep Canada’s yield curve comparatively contained. The benchmark 10-year Canada yield was around 3.745%, still the third lowest in the Group of Seven, behind Germany and Japan. While that was about 37 basis points higher than at the start of July, the spread versus U.S. 10-year notes has narrowed slightly, suggesting Canada has not been hit as hard as its southern neighbor by the global repricing in duration.
For investors, the key question is whether Canada’s relative outperformance can last. Bulls will point to the country’s persistent appeal to international buyers, its credible funding profile and the fact that Canadian debt remains one of the more defensive large sovereign markets in a world of elevated volatility. The case for caution is that higher deficits are coming, the government is preparing a new budget, and Ottawa is still aiming to spend on growth-oriented priorities while trying to attract more private investment.
Champagne said Canada is “not immune” to geopolitical shocks, citing the wars in Iran and Ukraine, which continue to affect energy markets and consumer prices. That matters because a prolonged rise in inflation expectations would eventually feed into longer-dated borrowing costs everywhere, including Canada, regardless of current demand.
The political backdrop is also adding noise. Relations with the U.S. are at their worst in years after trade talks collapsed on Aug. 21 and both countries imposed tariffs on each other’s goods. Prime Minister Mark Carney said talks cannot resume until Washington stops “throwing shade” and gets serious, while Champagne said he plans to be “constructive” but “firm” in a meeting with Treasury Secretary Scott Bessent. For markets, the trade dispute raises the risk that a policy shock could hit growth, corporate earnings and cross-border investment just as bond markets are already under pressure.
Ottawa’s fiscal path will be closely watched in the next budget. The finance department projected a C$65.3 billion shortfall for this fiscal year in April, or about 2% of GDP, but more than half of economists in a Bloomberg survey expect a deeper deficit. If growth weakens or borrowing needs rise faster than expected, Canada’s funding advantage could narrow. For now, though, the bond market is signaling that Canada is still viewed as one of the safer credits in the G7.
| Entity | Gains | Losses |
|---|---|---|
| Canada government bonds | ▲Lower yields, strong foreign demand | ▼Higher deficits, future issuance pressure |
| Foreign investors | ▲Attractive sovereign carry | ▼Currency and duration risk |
| U.S. Treasuries | ▲Little from higher yields | ▼Borrowing costs rise sharply |
| Canada exporters | ▲Potentially weaker funding stress | ▼Trade tensions and tariff risk |