China Ends Foreign Dividend Tax Exemption
China is ending a long-standing tax exemption on foreign individuals’ dividend income, a move that lifts the levy on payouts to overseas investors and narrows one of the more attractive features of Chinese equities for cross-border capital.
The policy shift matters economically because it puts foreign and domestic investors on a more even footing, but it also makes Chinese stocks less tax-efficient for wealthy individuals and family offices that have used dividend flows as part of offshore allocation strategies. The change is set to affect how capital is routed into mainland and Hong Kong-listed shares, particularly among income-focused investors.
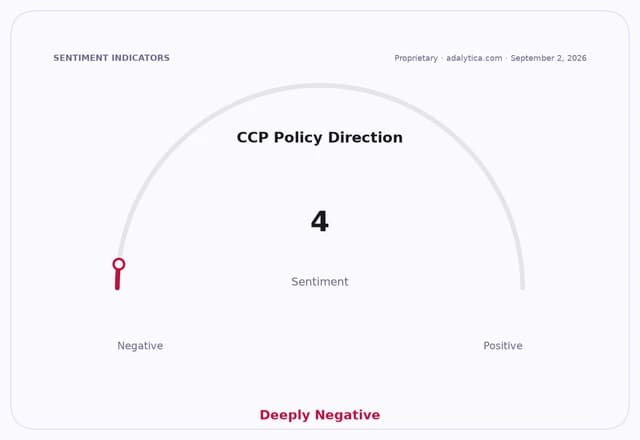
Beijing said the step is “intended to deliver equal treatment for all market players,” signaling a broader effort to standardize market rules even as it seeks to steady investor confidence in a fragile policy environment. Adalytica’s China CCP Policy Direction Sentiment gauge remains in “Extreme Fear,” underscoring how sensitive markets remain to any tightening of policy or capital rules.
The decision comes as China tries to balance support for financial markets with the need to widen the tax base and tighten oversight of cross-border flows. It also arrives against a backdrop of uneven sentiment toward Chinese assets, with U.S.-China relations still politically fraught even as investors continue to hunt for value in the world’s second-largest economy.
For investors, the immediate question is whether the tax change prompts a modest re-pricing of dividend-heavy China exposure or a broader rethink of after-tax returns across the market. That is especially relevant for exchange-traded products such as the iShares China Large-Cap ETF, which has been trading below its 200-day moving average, and the Direxion Daily FTSE China Bull 3X Shares fund, where risk appetite remains choppy.
China’s next policy moves on capital controls, market access and tax enforcement will be watched closely for signs that this is an isolated adjustment or part of a wider recalibration of rules for foreign money.
| Entity | Gains | Losses |
|---|---|---|
| China tax authorities | ▲Higher revenue | ▼Less tax leakage |
| Domestic investors | ▲Equal treatment | ▼No dividend break advantage |
| Foreign individuals | ▲Rule clarity | ▼Higher after-tax dividend costs |
| China dividend stocks | ▲Policy transparency | ▼Some foreign income demand |