China Services PMI in Focus for AUD and China ETFs
China’s latest services PMI is set to be the key release in Asia on Thursday, with traders watching to see whether private-sector strength can offset a softer official read and keep support under the Australian dollar and China-linked assets.
The day’s main market mover is the Rating Dog / S&P services PMI, coming after this week’s manufacturing surveys sent mixed signals on the economy. Official data from the National Bureau of Statistics showed August manufacturing PMI at 49.8, still below 50 but slightly better than expected, while the non-manufacturing gauge held at 49.0, dragged down by construction.
By contrast, the private RatingDog manufacturing PMI rose to 51.5, a two-month high and above forecasts, underscoring a divergence between more state-heavy surveys and a panel that leans toward smaller, export-oriented firms. That split matters because services make up the bulk of China’s economy and household demand, so a weak reading would reinforce worries that momentum is still uneven despite signs of resilience in factory orders and exports.
For investors, the print is a direct test of the China-growth trade. The Australian dollar often trades as a liquid proxy for Chinese demand because of the commodity link, especially iron ore, and a downside surprise could pressure AUD/USD and AUD crosses. A stronger-than-expected result would add to this week’s argument that external demand is holding up and could help Chinese equity proxies such as the FXI and MCHI ETFs stabilize above recent levels.
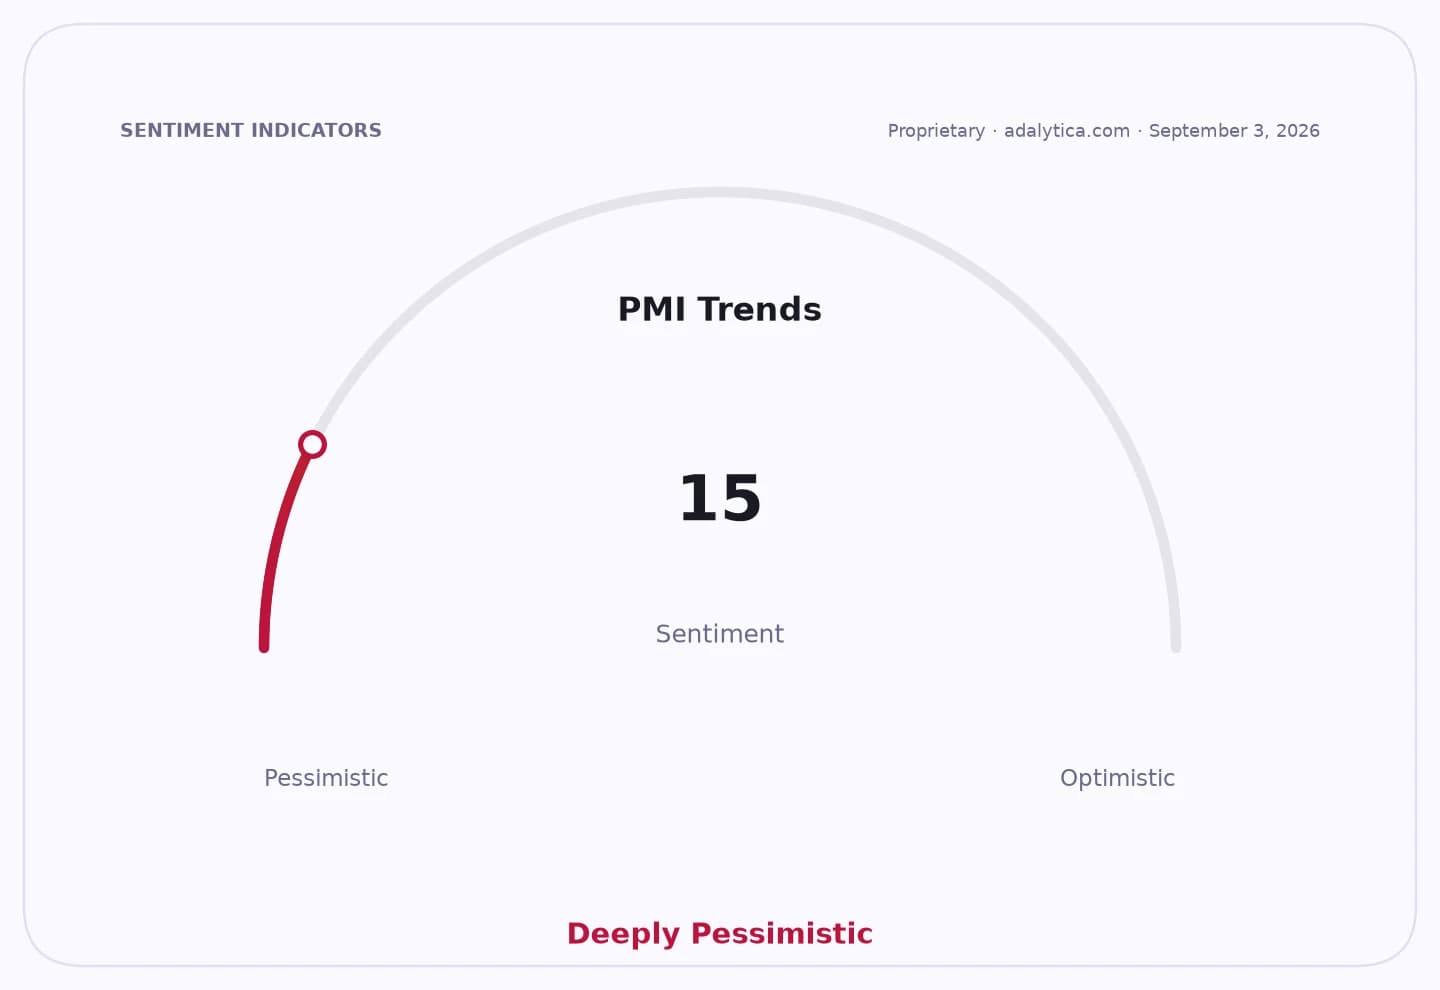
That backdrop is also showing up in market sentiment. Adalytica’s China Economic Growth Target Sentiment gauge jumped to 96, labeled “Extreme Greed,” while its PMI Trend Recession Sentiment remains in “Extreme Fear” territory at 15, highlighting how traders are still split between hopes for policy support and concern over lingering slowdown risks.
The next catalyst is simple: today’s services PMI. If it confirms the official weakness, attention will quickly turn back to Beijing’s policy response and to whether the modest recovery in manufacturing can broaden into domestic demand.
| Entity | Gains | Losses |
|---|---|---|
| AUD bulls | ▲Strong China services PMI | ▼Weak China services PMI |
| China growth bets | ▲Better domestic demand signal | ▼Slower household spending |
| FXI and MCHI holders | ▲Broader China rebound narrative | ▼Renewed growth concerns |
| Short-duration China skeptics | ▲— | ▼Stronger risk sentiment and higher China exposure |