College football’s latest escalation is no longer just about who wins on Saturdays; it’s about who controls the money, the rules and the future talent pipeline.
College football money race lifts sports retailers
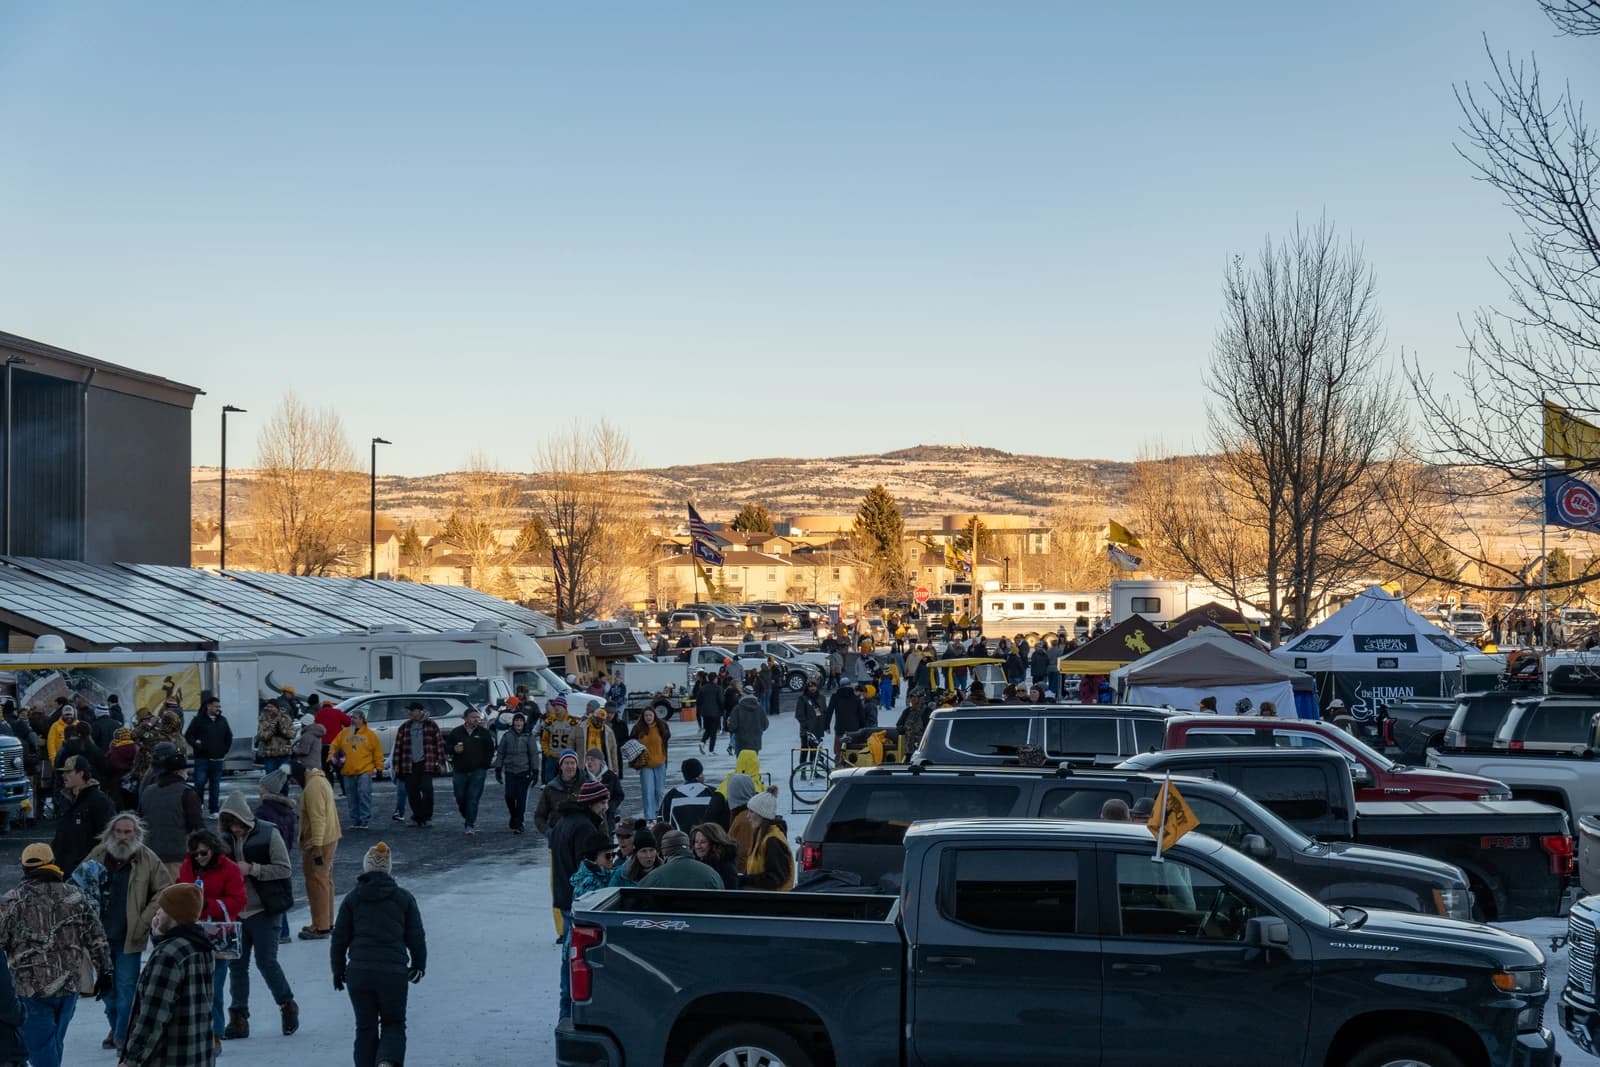
That matters because the sport is moving deeper into an arms race that rewards scale, brand power and institutional muscle. The SEC and Big Ten blocking the return of former NFL players to member schools shows how the biggest conferences are protecting their own turf, even as the championship race tightens and recruiting for the 2027 class is already underway. For investors, the message is simple: college football is becoming a more expensive, more consolidated entertainment economy, and that can reshape spending across apparel, media and sports-adjacent businesses.
Sentiment IndicatorsⓘProprietary · adalytica.com · September 4, 2026
This is a snapshot — live sentiment, awareness and momentum for 130+ markets update continuously in the dashboard.Open AlphaPulse
The economic significance is hard to miss. College football is increasingly behaving like a capital-intensive industry, where conferences, universities and boosters are all spending to secure competitive advantage. When the SEC and Big Ten act together, they are not just making a football decision; they are asserting pricing power over talent access, brand control and competitive rules. That kind of governance tension can keep costs elevated and uncertainty high, but it also tends to concentrate value in the biggest brands.
For companies tied to the college sports ecosystem, that is both an opportunity and a warning. Dick’s Sporting Goods, Nike and other apparel names benefit when fan engagement, team spending and youth recruiting all stay hot. But the same environment can also pressure margins if inventories pile up and promotions get more aggressive, which is exactly what Dick’s flagged in its latest filing. Nike has also been fighting a tougher demand backdrop, with its stock still far below where it traded earlier in the year. In other words, the long-term story is still about sports passion and merchandising power, but the near-term economics are more about execution than easy growth.
The market picture reinforces that split. Dick’s shares have plunged from above $200 to about $140, and Nike is trading near $39 after a long slide, while Warner Bros. Discovery has held up better as investors continue to look for optionality in live sports and broader media rights. That tells you investors are not simply buying “sports” as a theme. They are rewarding the businesses that can turn sports attention into durable cash flow without overpaying for inventory, rights or distribution.
The broader narrative is that college football is no longer a pure sports story. It is an institutional power struggle wrapped around a massive consumer business. The SEC, Big Ten and their peers are fighting to preserve their advantages, recruits are committing earlier, and championship relevance is now intertwined with spending discipline. That should keep the sport compelling for years, but it also means the financial winners will be the groups with the strongest brands, the deepest pockets and the best ability to monetize attention.
For long-term investors, that means staying selective. The sport itself may keep growing, but not every sports-linked stock will benefit equally. The best approach is to focus on companies with real scale, pricing power and free-cash-flow generation, and to treat volatility as part of the opportunity. If you want exposure to the sports economy, this is a story worth watching — and one that rewards patience.
| Entity | Gains | Losses |
|---|---|---|
| SEC and Big Ten | ▲Control and influence | ▼Competitive openness |
| Top programs and recruits | ▲Brand power and exposure | ▼Smaller schools |
| Dick’s Sporting Goods and Nike | ▲Long-term sports demand | ▼Margins from promotions |
| Fans and media partners | ▲Bigger championship stakes | ▼Predictable, stable rules |