Costco Before Earnings as UBS Keeps Buy Rating
Costco is heading into Thursday’s fiscal fourth-quarter earnings with its stock under pressure, and that is exactly why UBS says the market may be underestimating the resilience of one of retail’s best compounders.
The call matters because Costco is no longer being priced as a simple defensive retailer. At nearly $895 a share, the stock trades below its 50-day moving average and its 200-day moving average, while UBS still sees a path to $1,275, about 42% above current levels. In a market that is increasingly punishing any sign of slowing momentum, Costco’s premium valuation leaves little room for disappointment — but also creates meaningful upside if the company once again shows that its model can keep expanding in a tougher consumer backdrop.
That is the core of Michael Lasser’s “This warehouse is still stocked full” thesis. The five-star UBS analyst kept his Buy rating and said Costco continues to outperform most retail peers, even as the environment becomes more complicated. His caution is important: when a stock already carries a premium multiple, even modest changes in traffic, ticket growth or membership momentum can move the shares sharply. But the setup is equally important for investors hunting quality growth. Costco has matched or beaten earnings estimates in each of the last five quarters, and Wall Street expects revenue to rise 10% to $94.85 billion in the coming report, with adjusted earnings per share seen up 12% to $6.55.
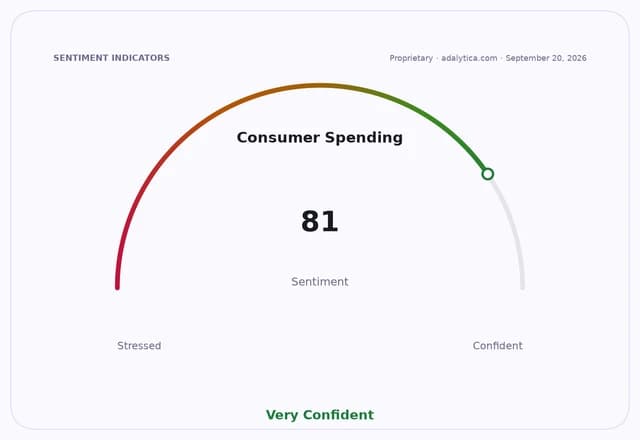
The bigger investment story is that Costco remains one of the market’s cleanest plays on consumer resilience, scale economics and recurring membership revenue. The company just reported fiscal 2026 net sales of $297.3 billion, up 10.2% from a year earlier, reinforcing the argument that shoppers continue to trade value and bulk purchasing for convenience. That matters at a time when broader consumer sentiment signals remain mixed and other retailers are warning that conditions are less predictable. Walmart has held up well, but the wider retail tape has shown that earnings reactions can be brutal when growth slips even slightly.
For investors, Costco is still a classic high-quality compounder: not the cheapest name on the board, but one that can justify a premium if execution stays steady. UBS’s call suggests the market may be focusing too much on near-term moderation and not enough on the durability of the membership model, the long runway for store productivity and the ability to keep converting traffic into operating leverage. If Costco delivers another clean quarter next week, the stock could quickly re-rate toward the higher end of Wall Street’s expectations.
The actionable takeaway is straightforward: if you want exposure to a consumer franchise with pricing power, recurring cash flow and a proven ability to outperform, Costco remains one of the best large-cap retail names to own into earnings — especially if weakness in the shares has already priced in too much caution.
| Entity | Gains | Losses |
|---|---|---|
| Costco | ▲valuation reset higher | ▼bears betting on slowdown |
| UBS bulls | ▲thesis validated | ▼if KPIs soften |
| Long-term investors | ▲upside from quality compounding | ▼traders chasing perfection |
| Retail peers | ▲benchmark pressure | ▼comparison to Costco execution |