CrowdStrike Rises on AI Security Demand
CrowdStrike has emerged as one of the clearest beneficiaries of the latest AI debate, with Jim Cramer calling it a “must buy” stock for 2026 as investors reassess where the durable profits in artificial intelligence may actually sit.
The call matters because the market has been oscillating between two competing AI narratives: one built around the compute-heavy infrastructure boom, and another focused on the security and governance costs created by faster model deployment. CrowdStrike CEO George Kurtz pushed the latter case hard, arguing that slowing the next wave of AI will not make today’s systems safer because the “genie’s out of the bottle” and dangerous models already exist. That framing helped CrowdStrike jump nearly 14% on Sept. 14 to a record high, while semiconductor shares sold off as investors worried that calls for a slower AI rollout could eventually curb chip demand.
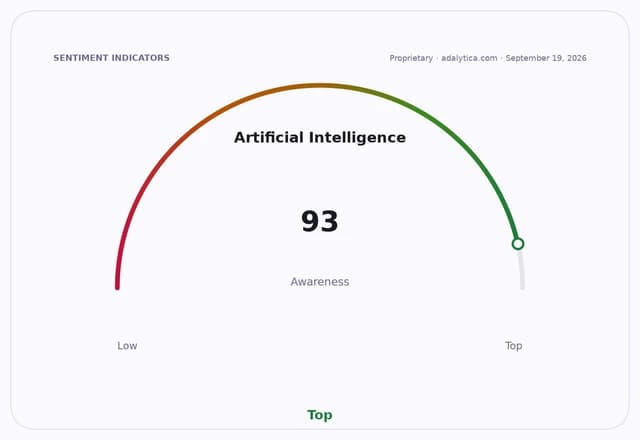
For investors, the key point is that cybersecurity spending is less exposed to the timing of frontier-model releases than chipmakers are. If the market’s first AI winners were Nvidia, Broadcom and other infrastructure providers, the next phase may increasingly reward companies that help enterprises defend against model misuse, data leakage and automated attacks. Kurtz’s argument effectively recasts AI safety from a theoretical policy issue into a budget line item for businesses that have already deployed generative tools and now need to secure them.
That is why Cramer’s endorsement resonated. He was not merely cheering a stock price move; he was aligning with a broader investment thesis that AI creates second-order demand for security software even if the pace of model innovation slows. CrowdStrike sits at the intersection of cloud security, endpoint defense and AI-driven threat detection, giving it a claim to secular growth that is harder to dismiss than the broad “AI infrastructure” trade, which has become more vulnerable to valuation pressure and regulatory headlines.
The market backdrop also helps explain the rotation. Nvidia has still held above key technical levels even after volatile swings, and Microsoft remains a core AI beneficiary, but both names have seen periods of consolidation as investors debate how much of the spending boom is already priced in. By contrast, CrowdStrike’s move suggests capital is beginning to search for AI-adjacent businesses with clearer recurring demand and less direct exposure to the capital-spending cycle in semiconductors and cloud infrastructure.
The bull case is straightforward: AI adoption increases attack surfaces, enterprise risk budgets rise, and security vendors with strong platforms take share. The bear case is that a fast run-up in the stock leaves little room for execution misses, while competition from larger platforms and in-house tools could slow expansion. Still, Kurtz’s point that dangerous models already exist gives the security thesis immediate relevance, even if regulators and AI labs eventually slow the frontier.
For investors, the message is that the AI trade is broadening. The next winners may not just be the companies selling picks and shovels for model training, but also the firms selling the locks, alarms and monitoring systems needed once those models are in production. CrowdStrike is now being priced as one of the clearest examples of that shift.
| Entity | Gains | Losses |
|---|---|---|
| CrowdStrike | ▲AI security demand | ▼valuation skeptics |
| Cybersecurity vendors | ▲higher enterprise budgets | ▼slower AI labs |
| Semiconductor stocks | ▲short-term less favored | ▼AI slowdown fears |
| Enterprises adopting AI | ▲better protection tools | ▼higher compliance costs |