Frankfurt’s DAX climbed back above 25,000 points on Friday after weaker-than-expected US labor market data cooled bets on further rate hikes and helped investors shake off fresh inflation worries.
DAX Rises Above 25,000 After Weak US Jobs Data
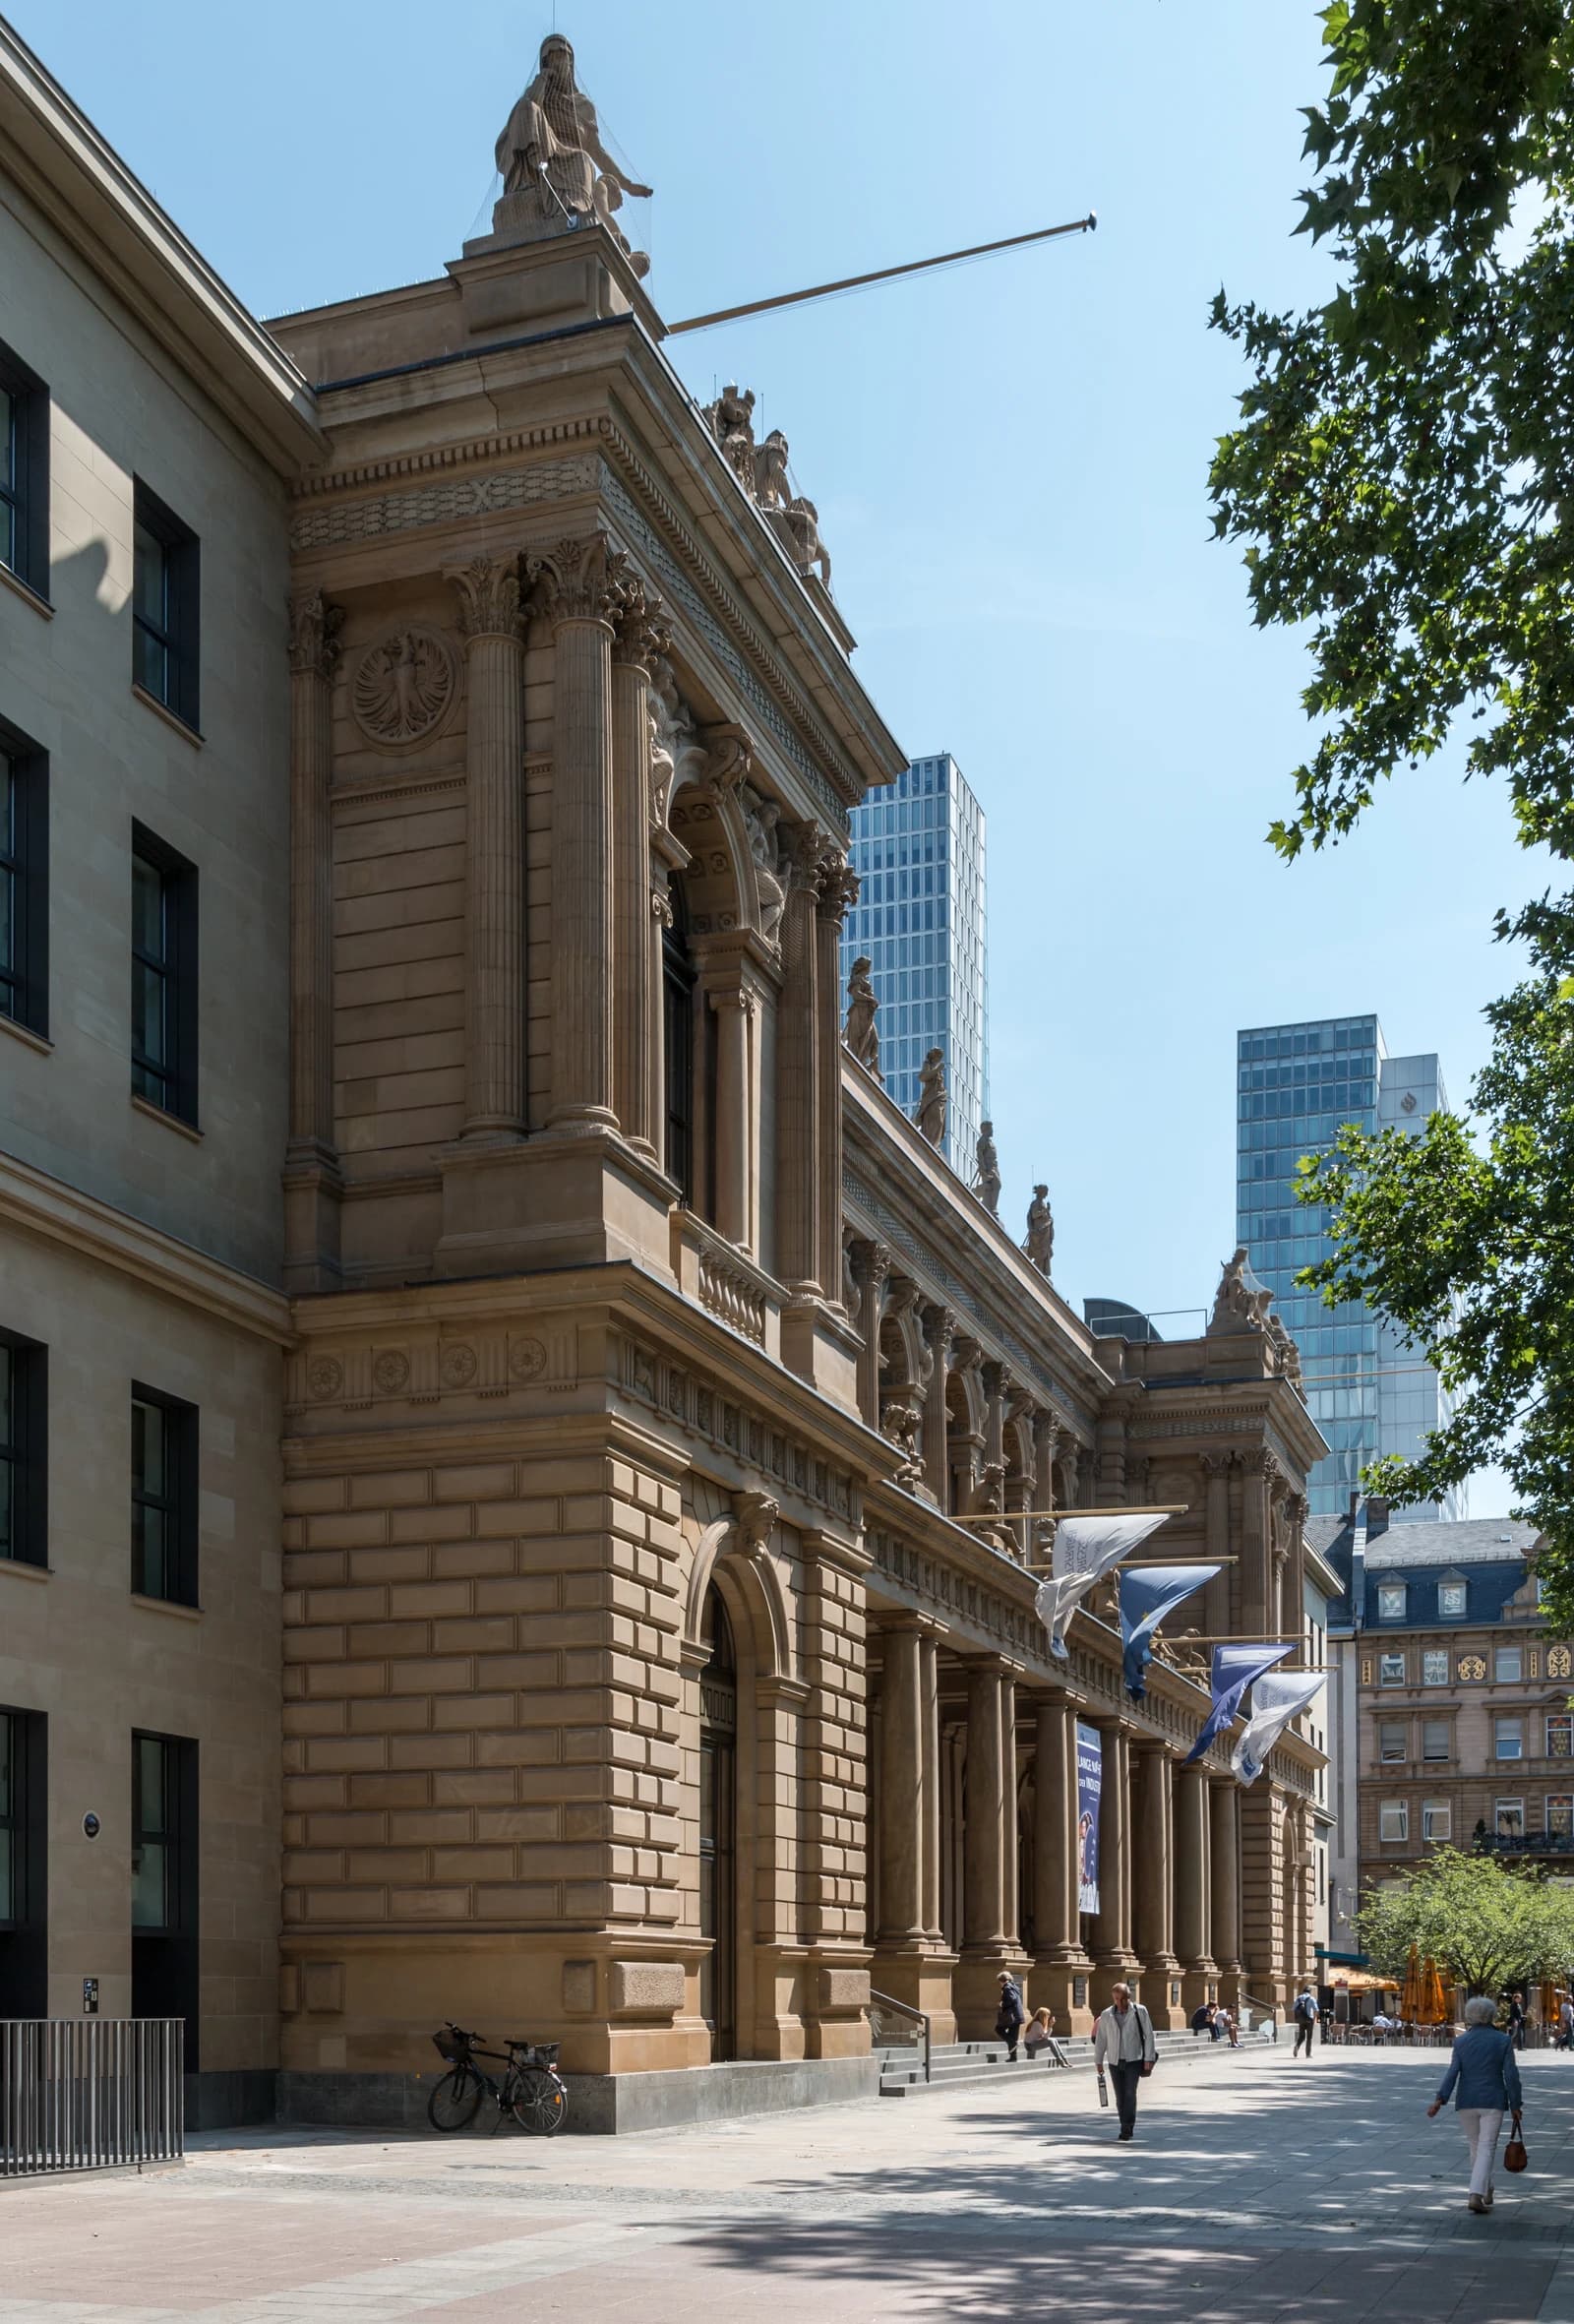
The benchmark rose 1.2% to 25,232 points, trimming its weekly loss to 0.7%, while the MDax advanced 0.8% to 30,491. The move followed a softer September US jobs report that showed payroll growth of just 90,000, below expectations, and unemployment edging up to 4.2%, reinforcing the view that the Federal Reserve has less reason to tighten policy further.
Sentiment IndicatorsⓘProprietary · adalytica.com · October 2, 2026
This is a snapshot — live sentiment, awareness and momentum for 130+ markets update continuously in the dashboard.Open AlphaPulse
For European markets, the significance is immediate. Lower US rate expectations ease pressure on global bond yields, support equity valuations and reduce the risk that the recent bond selloff spills further into stock markets. That was especially important in Frankfurt after the DAX had dropped below 25,000 on Thursday for the first time since July.
The relief extended beyond equities. Bond markets steadied after the recent selloff, including in French government debt, while weaker oil prices also helped calm inflation concerns in Europe. Eurozone inflation data earlier in the day did not add to the pressure.
Technology and AI-linked names led the rebound, with Infineon, Siemens Energy and Hochtief rising between 1.9% and 5.7%. The sector strength mirrored gains in US tech, where the Nasdaq 100 was again near a record, and supported the view that investors are still willing to pay up for growth when rate fears recede.
Adalytica’s S&P 500 trade signals showed neutral sentiment but extreme fear in awareness, while US Treasury bond signals pointed to extreme greed, underscoring how quickly positioning has swung toward bonds after the labor data. The US dollar signals remained in extreme fear, consistent with a weaker-rate narrative.
There were also stock-specific moves. Adidas and Puma recovered from an early dip after Nike cut its outlook and said in premarket trading its shares were down more than 8%, a reminder that the pain at Nike looks company-specific rather than a broad hit to the sportswear sector. In the MDax, Auto1 and Kion both fell after analyst briefings ahead of quarterly reports, while Hensoldt rose 3.1% after Kepler Cheuvreux called the defense electronics group a buying opportunity. Commerzbank fell 2% after RBC dropped its positive stance, with Deutsche Bank also under pressure as rising bond yields kept financials under strain.
For investors, the key question now is whether the labor slowdown is enough to lock in a softer Fed path without tipping recession fears higher. That balance will continue to drive Frankfurt trading into the next round of eurozone inflation data, US rate expectations and upcoming corporate earnings.
| Entity | Gains | Losses |
|---|---|---|
| DAX / European equities | ▲Lower rate fears, higher valuations | ▼Recent bond-yield pressure |
| Tech and AI-linked stocks | ▲Re-rating on easing policy worries | ▼Interest-rate sensitive value names |
| Adidas / Puma | ▲Nike weakness stays company-specific | ▼Early sector volatility |
| Commerzbank / Deutsche Bank | ▲— | ▼Higher bond-yield pressure, broker downgrade |