Egypt Gold Prices Fall as 21-Carat Drops to 6,370
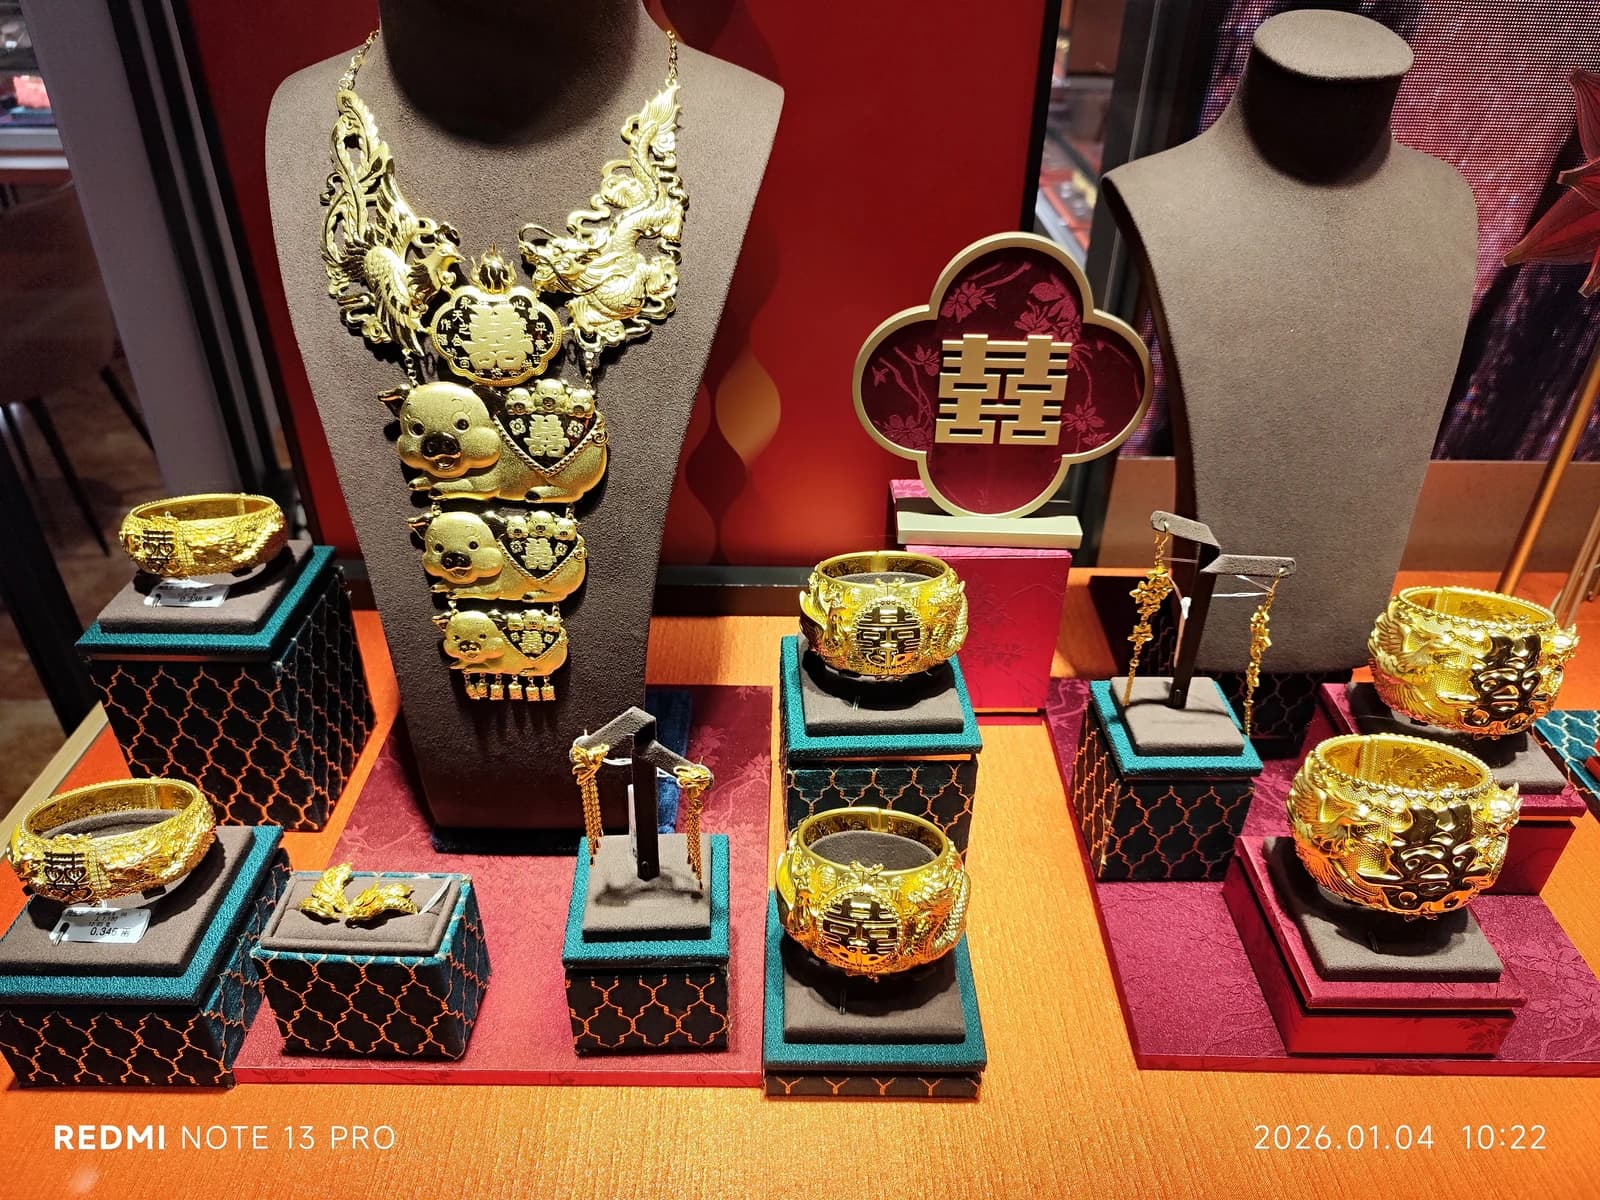
Gold prices in Egypt fell across all carat grades on Friday afternoon, with 21-carat jewelry gold dropping about 20 pounds to 6,370 Egyptian pounds a gram, even as the international price of bullion held near $4,360 an ounce.
The move matters because 21-carat is the benchmark for Egypt’s retail and wedding-jewelry market, where price changes quickly filter into household demand, shop inventories and working capital needs. A 20-pound drop is modest in isolation, but it extends a recent slide in domestic quotations at a time when global gold remains historically expensive and local buyers are already sensitive to affordability.
The broader backdrop is not a collapse in gold itself so much as a repricing inside a market that has been highly volatile this year. Global bullion has surged to record territory at different points and remains elevated, supported by persistent inflation worries, uncertainty over Federal Reserve policy and strong demand for monetary hedges. That has kept gold attractive to investors, but it also makes day-to-day jewelry demand more fragile in price-sensitive markets such as Egypt.
Local pricing reflects both the international benchmark and domestic cost pressures. Friday’s prices put 24-carat gold at 7,280 pounds a gram, 18-carat at 5,460 pounds and 14-carat at 4,246 pounds, with a gold pound coin at 50,960 pounds. Retail buyers typically pay an additional 100 to 200 pounds per gram in workmanship charges, a spread that can further suppress volume when prices soften.
For investors, the key question is whether the decline in Egyptian shop prices is a buying opportunity or a sign that physical demand is becoming more selective after a long rally. Gold-backed funds and bullion producers have benefited from the metal’s climb, but retail markets can diverge sharply when local wages and savings power fail to keep up with headline prices. That dynamic can compress margins for jewelers even when global prices stay firm.
Technically, gold futures remain elevated, and the recent pullback in Egyptian pricing looks more like a local adjustment than a new downtrend in the metal. The more important catalyst remains central-bank policy: any sign that U.S. rates will stay restrictive for longer would pressure non-yielding assets, while renewed recession or geopolitical stress would likely pull buyers back into bullion.
For now, the narrative is one of high gold prices, cautious consumers and a market searching for a level where physical demand can re-enter without undermining the metal’s broader investment appeal.
| Entity | Gains | Losses |
|---|---|---|
| Egyptian jewelry buyers | ▲Slightly lower entry prices | ▼Still-high total purchase cost |
| Jewelry retailers | ▲Easier inventory turnover | ▼Lower per-gram margins |
| Gold investors | ▲Support from safe-haven demand | ▼Volatility from rate expectations |
| Global bullion sellers | ▲Elevated benchmark prices | ▼Slower retail demand in price-sensitive markets |