EUR/CHF rises on ECB-SNB rate gap
The euro’s grind higher against the Swiss franc is being driven by one clean macro trade: the European Central Bank is offering a far better yield than the Swiss National Bank, and that gap still points to euro strength.
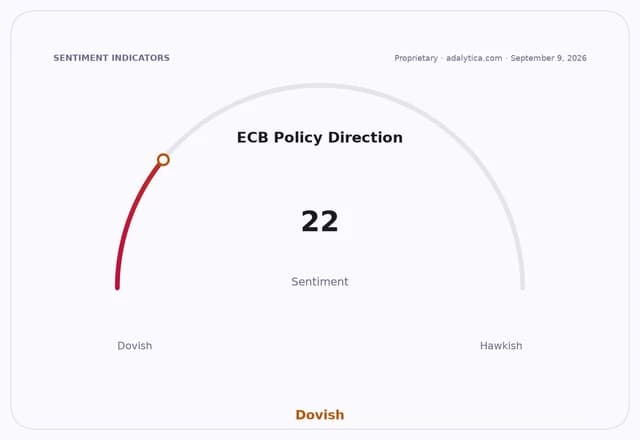
For investors, that matters because EUR/CHF is not just a quiet cross in consolidation. It is a barometer of how aggressively capital wants to own European assets when the carry on the euro remains meaningfully richer than the franc. With the ECB policy rate at 2.4% versus roughly zero in Switzerland, the incentive to stay long euros and avoid francs remains intact, even before Thursday’s ECB decision and press conference.
That yield spread is the heart of the narrative. Deutsche Bank now expects the ECB to hike this week and again by 25 basis points in December, a sign that persistent energy-linked inflation is still keeping policy restrictive. The Swiss side offers little counterweight. As long as the SNB remains anchored near zero, the franc’s traditional safe-haven appeal has to compete with a widening income advantage for the euro.
The market has not fully priced that asymmetry. EUR/CHF is hovering under 0.9450 resistance, and a sustained move through 0.95 could trigger a more decisive break higher. The latest price action in the euro against the franc shows a pair that is consolidating, not reversing, and that usually favors the direction of the underlying carry trade. Adalytica’s Euro Trade Signals show sentiment in fear territory even as awareness remains elevated, a mix that often appears before a positioning reset rather than a trend top.
The broader setup also argues for patience on the long side. FX volatility signals remain elevated enough to keep traders attentive, but not so disorderly as to negate the rate-differential story. In practical terms, that means pullbacks still look like opportunities for investors who want exposure to a stronger euro without taking outright directional risk in the dollar cross.
The near-term catalyst is Thursday’s ECB meeting. If policymakers reinforce the market’s expectation that rates need to stay restrictive, the euro should keep grinding higher against the franc. My view is that the market underestimates how persistent this divergence can be: Switzerland is still near zero, Europe is still earning a yield premium, and that is the kind of macro imbalance that can carry EUR/CHF through resistance and into a fresh uptrend.
| Entity | Gains | Losses |
|---|---|---|
| Euro long positions | ▲Yield pickup | ▼Near-term volatility |
| Swiss franc holders | ▲Safe-haven bid | ▼Carry disadvantage |
| ECB hawks | ▲Tighter policy credibility | ▼Growth sensitivity |
| SNB | ▲Stable inflation optics | ▼Franc strength support |