Fed Rate Hike Odds Rise Ahead of CPI Report
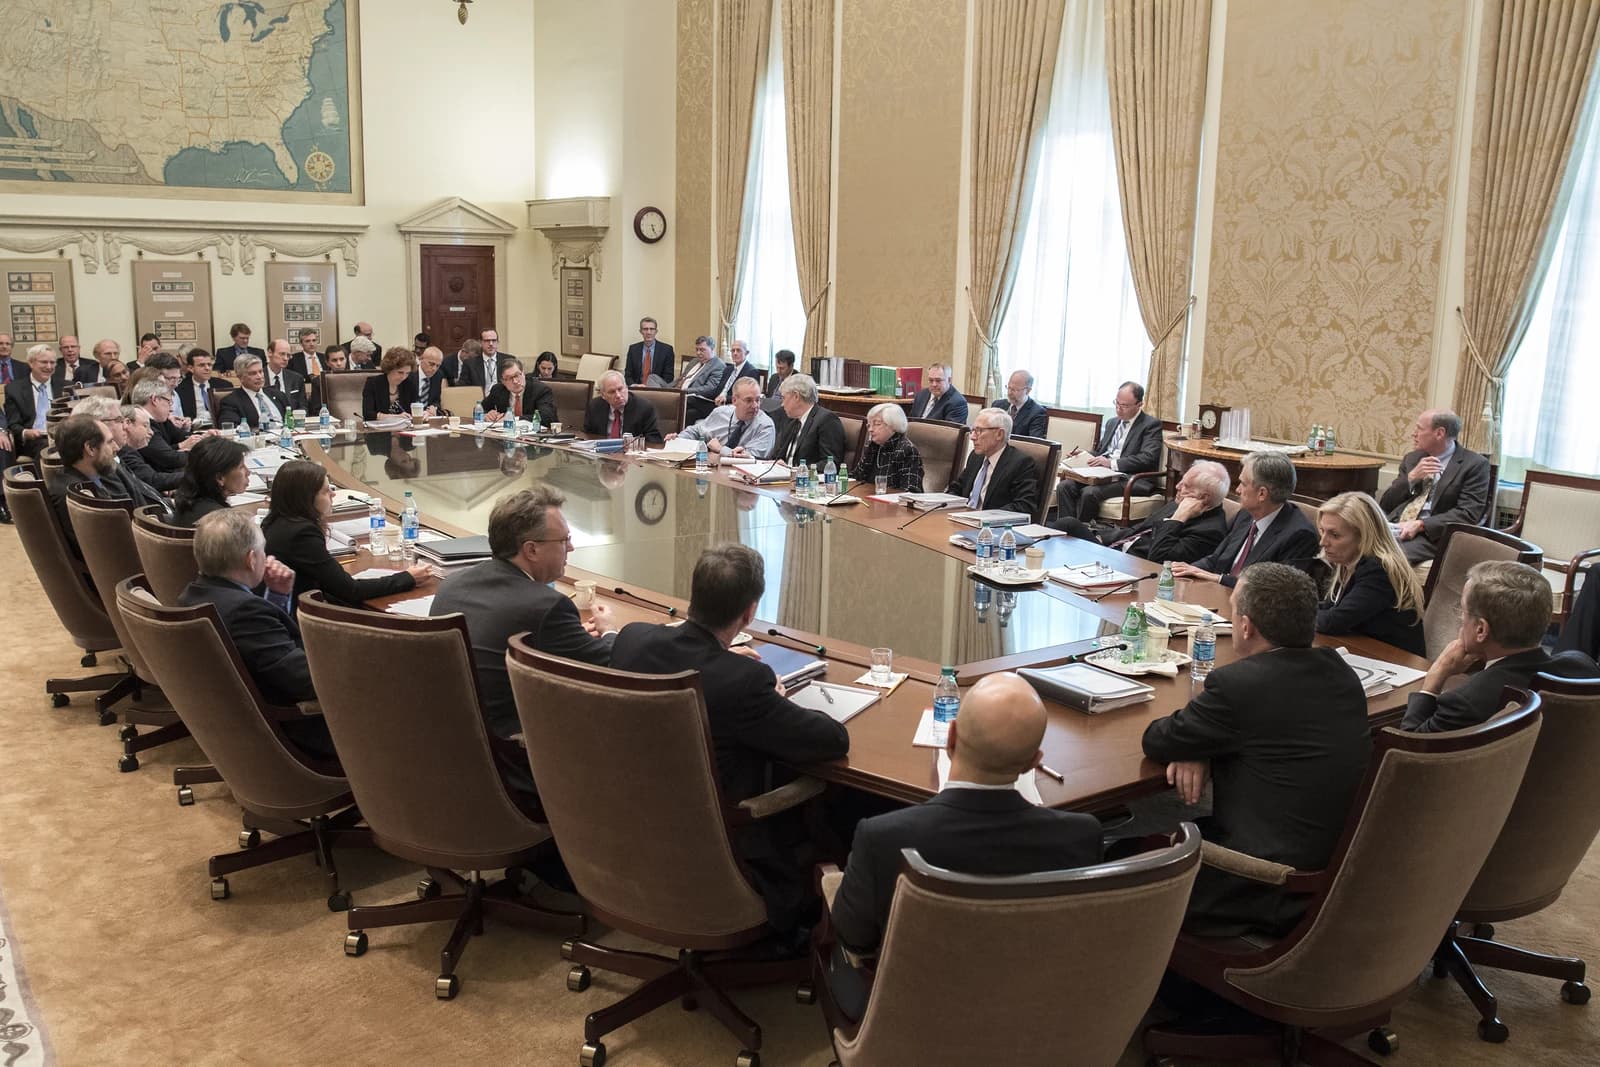
The Federal Reserve may be one hot inflation report away from a rate hike next week, with Friday’s consumer price data set to decide whether September policy stays on hold or turns hawkish.
That matters because markets are already close to pricing in a move: federal funds futures now imply a 58% chance of a hike at the Sept. 16 meeting, after August payrolls unexpectedly showed 162,000 jobs added and shifted the labor-market narrative from stagnant to resilient. A CPI print above expectations would strengthen the case that price pressures are not easing fast enough for policymakers to wait, especially after the Fed has already seen evidence that growth and hiring remain firmer than many expected.
For investors, the stakes are broader than one meeting. A hotter CPI would likely push Treasury yields higher and pressure rate-sensitive assets, including utilities, small caps and longer-duration bonds. It would also raise borrowing costs for households and businesses, potentially slowing credit demand and squeezing corporate margins, while making cash and fixed income relatively more attractive versus equities.
The market reaction could be sharp even if the longer-term outlook changes less than the headline reaction suggests. SPY, the S&P 500 ETF, has held up near 762, still above its 200-day moving average, but it has lost momentum in recent sessions and its relative strength reading has eased. IWM, the Russell 2000 ETF, looks more vulnerable, trading below both its 50-day and 200-day moving averages, a sign small caps remain exposed to higher financing costs and tighter financial conditions. Treasury bonds are already drawing strong interest ahead of the data, with TLT trading around 81.73 and Adalytica’s U.S. Treasury Bonds Trade Signals showing “Extreme Greed,” reflecting a market leaning toward lower prices and higher yields if inflation surprises on the upside.
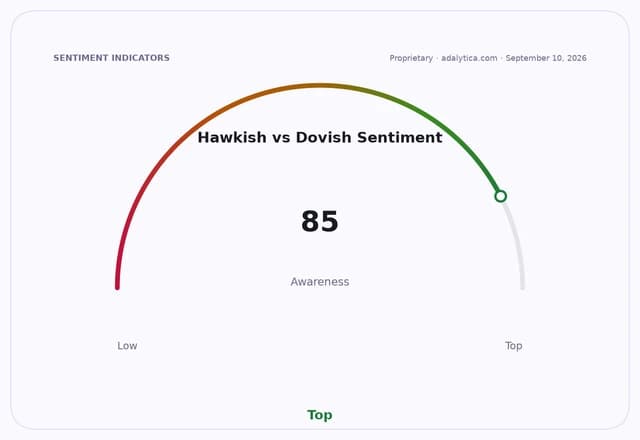
The narrative connecting the data is straightforward: the Fed has been handed a stronger labor-market signal and now needs one more inflation confirmation before moving. If CPI is tame, policymakers may still pause and preserve optionality. If it is hot, next week’s decision could shift from a debate to a near-lock, and that would ripple across rates, equities and credit.
For long-term investors, the question is not whether volatility rises around the release — it probably will — but whether a September hike meaningfully changes the underlying earnings and growth path. For rate-sensitive parts of the market, however, Friday may be the last and most important data point before the Fed decides.
| Entity | Gains | Losses |
|---|---|---|
| Fed hawks | ▲Stronger case for a hike | ▼Patience and pause advocates |
| Treasury bears | ▲Higher yields if CPI runs hot | ▼Bondholders and TLT holders |
| Large-cap equities | ▲Better resilience than small caps | ▼Rate-sensitive sectors |
| Small caps / IWM | ▲None if rates rise | ▼Higher borrowing costs |