Fed rate hike eases Treasury yield pressure
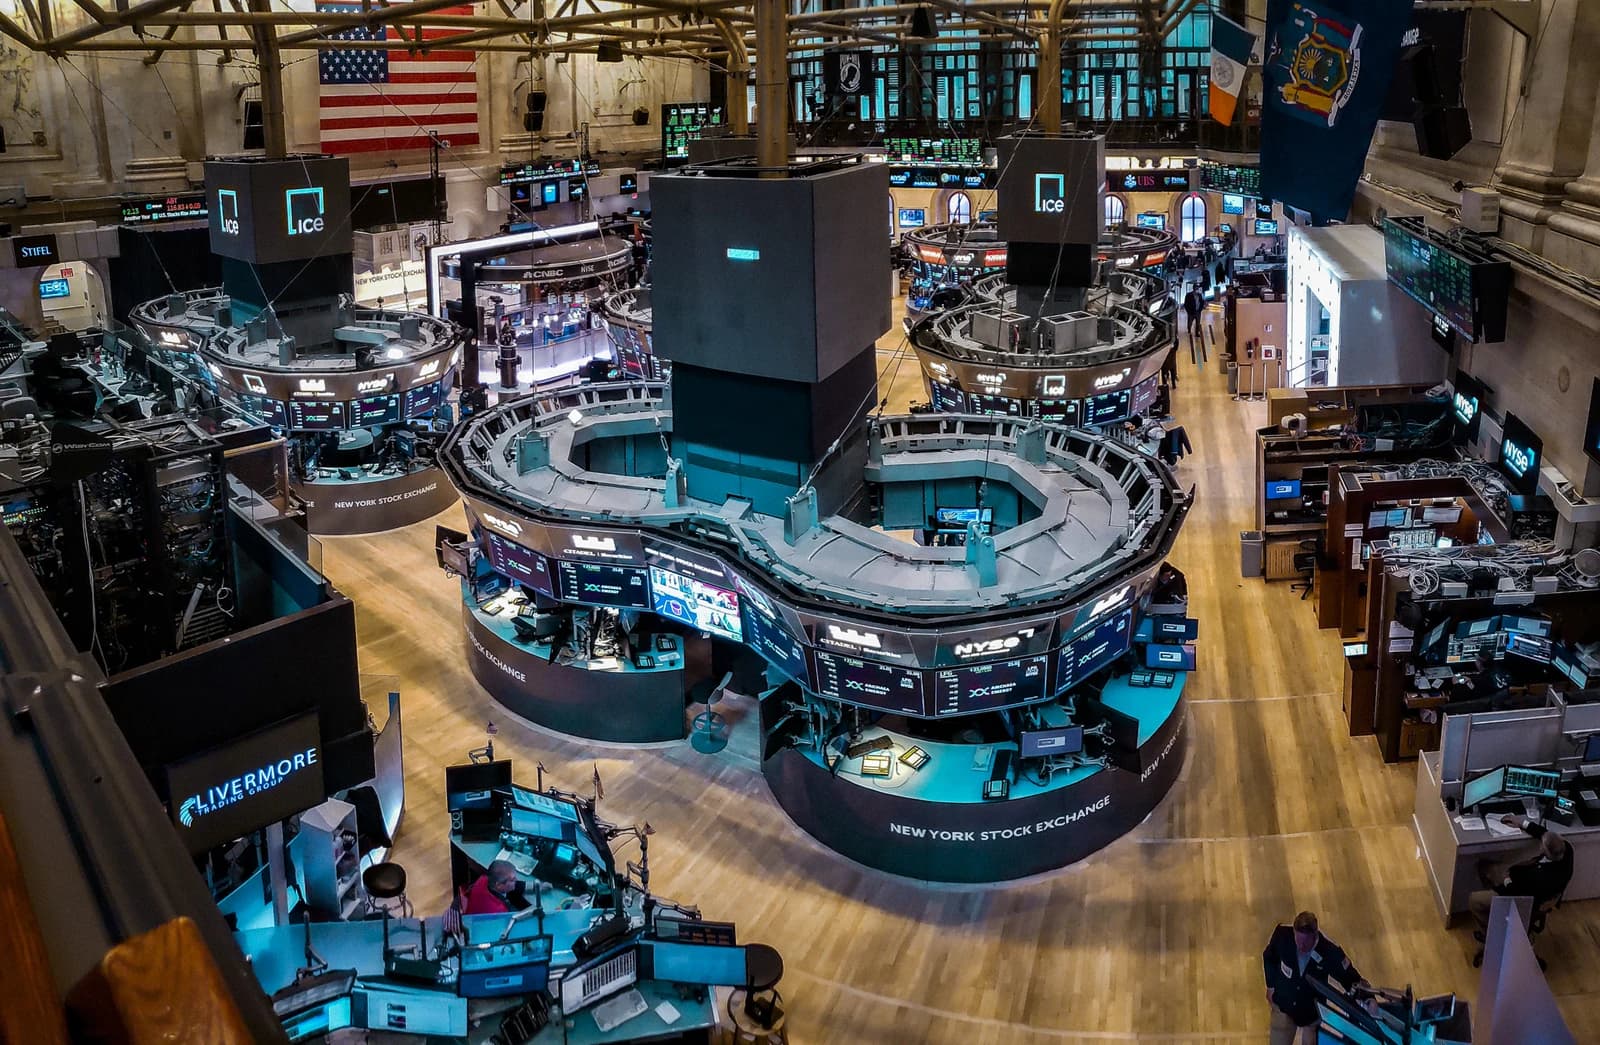
The Federal Reserve appears to have checked the bond market’s most powerful challenge to its authority, with long-dated Treasury yields easing after this week’s 25-basis-point rate increase and signaling that investors are no longer forcing an immediate fiscal or inflationary reckoning.
That matters because the “bond vigilantes” — traders who punish policy makers by selling government debt and pushing yields sharply higher — had been driving the macro conversation in recent weeks. Their pressure had raised financing costs across the economy and threatened to complicate both the Fed’s policy path and Washington’s broader economic agenda. Instead, the central bank’s move, coupled with a more measured interpretation from markets, has helped stabilize the long end of the curve.
The 10-year Treasury yield, a key benchmark for mortgages, corporate borrowing and asset valuations, has edged down to about 4.98% in the latest forecast from 5.00% earlier this week, while the 2-year yield slipped to 0.23% in the same projection. The curve remains modestly positive, but the more important point for investors is that the violent upward move in longer-dated yields has paused. That is exactly the kind of response the Fed needed if it wanted to avoid a broader tightening in financial conditions doing its work for it.
The bond market’s tone also reflects a shift in expectations around the Fed’s reaction function. Markets are now pricing in further tightening rather than a one-off adjustment, with investors expecting three additional rate hikes by the end of 2027. Kevin Warsh’s comment that the Fed had “removed a degree of accommodation” reinforced that view: policy is still restrictive enough to keep pressure on inflation, but not so abrupt as to trigger a disorderly repricing in Treasuries.
For investors, that distinction matters across asset classes. The stabilization in yields supports duration-sensitive assets after a bruising period, while reducing near-term stress for equities that have been vulnerable to higher discount rates. Bond proxies such as long-duration Treasuries have also started to recover from recent weakness. The iShares 20+ Year Treasury Bond ETF, TLT, closed at $81.69 on Monday after touching $81.25 on Friday, still below its 50-day moving average of $82.23 and 200-day average of $84.34, but no longer in free fall. The short-end proxy, SHY, was little changed at $81.31, underscoring how the market is now focused less on the policy rate itself than on whether the long end will keep rising.
The broader macro backdrop is not benign. Oil has been volatile on Middle East tensions, diesel prices remain a political inflation concern, and the Bank of Japan’s rate increase to 1.25% on Friday has added another cross-border tightening impulse. But the Fed’s latest move suggests it retains room to manage the narrative, at least for now. If incoming data on September flash PMIs and August durable goods orders show the economy remains resilient, the central bank may keep tightening without losing market control. If growth softens, the pause in long-term yields could prove temporary.
For now, the key message for investors is that the bond vigilantes have not vanished, but the Fed has shown it can still set the terms of engagement. The next test is whether yields remain contained once economic data resume driving the tape.
| Entity | Gains | Losses |
|---|---|---|
| Federal Reserve | ▲Policy credibility | ▼Yield-spike pressure |
| Treasury bondholders | ▲Stable long-end yields | ▼Less volatility premium |
| Borrowers | ▲Lower financing stress | ▼Less inflation hedge |
| Bond vigilantes | ▲Fading market leverage | ▼Less ability to force repricing |