France social housing project and incentives plan
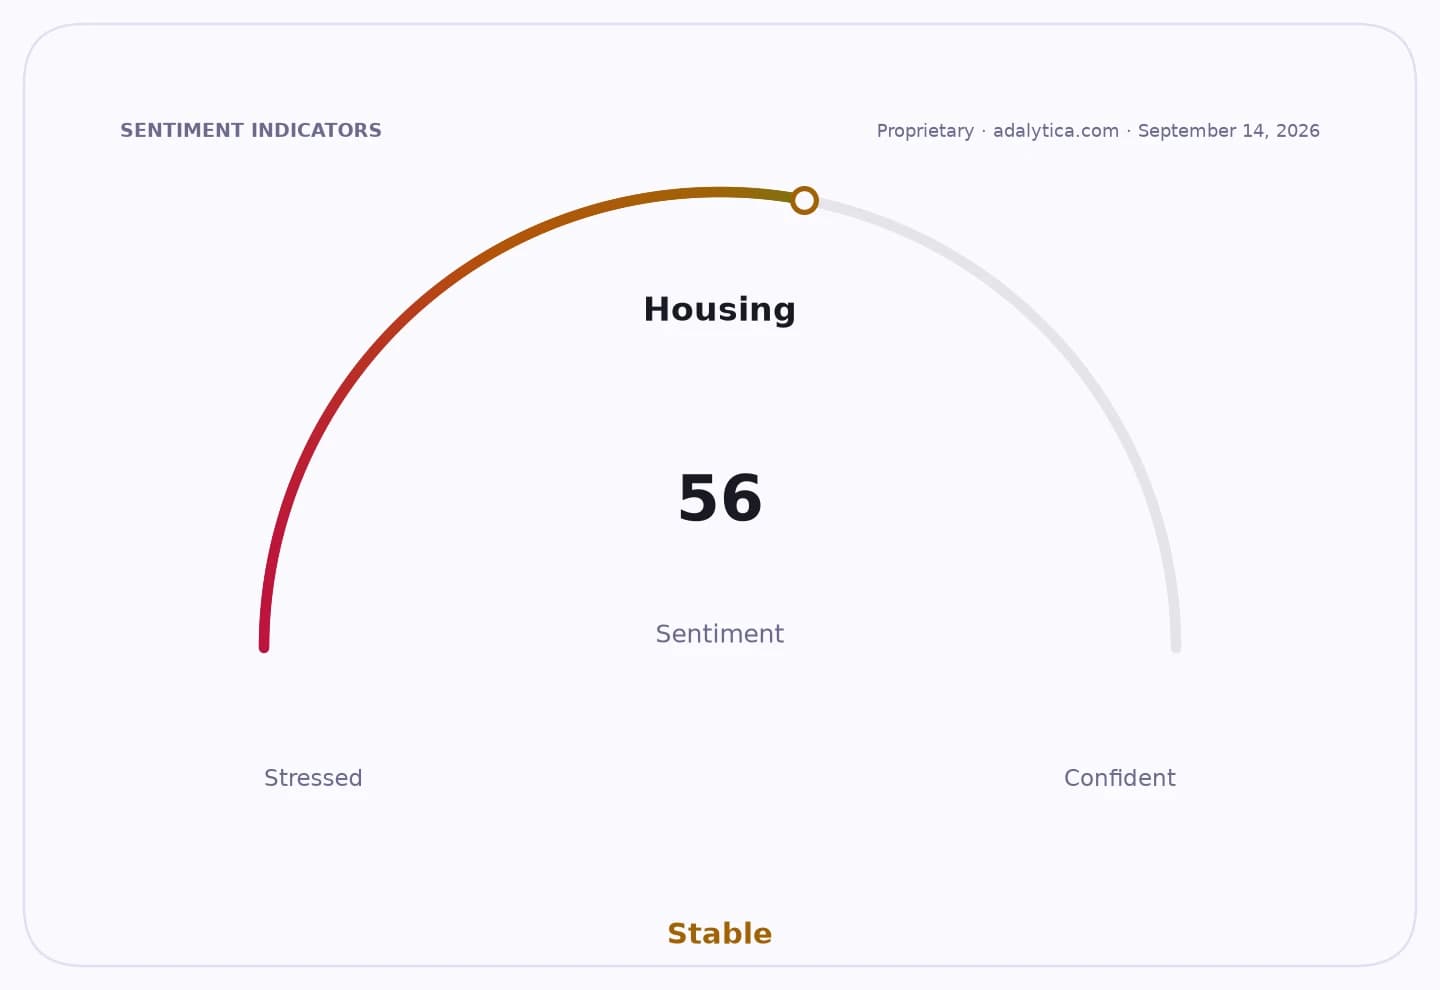
A proposed 340-unit housing project in Saint-Martin-d’Hères highlights how France’s worsening supply crunch is forcing policymakers to lean harder on incentives for social housing developers.
The scheme — four buildings, 13 floors and roughly 340 homes — comes as the Ministry of Construction proposes amending Resolution 201/QH15 to give investors more support in social housing projects. The goal is to strip out bottlenecks that have slowed approvals, delayed starts and left viable developments stuck in the pipeline.
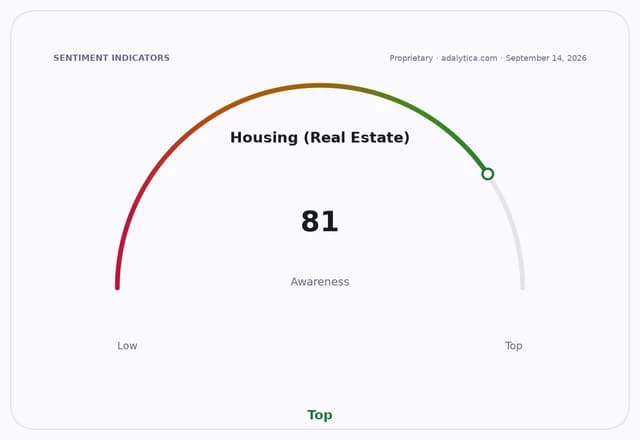
That matters economically because housing construction remains one of the fastest ways to feed demand into local economies, from builders and materials suppliers to utilities and municipal services. It also matters for households: with inflation still elevated and rents under pressure, every additional unit helps ease a shortage that has become a structural drag on affordability.
Official price data show French consumer inflation remains above the level policymakers want, even if it has cooled from earlier peaks. Housing costs are a key part of that equation, and supply-side relief is now a more important lever than rate cuts alone.
The broader backdrop is one of tight housing supply and uneven execution. Developers continue to run into planning delays, infrastructure bottlenecks and administrative friction, while governments are under pressure to move faster on affordable stock.
For investors, the story points to more support for developers exposed to social housing, construction and urban regeneration, while it reinforces the risks for landowners and builders dependent on slow approvals. It also keeps focus on whether the promised incentives translate into faster project starts, which would be the real test of the policy shift.
The next catalyst is legislative progress on the incentives package and any sign that local authorities can clear sites like Saint-Martin-d’Hères more quickly. If the measures move ahead, the housing market could see a modest but meaningful lift in supply over the coming months.
| Entity | Gains | Losses |
|---|---|---|
| Social housing developers | ▲Easier approvals | ▼Less red tape |
| Homebuyers/renters | ▲More supply | ▼Housing scarcity |
| Construction firms | ▲More project pipeline | ▼Delayed starts |
| Local blockers/bureaucracy | ▲— | ▼Less leverage |