Gold Falls as US Yields Rise on Rate Bets
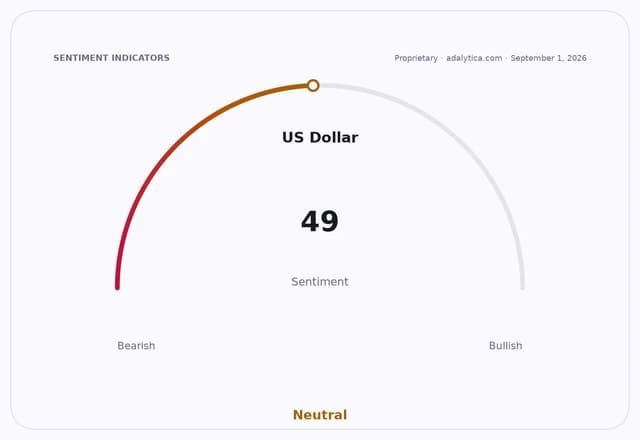
Gold extended its decline as traders priced in a greater chance of higher US interest rates, a shift that matters because it lifts Treasury yields, supports the dollar and raises the opportunity cost of holding a non-yielding asset.
The move has been reflected in the bond market, where the US 2-year Treasury yield has climbed to 4.34% from 4.19% on Aug. 26, while the 10-year has risen to 4.73% from 4.66%. Higher front-end yields are particularly important for gold because they usually move fastest when investors see the Federal Reserve leaning more hawkish. For bullion, that is a direct headwind.
Gold futures slipped to $4,393.9 on Sept. 1 from $4,478.1 on Aug. 28, pulling the metal further below its recent highs. GLD, the largest US gold-backed exchange-traded fund, also eased to $398.75 from $408.89 over the same period. The retreat came even after the metal had logged a strong run earlier in the year, underscoring how quickly bullion can lose momentum when rate expectations shift.
The pressure is not only coming from rates. Adalytica’s Gold Fear & Greed Index collapsed to 1, or “Extreme Fear,” from 12 a day earlier and 64 a week earlier, showing that short-term sentiment has turned sharply defensive. That kind of fear reading often accompanies forced de-risking, especially after a crowded trade has become vulnerable to profit-taking.
The case for further downside is straightforward: if the Fed keeps signaling inflation vigilance, real yields can stay elevated and the dollar can firm, both of which tend to weigh on gold. The bullish counterargument is that rate-hike expectations can reverse quickly if incoming data softens or if policymakers walk back hawkish guidance. Gold also retains its role as a hedge against policy mistakes, financial stress and geopolitical shocks, which can bring buyers back even during selloffs.
For investors, the key question is whether this is a pause in a broader bull market or the start of a deeper correction. Gold miners such as Newmont and broader precious-metals holders remain highly sensitive to every move in yields and Fed rhetoric, while gold-linked products will likely stay volatile until the market gets clearer direction on the policy path. For now, the narrative is being set by the same force that has pressured the metal throughout past tightening cycles: when rates rise, gold usually pays the price.
| Entity | Gains | Losses |
|---|---|---|
| US Treasury yields | ▲Higher returns | ▼Gold bulls |
| US dollar | ▲Support from rate bets | ▼Gold prices |
| Fed hawks | ▲Policy credibility | ▼Precious-metals traders |
| Gold miners / GLD holders | ▲Hedge demand if stress returns | ▼Near-term momentum buyers |