Italy Services PMI Rises to 55.2 in August
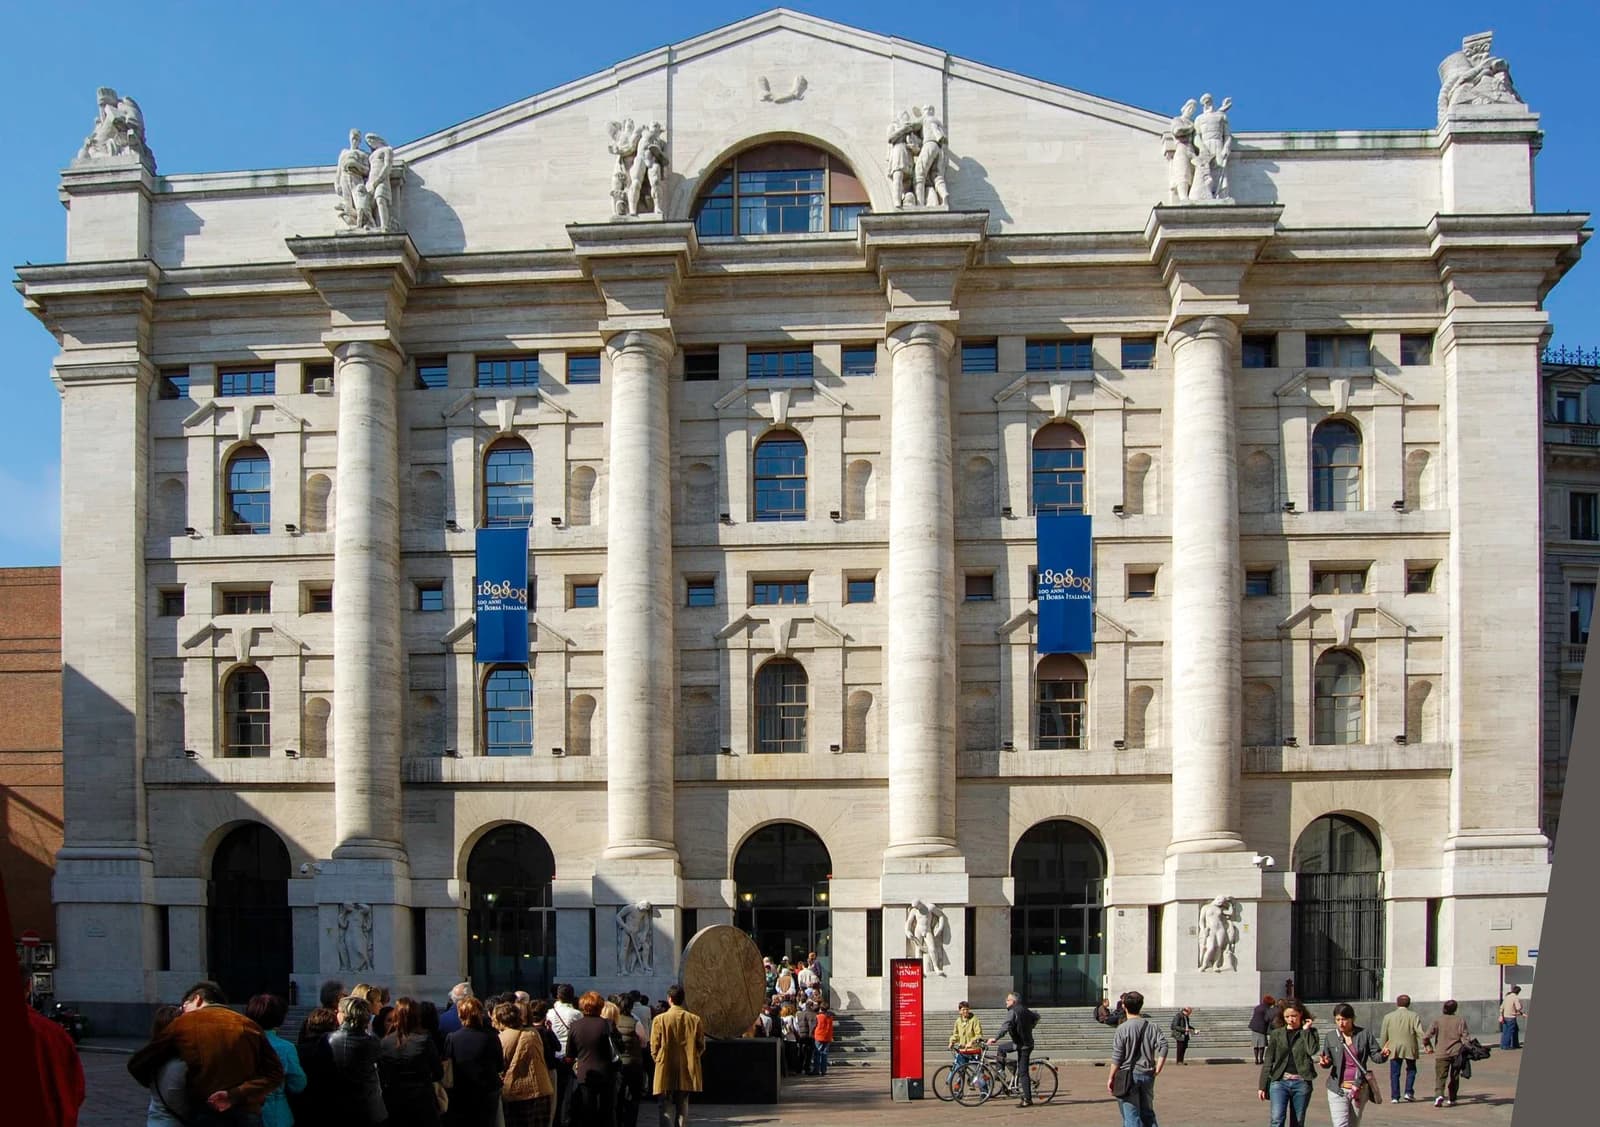
Italy’s services sector gained fresh momentum in August, with the PMI rising to 55.2 from 52.5 in July, its strongest reading in nearly three and a half years and a sign that the country’s third-largest economic engine is still expanding at a healthy pace.
That matters because services make up the bulk of Italy’s economy, and a move deeper into expansion territory suggests the recovery is being driven more by domestic orders than by outside demand. S&P Global Market Intelligence said the rise in activity and new business put the sector on track for what could be its best quarter of the year, while export orders increased only modestly, underscoring that the improvement is mostly homegrown.
For investors, the reading is encouraging for Italian consumer-facing businesses, banks and domestic cyclicals that depend on steady local demand. It also supports the case for the broader euro zone economy, where stronger service activity can offset weakness in manufacturing. If services continue to hold above the 50 threshold, Italy is less likely to slip into a softer growth patch, which can help sentiment toward Italian equities, sovereign debt and the euro in the months ahead.
The report was not uniformly upbeat. Cost pressures remained stubbornly high, hiring was only moderate and firms appeared less aggressive on pricing, a combination that suggests margins may still face strain even as volumes improve. That is the key trade-off for long-term investors: better activity is supportive, but sustained inflation in input costs can limit the speed and breadth of earnings gains.
Still, the bigger picture is constructive. A services PMI at 55.2 tells investors Italy is entering the second half of the year with real economic traction, not just statistical noise. For patient investors, that keeps Italy’s domestic growth story worth watching.
| Entity | Gains | Losses |
|---|---|---|
| Italian services firms | ▲Higher orders, stronger activity | ▼Cost pressure, margin strain |
| Domestic consumers and banks | ▲Better demand, healthier credit activity | ▼Higher service prices over time |
| Italian equities | ▲Better growth backdrop | ▼Less pricing power for squeezed firms |
| Export-oriented businesses | ▲Limited benefit from domestic-led rebound | ▼Slower export demand growth |