Japan opposition fragmentation deepens as centrists shrink
Japan’s fragmented opposition is becoming a market and policy risk as the centrist camp loses lawmakers and the Communist Party emerges as the largest opposition force, underscoring a widening vacuum on the other side of the ruling coalition.
The development matters because a weaker, more divided opposition makes it harder to build momentum for fiscal restraint, tax changes or structural reform, while also reducing the odds of a credible alternative government. For investors, that can mean more policy drift in Tokyo, less pressure on the ruling bloc and a slower path to changes that affect everything from wages and consumption to bond issuance and the yen.
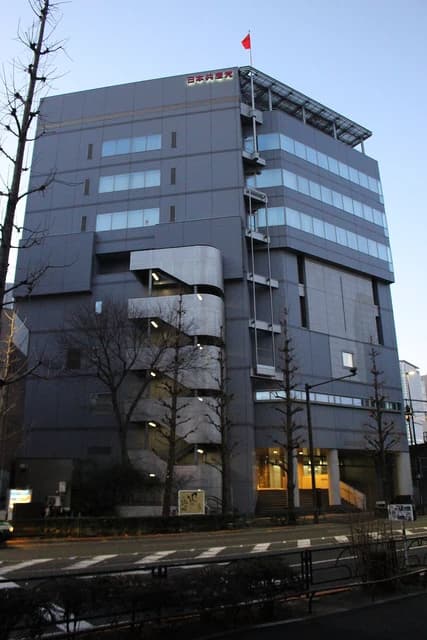
The seed of the shift is the collapse of the once-middling “centrist” space, with only one lawmaker left in the camp and party funding in the 1.2 billion yen range doing little to stop the erosion. That leaves the Communist Party, long a protest vote rather than a governing option, as the biggest opposition party by sheer numbers — a symbolic change that also highlights how far Japan’s opposition has splintered.
Markets typically care less about opposition branding than about whether a legislature can force debate on fiscal discipline, defense spending, energy policy and inflation relief. With the Bank of Japan already navigating a still-elevated inflation backdrop — Japan’s consumer prices have climbed far above pre-pandemic levels — the absence of a strong centrist counterweight could make it easier for the government to keep pushing stimulus-friendly policies.
That backdrop comes as global rate markets remain sensitive to Japan. The U.S. 10-year Treasury yield is around 4.95%, while Japanese equity proxies have held firm, with the EWJ ETF near 97.97 and the DXJ ETF at 177.77, both above their 50-day moving averages. The moves suggest investors are still positioning for Japan’s policy mix to remain supportive even as political fragmentation deepens.
Adalytica’s Global Stability Sentiment gauge shows fear at 30, down 42 points over the past month, while U.S. equity trade signals remain in extreme fear territory. That points to a market environment already primed for any political surprise in Tokyo to be read through the lens of policy continuity, currency trends and risk appetite.
The next catalyst is whether opposition parties can regroup around a clearer fiscal or reform agenda, or whether Japan heads deeper into one-party dominance with a weakened check on policymaking.
| Entity | Gains | Losses |
|---|---|---|
| Ruling coalition | ▲Easier passage of policy | ▼Stronger parliamentary pressure |
| Communist Party | ▲Largest opposition status | ▼Governing credibility |
| Centrist opposition bloc | ▲— | ▼Lawmakers, relevance |
| Japanese investors | ▲Policy clarity from continuity | ▼Reform momentum |