Kazakhstan Central Bank Eyes BNPL Rules
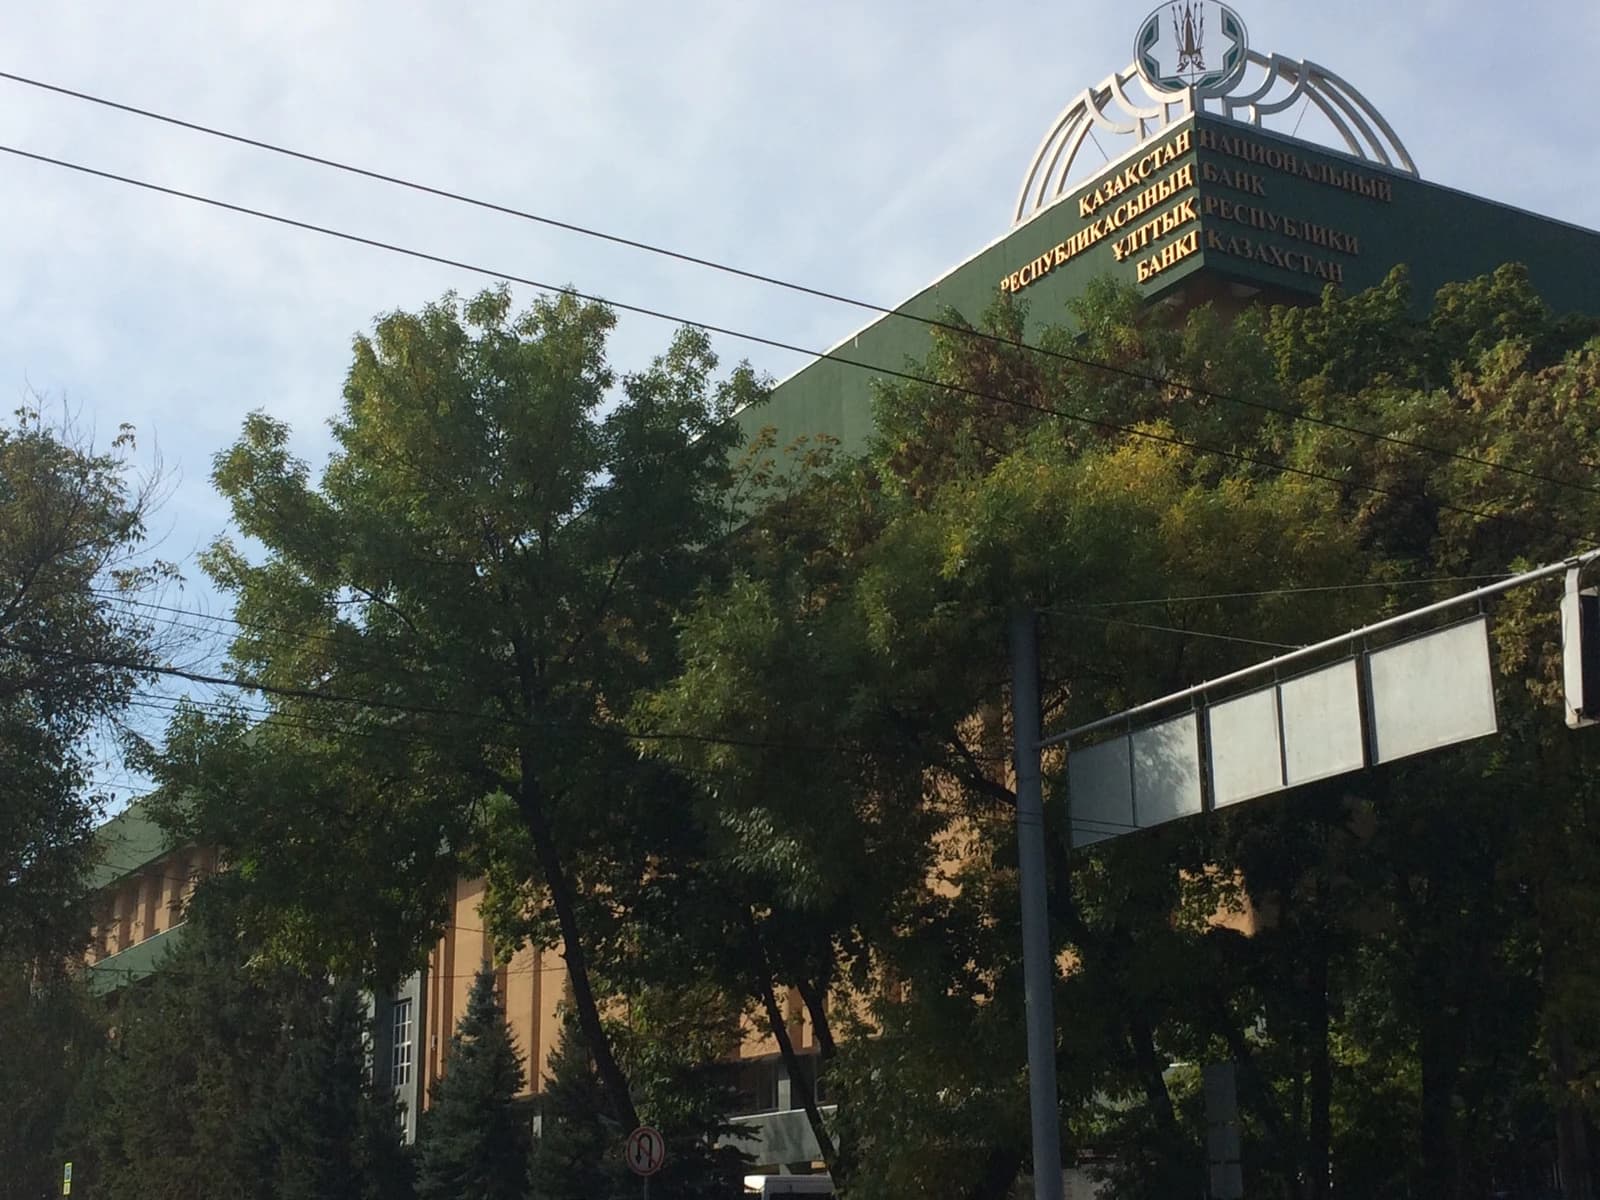
Kazakhstan’s central bank is moving toward tighter oversight of the country’s fast-growing installment and BNPL market, a shift that could reshape how consumers borrow and how lenders, merchants and developers book sales.
The National Bank of Kazakhstan has put out a discussion paper warning that many installment deals look and behave like consumer credit, but are often structured outside the rules that apply to banks and microfinance firms. That creates a blind spot for regulators and other lenders, while leaving shoppers exposed to hidden fees, open-ended penalties and weaker protections on returns and disputes.
For the economy, the issue is not just consumer rights. The central bank says non-financial installment plans can build up “hidden” debt that does not show up in credit bureau data, making it harder to assess households’ true leverage. That matters in any credit-driven economy, because unchecked installment lending can inflate consumption in the short run while masking stress in the household balance sheet.
The bank is not proposing an outright ban. Instead, it wants an 8-week public consultation, with comments due by Nov. 3, 2026, on options ranging from simple disclosure rules and reporting to credit bureaus to licensing and other hard limits. It also floated the idea of checking borrowers’ ability to repay and setting maximum installment terms depending on whether the purchase is a phone, a car or a home.
That broadens the stakes well beyond retail gadgets. The central bank singled out cars and housing, where installment structures can leave buyers with large obligations while the asset remains legally owned by the seller until payment is complete. In property, the warning is especially important: if a buyer is using a pay-over-time arrangement instead of a standard housing contract, the usual safeguards may be weaker if a developer runs into trouble.
Investors should care because regulation can change the economics of a booming consumer-finance niche very quickly. BNPL and installment providers tend to win on speed and convenience, but they also rely on light-touch underwriting and easy checkout flows. Stricter rules would likely raise compliance costs, slow growth and favor firms with bank-like risk controls over smaller non-bank players.
The move also fits a wider global pattern. Regulators in Europe, Australia and Russia have already started bringing BNPL closer to traditional lending rules, arguing that a product designed to feel frictionless still creates real debt. Kazakhstan appears to be heading in the same direction, but with a more measured approach that tries to preserve the social value of installment buying while forcing the market to become more transparent.
For long-term investors, the takeaway is straightforward: this is less about a crackdown than a maturation step. If Kazakhstan follows through, the winners are likely to be lenders and platforms that can prove they underwrite well, disclose clearly and integrate with credit reporting systems. The losers are opaque providers that have benefited from operating in the seams between consumer commerce and credit regulation. Worth watching closely.
| Entity | Gains | Losses |
|---|---|---|
| Consumers | ▲Clearer terms | ▼Hidden fees and weaker protections |
| Banks and MFOs | ▲More level playing field | ▼Faster competition from unregulated BNPL |
| BNPL providers with strong controls | ▲Regulatory legitimacy | ▼Cheap growth from light oversight |
| Opaque installment sellers | ▲None | ▼Higher compliance, slower sales |