London Stock Exchange Group is preparing a large three-year bond offering as global borrowing costs stay elevated, a move that underlines how even top-tier market operators are tapping debt now before rates climb further.
London Stock Exchange Group prepares three-year bond sale
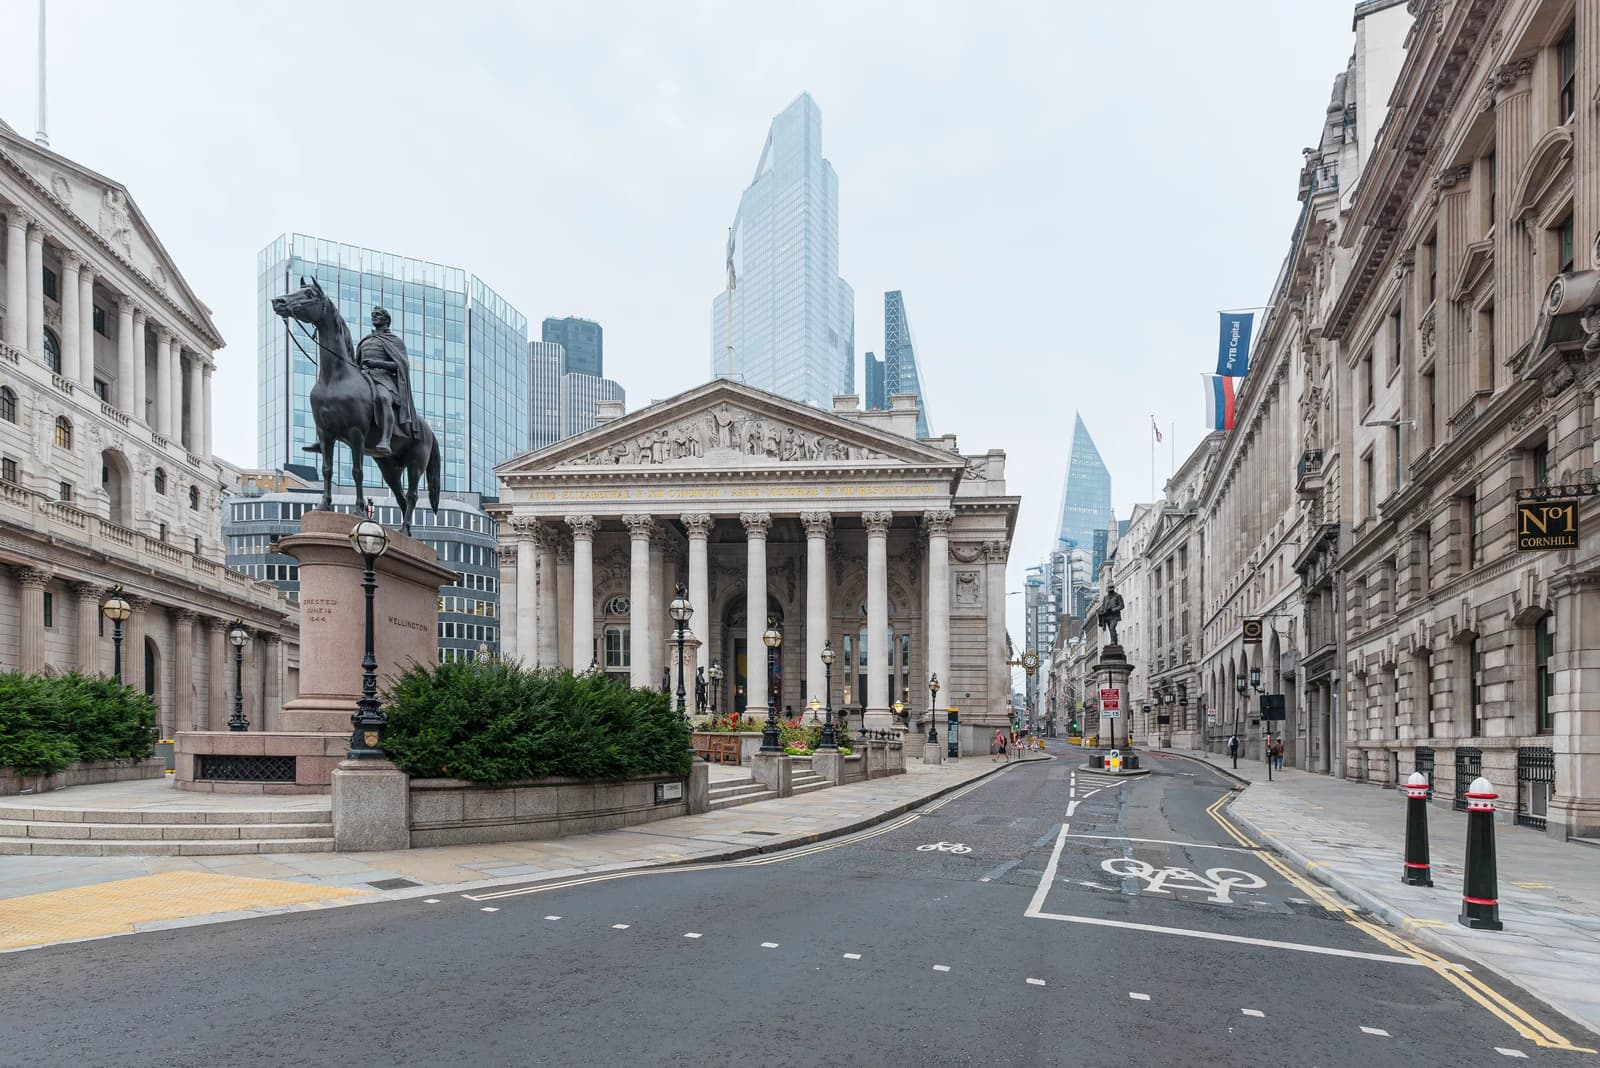
The sale matters because the benchmark backdrop has turned more expensive for issuers. US 10-year Treasury yields are above 5%, the 2-year is near 4.9%, and high-yield credit spreads have widened, a combination that raises the cost of refinancing and can pressure corporate margins, especially for companies funding acquisitions, technology investment or balance-sheet reshaping.
Sentiment Indicators
For investors, the deal is a reminder that Europe’s financial infrastructure firms are not insulated from the rate cycle. LSE Group, owner of the London Stock Exchange and a major provider of market data and post-trade services, typically enjoys strong access to capital, but a larger short-dated bond issue suggests it is managing funding needs in a market where investors are demanding more yield and shorter duration.
The backdrop also includes a broader pickup in debt issuance across sectors, from corporate and catastrophe bonds to refinancing deals, as issuers rush to secure financing before conditions tighten further. That trend has become more pronounced as Treasury volatility feeds through into global credit pricing and as bond investors remain cautious about crowded issuance calendars.
Shares of key exchange operators have held up better than the broader market, but the funding environment still matters for capital returns, acquisition appetite and the cost of building out data and technology platforms. The next test for LSE will be how the market prices the new notes, and whether demand holds up as higher sovereign yields keep pressure on corporate borrowers.
| Entity | Gains | Losses |
|---|---|---|
| London Stock Exchange Group | ▲Locks in funding | ▼Pays higher coupons |
| Bond investors | ▲Earn higher yield | ▼Face duration risk |
| Competitor exchanges | ▲Benchmark funding access | ▼Relative capital pressure |
| Corporate borrowers | ▲Can still tap market | ▼Higher refinancing costs |