Mexico Banxico survey trims inflation outlook
Mexico’s central bank survey showed economists trimming their inflation outlook and nudging up growth expectations, a combination that points to a still-cooling price backdrop even as the economy holds up better than feared.
The median forecast for headline inflation in August was cut to 0.35% from the previous reading, while analysts raised their 2026 GDP growth estimate to 1.28%, according to the Banxico poll. That mix matters because it suggests Mexico may be moving into a softer inflation, modest-growth phase rather than the kind of stagflationary slowdown that would keep policy restrictive for longer. For investors, that is the sort of shift that can support local assets by improving visibility on rates, corporate earnings and currency stability.
The inflation revision is especially important after a prolonged period in which central banks have been forced to balance disinflation against economic resilience. A slower pace of price gains gives Banxico more room to calibrate policy, though not enough to declare victory. The growth upgrade, meanwhile, implies domestic demand, exports or both are proving sturdier than expected, which is relevant for companies exposed to Mexico’s consumer cycle and industrial supply chains.
Market reaction will hinge on whether the improved growth view comes without a re-acceleration in prices. The peso, which has recently traded around the 17-to-the-dollar area, reflects that tug of war: stronger growth can attract capital, but persistent inflation would keep real rates elevated and limit the central bank’s flexibility. Mexican equities, including exporters and consumer names, tend to benefit when growth expectations improve, while rate-sensitive sectors gain only if easing becomes more credible.
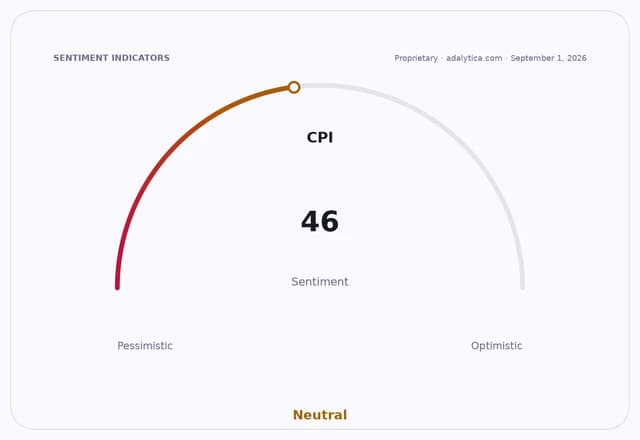
The broader narrative is one of gradual normalization rather than a clean break. Banxico’s survey suggests economists see inflation pressures easing enough to lift real activity, but not so quickly that policymakers can become complacent. For bond investors, the key test is whether upcoming data confirm that disinflation is durable. For equity investors, the message is that Mexico’s macro backdrop may be improving incrementally, even if the path to lower rates remains measured and dependent on the next inflation prints.
| Entity | Gains | Losses |
|---|---|---|
| Mexico growth-linked stocks | ▲Better earnings outlook | ▼None if inflation stays contained |
| Banxico policymakers | ▲More room to ease cautiously | ▼Less room if prices reaccelerate |
| Bond bulls | ▲Lower inflation expectations | ▼Less if growth stays firm enough to keep rates higher |
| Peso bears | ▲Limited upside if disinflation continues | ▼Short positions if macro stability improves |