Mozambique Debt and Bank Lending
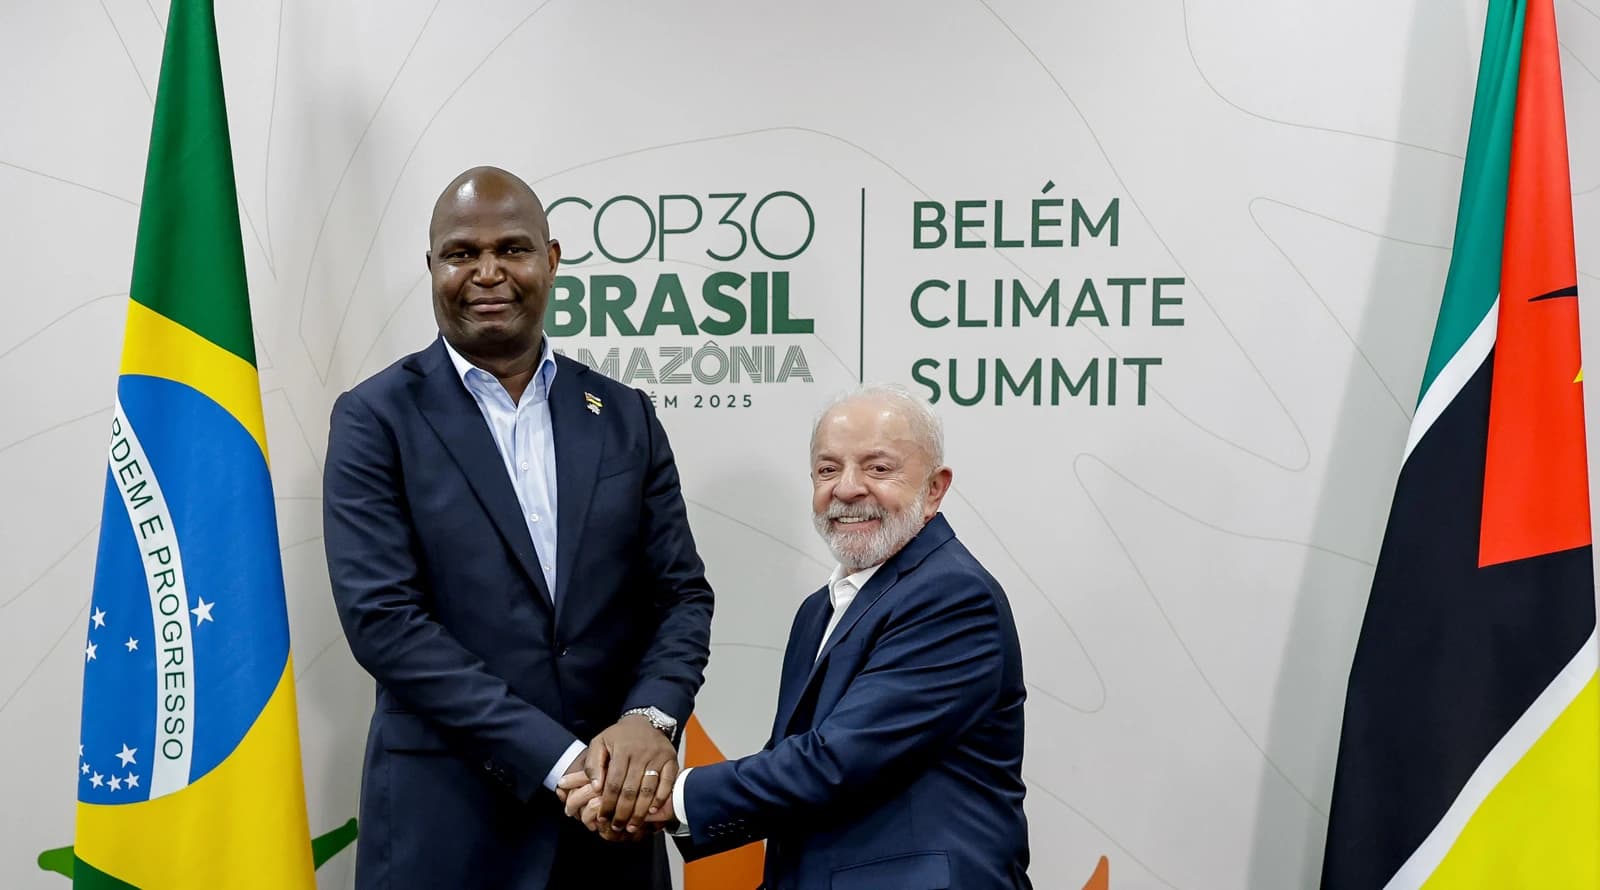
Domestic debt levels cannot be allowed to choke company lending in Mozambique, President Daniel Chapo said, putting the government’s financing strategy at the center of a broader test of whether the country can keep credit flowing while managing a heavy public balance sheet.
The message matters because in a low-income economy like Mozambique, bank lending is still a key transmission channel for investment, trade finance and working capital. If the state’s borrowing needs crowd out private borrowers, the damage would show up quickly in slower corporate spending, weaker imports, delayed project execution and tighter conditions for smaller firms that rely on local banks rather than capital markets.
Chapo’s intervention is also a signal to lenders and foreign investors that the administration wants to separate sovereign debt management from the real economy. That distinction is crucial in markets where government paper can absorb bank liquidity, drive up funding costs and constrain balance-sheet capacity for private credit. The risk is not only higher rates, but a broader loss of confidence that can push banks to hold back even when demand for loans exists.
The policy challenge is familiar across emerging markets: governments need domestic financing to cover budget gaps, yet too much reliance on local borrowing can crowd out private-sector credit and keep real growth subdued. For Mozambique, where investment is needed in infrastructure, mining, energy and logistics, the stakes are high. If financing costs remain elevated, the companies most likely to expand are also the ones most vulnerable to being squeezed out by sovereign demand.
That tension comes as global funding conditions remain uneven. US benchmark Treasury yields are around 4.75%, while the federal funds rate is still at 3.63%, levels that keep international financing relatively expensive and reinforce pressure on frontier borrowers. Credit spreads remain contained by developed-market standards, but they are not loose enough to make weaker sovereigns or local corporates immune to refinancing stress.
For investors, the key question is whether Chapo’s comment reflects a credible shift toward protecting private credit or merely a political reassurance. If the government can lengthen maturities, improve fiscal discipline and avoid overreliance on short-term domestic paper, banks may retain room to finance businesses. If not, domestic debt will continue to compete with the private sector for scarce savings, leaving the banking system exposed and the investment outlook fragile.
The near-term watchpoints are straightforward: how the treasury funds itself, whether banks increase exposure to sovereign paper, and whether loan growth to companies holds up. In Mozambique, as in many emerging markets, the winner is the economy only if the state can borrow without consuming the credit it needs to grow.
| Entity | Gains | Losses |
|---|---|---|
| Mozambican companies | ▲Better access to financing | ▼Crowd-out from sovereign borrowing |
| Government/Treasury | ▲Funding flexibility | ▼Pressure to discipline domestic debt |
| Banks | ▲Larger lending opportunity | ▼Higher sovereign exposure risk |
| Investors | ▲Clearer credit outlook if policy holds | ▼Risk if debt crowds out growth |