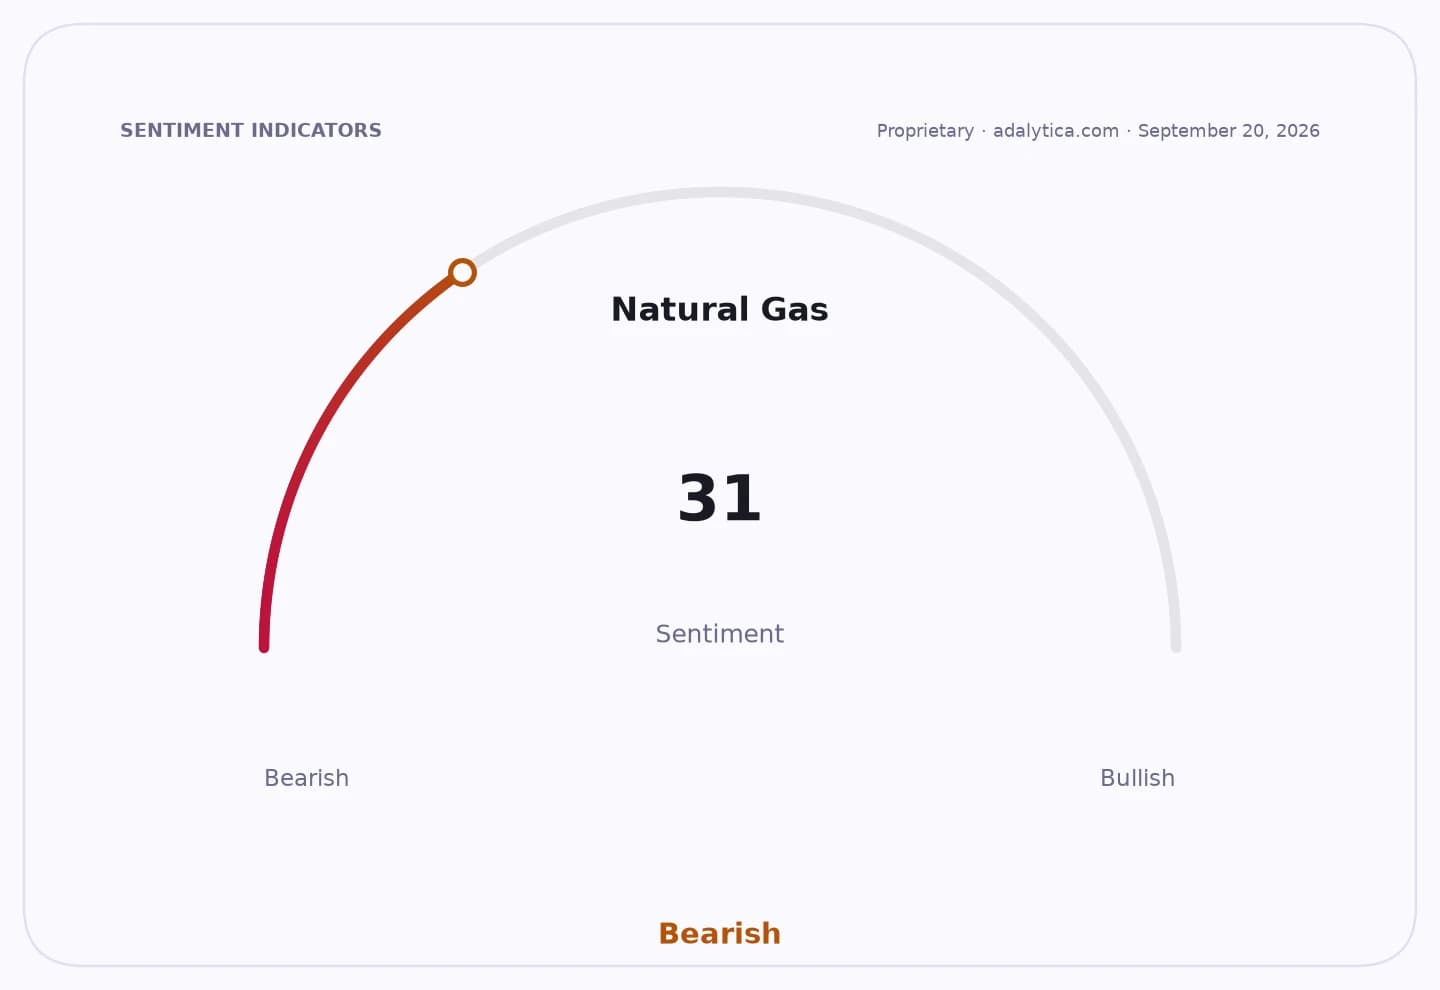
Nigeria’s push to lift Nigeria LNG’s export capacity to 30 million tonnes a year is running into the one constraint that matters most in LNG: there still isn’t enough feedgas to keep the plants full.
Nigeria LNG Train 7 faces feedgas shortfall

That gap is the real story. In a market that has been re-priced by supply disruption, geopolitics and buyers’ hunger for reliable cargoes, Nigeria should be in the sweet spot. Instead, NLNG is operating six liquefaction trains at only 82% to 83% utilization and remains under force majeure, a stark reminder that ambitious capacity expansions mean little without upstream gas.
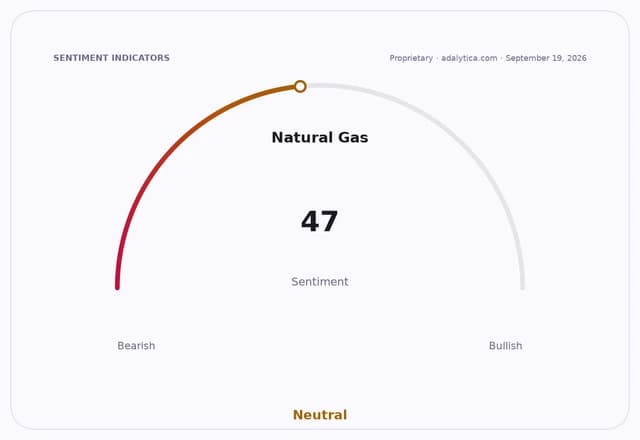
NLNG wants to bring its seventh train online by the end of 2027, a $10 billion project that would take Bonny Island from 22 million tonnes a year to 30 million. But management says it still needs to bridge roughly a 15% gas shortfall before the plant can run the way it should. The company has said it will lift force majeure only when utilization reaches 90%, underscoring how operational bottlenecks are now delaying what should be a straightforward growth story.
For investors, that makes this a classic LNG infrastructure trade with a second-order twist. The market usually rewards new liquefaction capacity, but the higher-conviction opportunity is in the upstream and midstream assets that secure molecules first. In other words, the winners are not just the terminal owners but the producers, shippers and contractors that can guarantee reliable supply into a tighter global system.
The timing still matters. The LNG market has been jolted by disruptions around the Strait of Hormuz and broader Middle East tension, pushing buyers to favor flexible spot cargoes and diversified supply. That should be a tailwind for any exporter that can deliver consistently. Nigeria could benefit from that reset — if it can solve its own domestic gas constraint.
NLNG, majority-owned by state oil company NNPC alongside Shell, TotalEnergies and Eni, is already prioritizing the contracts covered by force majeure while trying to maximize current output. That is rational near term, but it also means the upside from Train 7 will be gated by upstream investment, government coordination and feedgas reliability, not just engineering.
That is why the real investment lesson is bigger than Nigeria. The LNG cycle is shifting from a pure capacity story to a resilience story. The market underestimates how valuable dependable supply has become, and that should keep premium valuations intact for LNG exporters with strong upstream integration, as well as for the equipment and services names tied to gas gathering, processing and liquefaction buildout.
If Nigeria can close the gas gap, it has a credible path to becoming a more important supplier into a world that increasingly pays up for certainty. Until then, the stock-like prize in LNG remains with the parts of the chain that turn resource abundance into delivered volumes.
| Entity | Gains | Losses |
|---|---|---|
| NLNG / Nigeria | ▲Higher long-term export capacity | ▼Current underutilization and force majeure |
| Shell, TotalEnergies, Eni, NNPC | ▲Optionality on Train 7 growth | ▼Capital tied up by feedgas bottlenecks |
| LNG buyers seeking secure supply | ▲More diversified future supply source | ▼Less near-term Nigerian cargo availability |
| Upstream gas and midstream contractors | ▲More demand for gas capture and transport | ▼Projects without reliable feedgas backing |