Nintendo Rises as BOJ Rate-Hike Bets Hit Japan Stocks
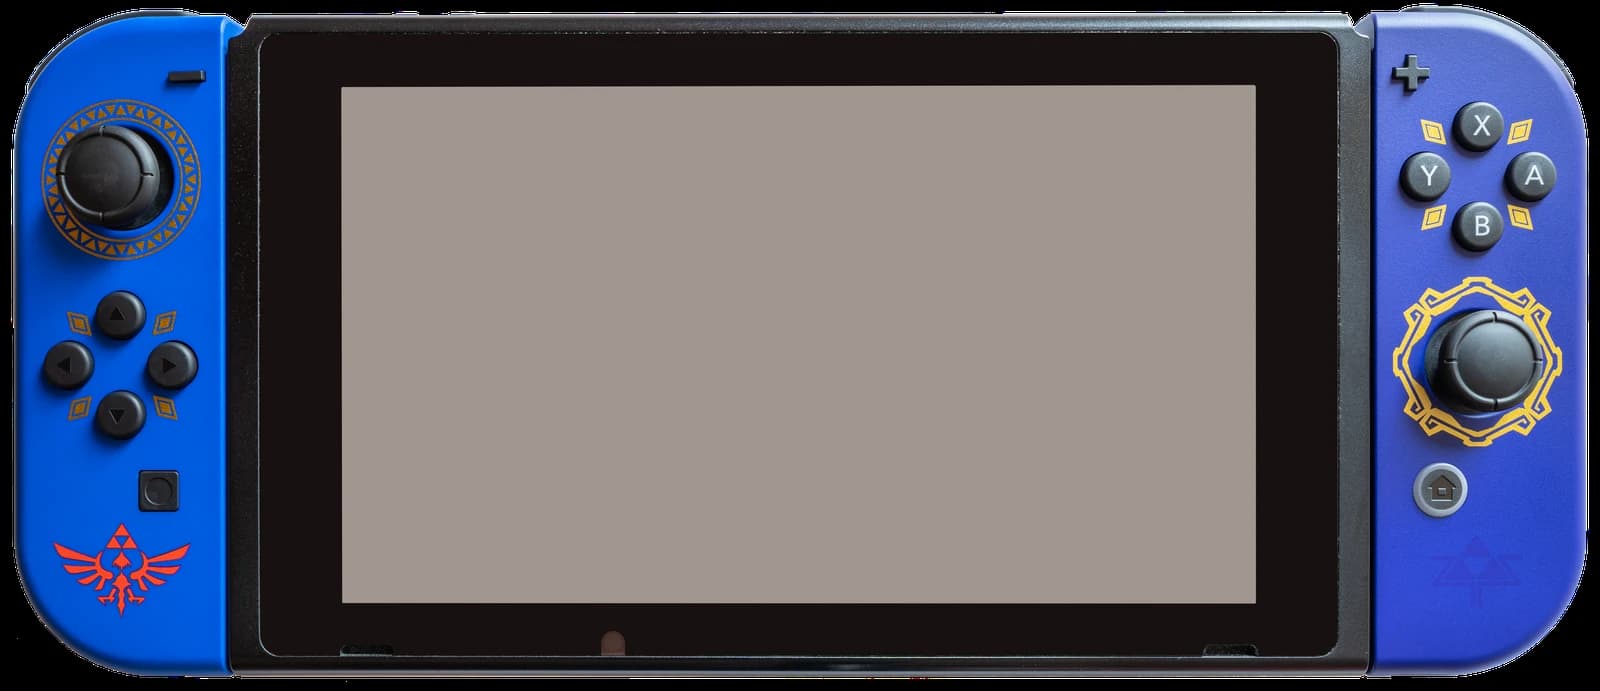
Nintendo’s shares bounced on Friday as investors looked past a brief pullback and focused instead on the market’s biggest question: whether the company can meet the very high expectations surrounding its next “The Legend of Zelda” release. The stock’s recovery comes even as broader Japan-linked tech names swung on a very different force — speculation that the Bank of Japan will accelerate rate hikes, pushing the yen to a seven-month high and putting pressure on exporters, suppliers and other equity winners of cheap money.
That macro shift matters because it is starting to change which Japanese stocks deserve a premium. A faster-tightening BOJ would support the yen, raise funding costs and make investors more selective about businesses that depend on export demand, balance-sheet leverage or speculative inventory cycles. It also helps explain why some hardware and component names are struggling to find short-term catalysts even when end-demand remains intact.
Taiyo Yuden was hit hard, falling as much as 6.3% after SMBC Nikko said it lacked short-term recovery material. The move highlights how quickly the market is punishing companies without a near-term earnings spark when rates are rising and the currency is strengthening. In that environment, investors are no longer willing to pay up for far-off demand stories alone.
The tension in Japan’s market is a useful clue for where opportunity may still exist. Nintendo stands out because it is not just a cyclical supplier of gadgets; it is a global intellectual-property platform with pricing power, a loyal installed base and the ability to turn a major game launch into software, hardware and merchandising demand. If “The Legend of Zelda” lives up to the market’s expectations, the earnings leverage can still be meaningful even in a tougher domestic macro setting.
That is why the stock’s rebound matters beyond one session. Investors are trying to separate businesses with durable content franchises from those exposed to a more expensive capital regime and a potentially stronger yen. The recent weakness in the 5-year bond auction, along with the yen’s surge, suggests the market is already pricing in a less forgiving backdrop for Japanese equities tied to cheap liquidity and export-led momentum.
The trade here is becoming clearer: in a BOJ tightening cycle, the best-positioned names are the ones with secular demand drivers, global pricing power and limited reliance on a low-rate domestic cycle. Nintendo fits that mold far better than commodity-sensitive or inventory-dependent suppliers. For investors, the actionable takeaway is to lean into Japanese companies with brand moats and recurring demand while treating rate-sensitive suppliers as tactical, not core, holdings.
| Entity | Gains | Losses |
|---|---|---|
| Nintendo | ▲Franchise-driven demand | ▼Short-term skepticism |
| Taiyo Yuden | ▲— | ▼No near-term recovery catalyst |
| Yen | ▲Higher policy expectations | ▼Exporter margins |
| BOJ rate-hike bets | ▲Policy credibility | ▼Risk assets tied to cheap money |