NNN REIT Dividend Raised to 5.6% Yield
NNN REIT’s 37th straight annual dividend increase is reinforcing why the net-lease landlord remains one of the REIT sector’s most dependable income stocks, even as the broader commercial property trade has come under pressure.
The appeal is simple for investors: NNN now yields 5.6%, well above the S&P 500’s roughly 1% and the REIT sector’s 4% average, while still leaving room for dividend growth. The company raised its payout by 3.3% in July to 62 cents a share quarterly, or $2.48 annualized, and expects adjusted funds from operations of $3.55 to $3.59 a share this year, implying a payout ratio near 70%.
That coverage matters because REIT dividends are only as durable as cash flow. NNN’s nearly 3,800 net-lease retail properties, weighted-average remaining lease term of more than 10 years and investment-grade balance sheet give it visibility on rental income that many property owners lack. Management says it can self-fund about $550 million of annual acquisitions through retained cash flow, asset sales and debt while still preserving its financial profile.
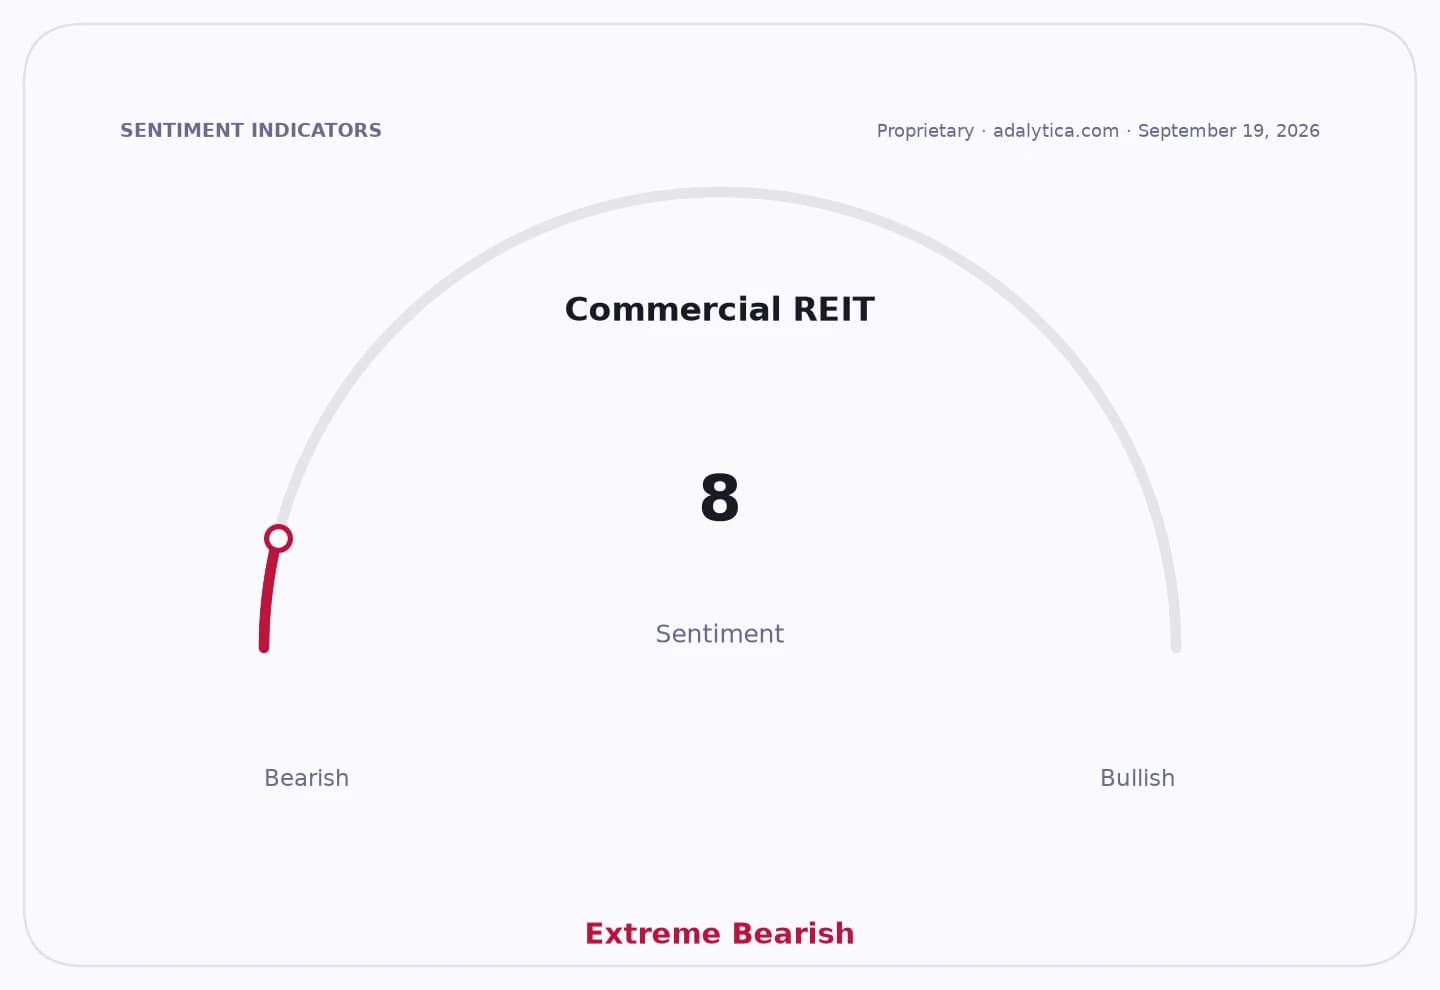
For income investors, the streak is the main attraction, but the market backdrop helps explain why the stock is being treated as a defensive yield play. REIT sentiment has deteriorated sharply, with Adalytica’s commercial REIT sentiment reading at 8, or “Extreme Fear,” even as Treasury bonds have stabilized and the S&P 500 shows more neutral positioning. That split has left high-quality income names looking more attractive to long-term buyers seeking steady cash returns over cyclical growth.
NNN’s shares have also been under pressure recently, with the stock trading around $41.55, below both its 50-day moving average of $46.08 and its 200-day moving average of $43.28. The drop has pushed the yield higher, which can draw fresh income-focused money even as technical momentum remains weak, with RSI readings near 4 signaling deeply oversold conditions.
The bigger story for investors is not just the dividend itself but the durability of the model behind it. With a conservative payout ratio, long lease terms and a large addressable market in U.S. freestanding retail property, NNN has room to keep compounding income even if REIT valuations stay volatile. The next catalyst is whether the company can keep converting that cash flow into another year of dividend growth as financing costs and retail property demand evolve.
| Entity | Gains | Losses |
|---|---|---|
| NNN REIT shareholders | ▲Higher income yield | ▼Near-term share price pressure |
| Income-focused investors | ▲Stable 5.6% payout | ▼Less upside than growth stocks |
| REIT bulls | ▲Durable cash-flow story | ▼Weak sector sentiment |
| Short-term traders | ▲Oversold rebound setup | ▼Trend remains negative |