Oracle, ECB and U.S. CPI in focus this week
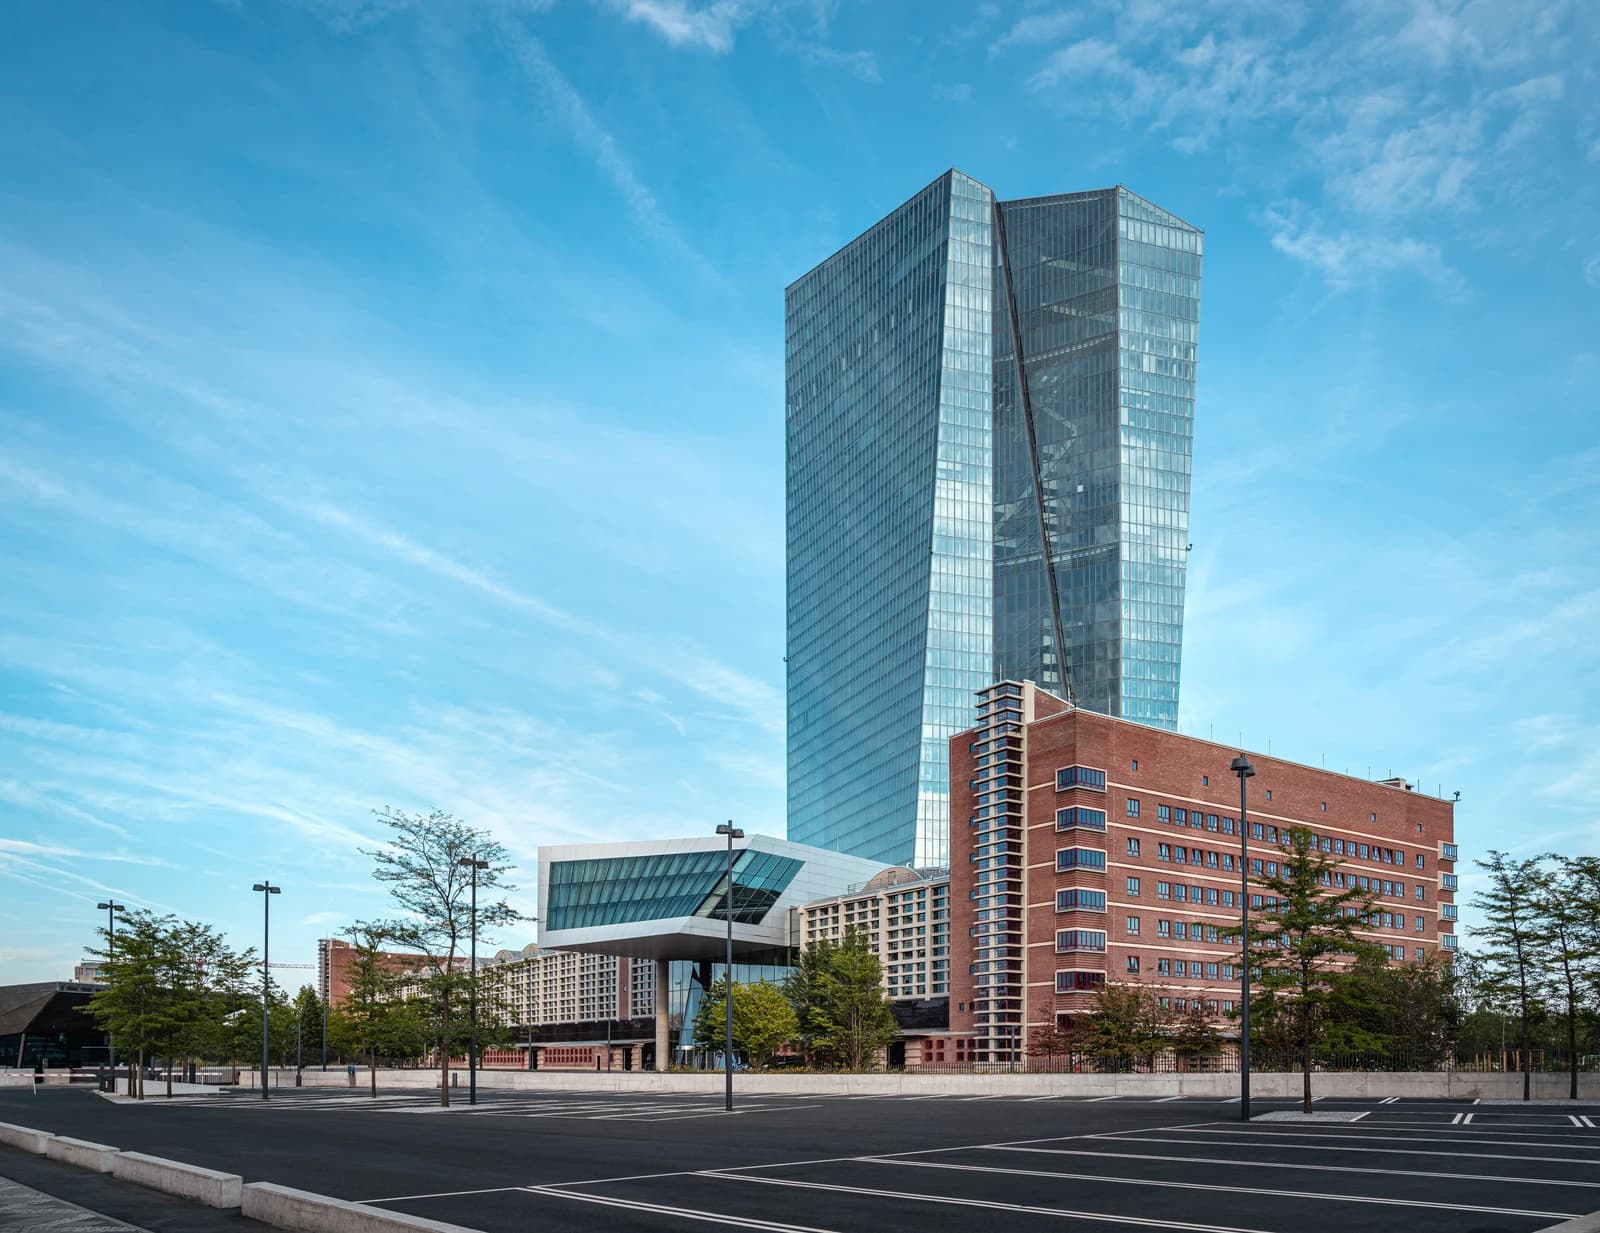
The euro zone and U.S. face a pivotal week for rates and risk assets, with the European Central Bank expected to tighten policy, Oracle due to report on AI infrastructure demand and the next U.S. inflation reading likely to decide whether the Federal Reserve stays on hold or moves to raise rates next week.
Why it matters economically: the ECB is under pressure from a fresh inflation flare-up, while U.S. policymakers are watching whether August CPI confirms that disinflation is still intact. Euro area inflation has accelerated to 3.3%, driven by higher energy costs and geopolitical tensions in the Middle East, and traders are now fully pricing a rate increase, with markets expecting a total of three hikes by mid-2027.
In the U.S., Friday’s CPI report is the key input for the FOMC ahead of next week’s meeting. Fed Governor Christopher Waller recently said the disinflation process is continuing and that core inflation looks better than headline measures suggest, adding that a CPI print without a negative surprise would likely support leaving rates unchanged.
That backdrop has already shifted market pricing. After August nonfarm payrolls rose 162,000, above expectations, the implied probability of a September rate hike climbed to 60% from about 50% before the release. The 10-year Treasury yield has also pushed up to around 4.8%, keeping financial conditions tight even before the next inflation print.
For investors, the ECB decision and U.S. CPI could reprice everything from bond yields to the dollar and equity leadership. A hotter U.S. inflation number would strengthen bets that the Fed keeps tightening, while a softer reading could ease pressure on duration-sensitive assets and risk appetite. Adalytica’s S&P 500 trade signals currently show “Extreme Fear,” while its long-term inflation expectations gauge remains neutral, underscoring how brittle positioning is heading into the data.
Oracle’s results on Thursday after the close add a corporate catalyst to an already crowded macro week. Investors will focus on cloud revenue growth, backlog and management’s outlook, with the bar high across the AI infrastructure trade. Oracle shares have rebounded sharply in recent sessions, and the stock’s 50-day moving average has turned up, but the key test is whether the company can convert AI demand into bookings and revenue momentum without disappointing guidance.
The broader market setup remains finely balanced. The S&P 500 has held near record territory, but the move has come with heavy dependence on a few mega-cap names and rising sensitivity to rate expectations. Treasury trading and the dollar are likely to react first to CPI, while Oracle’s report will help determine whether the AI rally has another leg or starts to look crowded.
The next catalyst is Friday’s U.S. inflation release, followed by the Fed meeting next week and guidance from the ECB on how far it plans to go with tightening.
| Entity | Gains | Losses |
|---|---|---|
| ECB hawks | ▲Tighter policy credibility | ▼Growth-sensitive borrowers |
| U.S. bond bears | ▲Higher yield reset | ▼Treasury bulls |
| Oracle bulls | ▲Strong AI backlog and cloud growth | ▼Investors if guidance disappoints |
| Equity longs | ▲Softer CPI / lower rates | ▼Volatility if inflation runs hot |