Poland bond yields widen vs WIBOR
Poland’s bond market has hit an unprecedented gap between government borrowing costs and WIBOR, a mismatch that is already making it harder for companies to sell debt and threatening to reshape pricing across the corporate bond market.
The difference between the yield on Poland’s 10-year government bonds and the six-month WIBOR rose to 2.66 percentage points on Tuesday, the widest on record. Even after the benchmark bond yield eased to 6.15%, the spread was still 2.3 percentage points, well above the long-term median of 0.8 percentage point.
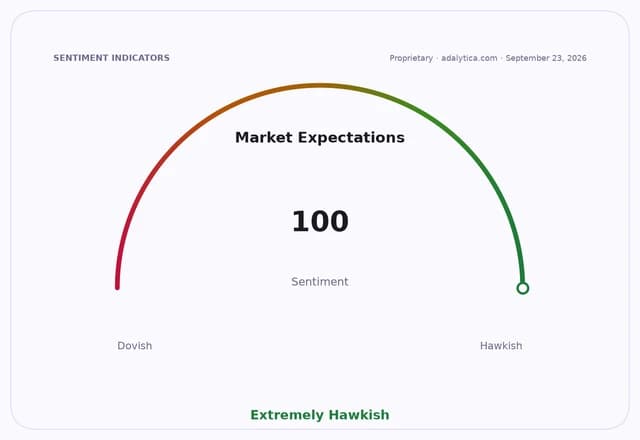
That gap matters because much of Poland’s corporate debt is priced off WIBOR. When Treasury bonds offer nearly the same nominal return as floating-rate corporate notes paying WIBOR plus a margin, investors have less incentive to take credit risk for a small extra spread. Emil Szweda, chief analyst at Michael/Ström Dom Maklerski, said that makes it harder to justify buying bonds such as those offering WIBOR plus 2.5 percentage points.
The pressure is already showing up in issuance. Investors this week bought 10-year subordinated notes from VeloBank at that margin, while Bank Pocztowy earlier sold four-year senior bonds at a 2.2-point spread. But those deals stand out as exceptions in a market where fewer medium and large corporate offerings are getting done.
Since the selloff in government bonds began, only a handful of larger corporate issues have reached the market, and just one — AB SA’s July deal — was placed with traditional institutional investors before sovereign yields surged. Other offerings have been aimed at retail buyers, structured through bank groups, or sold bilaterally to private debt funds at much higher rates, including around 14.5%, which reflects a very different part of the market.
For investors, the message is twofold. Corporate issuers may delay borrowing, reducing supply in a market that already lacks depth, while investors in bond funds may still face inflows without enough new paper to buy. At the same time, banks remain active competitors for lending to small and mid-sized companies, giving issuers an alternative to the bond market for now.
The longer-term risk is that corporate coupons have to rise to keep pace with sovereign yields. Szweda said one way that adjustment could happen is through higher WIBOR, a scenario that has become more plausible as the Fed, following the ECB, has raised rates, Poland’s core inflation has climbed to 3.3%, and oil prices have stayed well above $100 a barrel despite recent declines.
| Entity | Gains | Losses |
|---|---|---|
| Polish government bond buyers | ▲Higher sovereign yields | ▼Corporate bond relative value |
| Corporate issuers | ▲Delay financing needs | ▼Higher future borrowing costs |
| Bank lenders | ▲More loan demand | ▼Bond market competition |
| Bond fund managers | ▲Continued inflows | ▼Limited supply of new issues |