Purple Style Labs made a weak stock market debut, listing below its IPO price as investors focused less on revenue growth and more on widening losses, rising debt and execution risk in India’s premium fashion business.
Purple Style Labs Shares Fall Below IPO Price
The luxury fashion and lifestyle company’s shares opened at 539 rupees on the BSE and 535 rupees on the NSE, both below the 575-rupee issue price by about 6% to 7%. Selling pressure deepened after listing, with the stock slipping as much as 10.3% below the offer price in early trade. For an IPO that raised 6.8 billion rupees, the debut shows the market is not yet willing to pay up for growth alone.
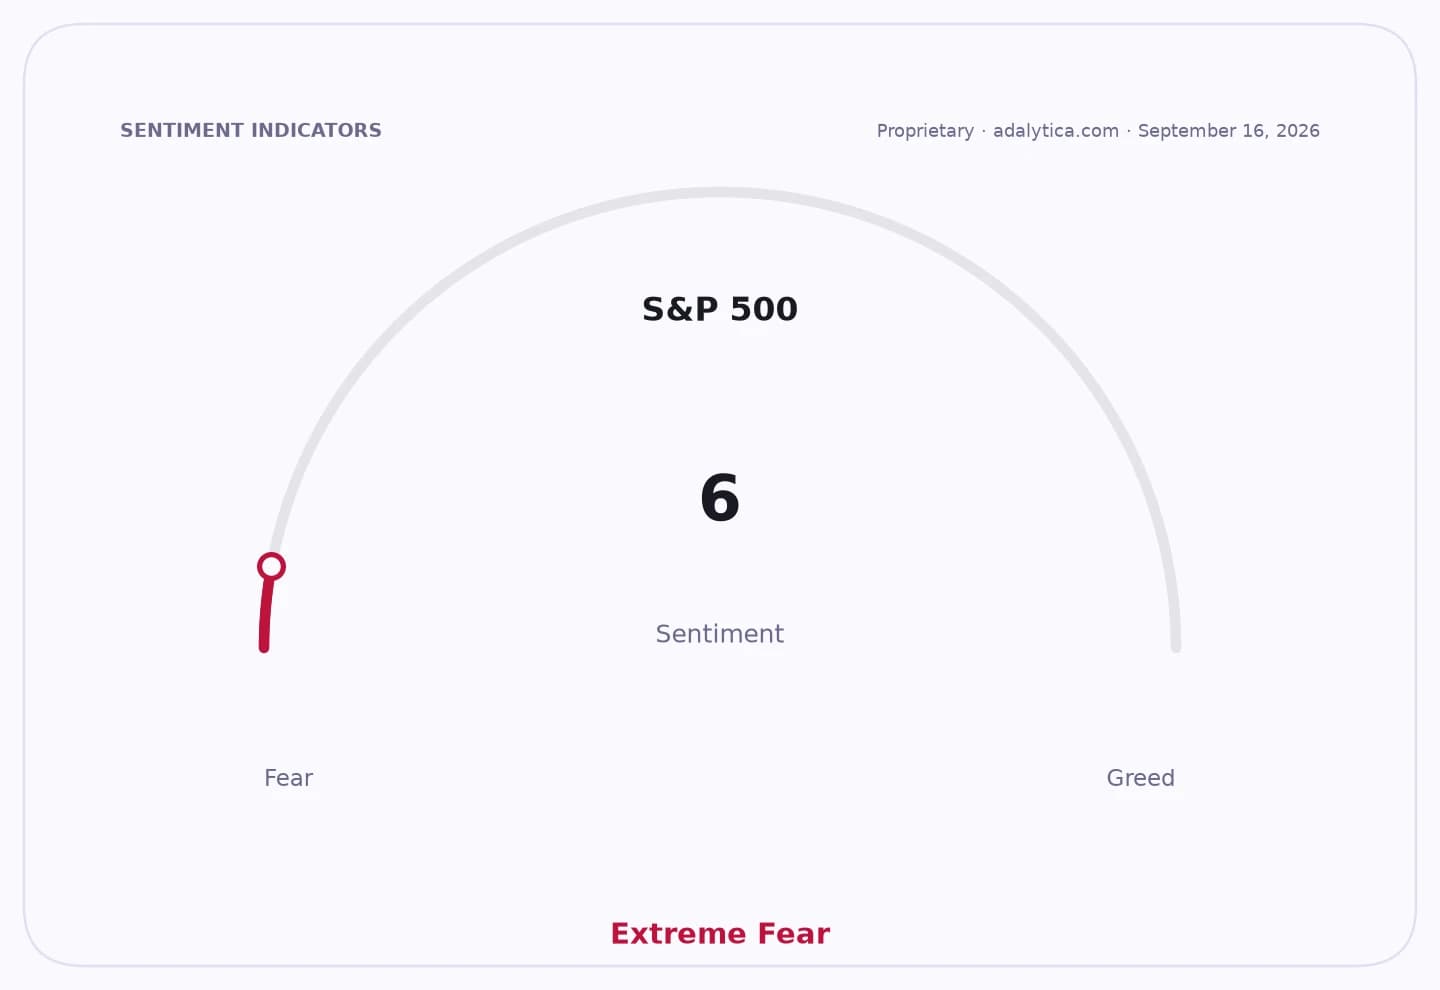
Sentiment IndicatorsⓘProprietary · adalytica.com · September 7, 2026
This is a snapshot — live sentiment, awareness and momentum for 130+ markets update continuously in the dashboard.Open AlphaPulse
That matters because Purple Style Labs is entering public markets at a time when investors are scrutinizing consumer companies for cash burn, leverage and the durability of margins. According to its prospectus, the company’s consolidated loss widened to 2.854 billion rupees in FY2025-26 from 1.884 billion rupees a year earlier and 477.1 million rupees in FY2023-24, while total borrowings jumped to 3.714 billion rupees from 1.128 billion rupees a year earlier. Revenue rose to 5.671 billion rupees, but EBITDA fell to 303.7 million rupees from 419.9 million rupees, underscoring that sales growth has not translated into stronger operating leverage.
The numbers help explain why the deal was met cautiously despite the company’s premium positioning. Purple Style Labs, known for Pernia’s Pop-Up Shop, derives 77.7% of gross merchandise value from women’s wear, leaving it exposed to shifts in fashion tastes and demand softness in a narrow customer base. In a discretionary sector, that concentration can cut both ways: it offers brand clarity if demand holds, but it also amplifies downside if product cycles misfire.
Investors also face governance and commercial uncertainties. The company said it received a notice seeking termination of a licence agreement linked to Pernia Kuriaeshi and a related vendor, raising questions over some brand rights. On top of that, many designer-branded products are priced by the designers themselves and several agreements are non-exclusive, limiting Purple Style Labs’ ability to control pricing and potentially allowing brands to sell through rival channels or direct to consumers.
The bear case is straightforward: a higher-debt, loss-making retailer with thin profitability and brand dependency is being asked to justify expansion plans before proving it can defend margins. The bull case rests on the company’s growth runway through new stores, international expansion and deeper partnerships with premium labels, but that strategy will only gain traction if management can show tighter capital discipline and steadier earnings.
For investors, the debut is a reminder that the market is rewarding quality and visible cash generation over narrative. Unless Purple Style Labs can demonstrate that revenue growth can outpace costs, reduce leverage and stabilize its brand economics, the stock may continue to trade with a discount to the IPO price.
| Entity | Gains | Losses |
|---|---|---|
| IPO investors who stayed cautious | ▲Avoid paying peak valuation | ▼Missed near-term upside |
| New buyers at lower levels | ▲Get a cheaper entry point | ▼Face execution and leverage risk |
| Purple Style Labs management | ▲Public listing completed | ▼Weak debut hurts market confidence |
| Rival fashion platforms | ▲Benefit from investor skepticism | ▼Face less direct impact |