SHFE Tin Falls Below 410,000 Yuan on Hot US PPI
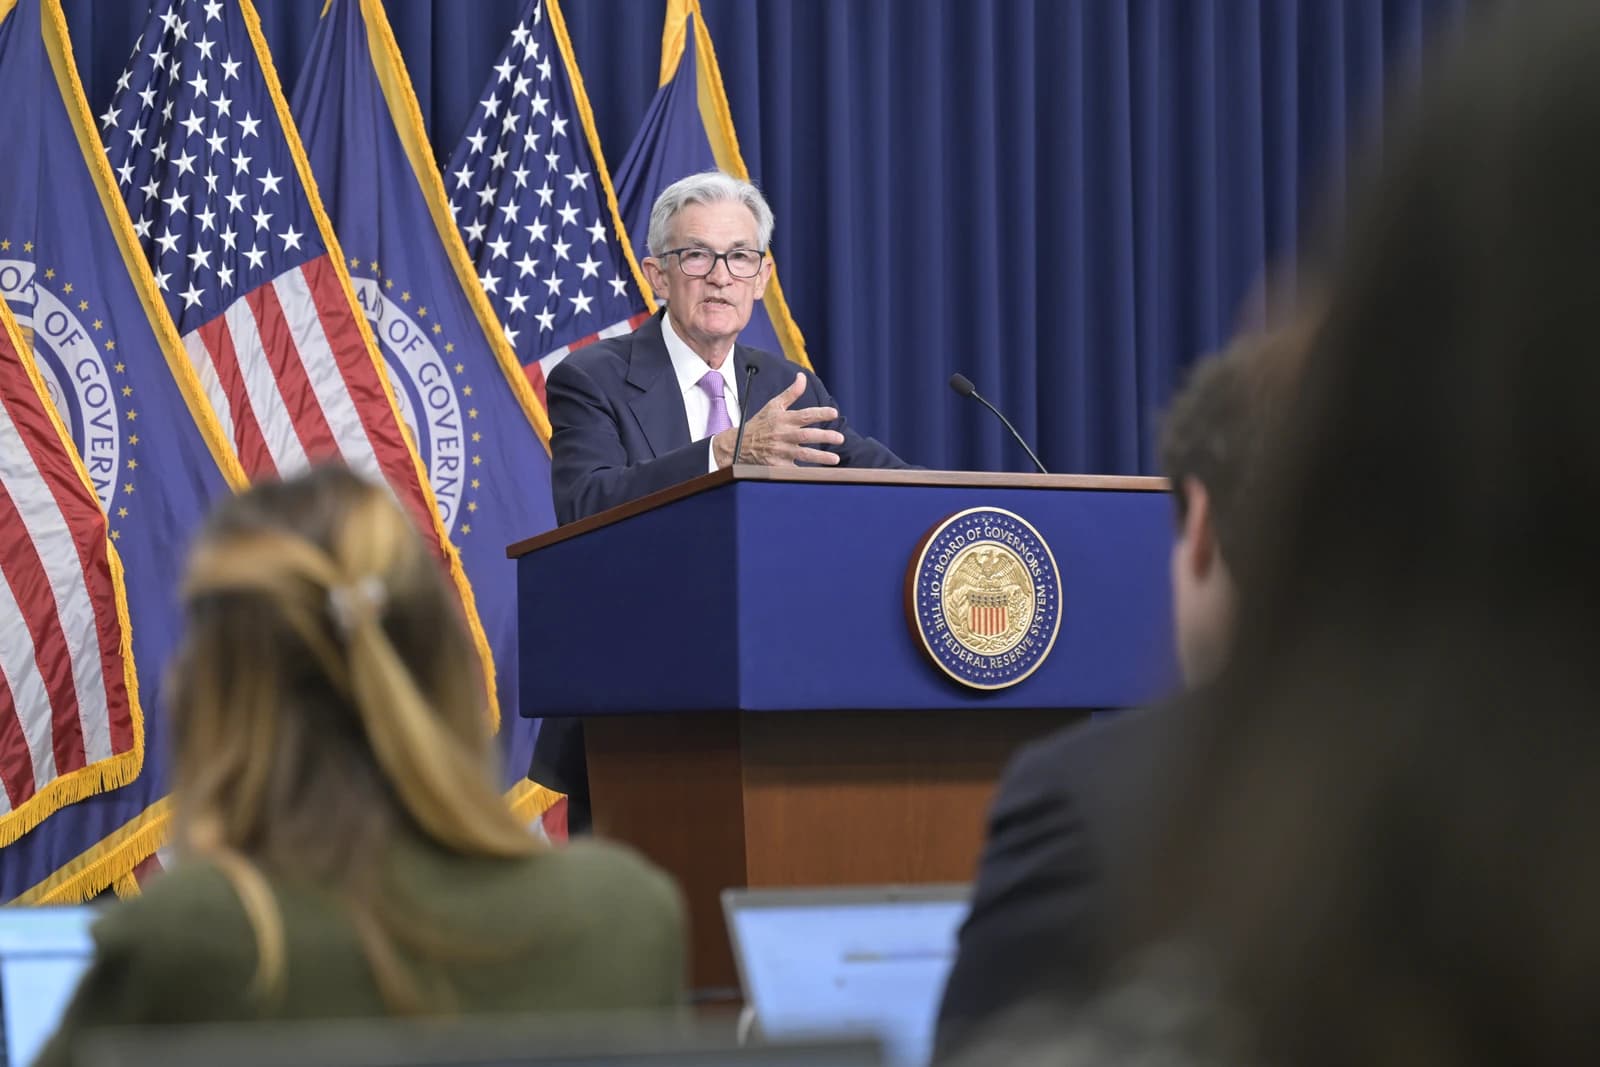
US producer prices rose more than expected in August, pushing traders to price a greater chance of another Federal Reserve hike and dragging the most-traded SHFE tin contract below 410,000 yuan a tonne as tighter dollar liquidity weighed on industrial metals.
The move matters because tin is one of the more rate-sensitive base metals: it is heavily exposed to the dollar, global financing conditions and expectations for end-user demand in electronics and soldering. A hotter-than-expected US inflation print tends to strengthen the dollar, lift Treasury yields and tighten financial conditions, all of which typically pressure metals priced in dollars and weigh on speculative positioning across Shanghai and London.
In Shanghai, the most-traded tin contract fell 3.25% to 409,550 yuan a tonne after touching an intraday low of 408,030 yuan, breaking a psychologically important floor that had helped anchor the market. Spot tin averaged 410,600 yuan a tonne, down 15,100 yuan from the previous session, while LME tin slipped 0.47% to $53,860 a tonne. The simultaneous decline in both venues points to a macro-driven move rather than a purely domestic China story.
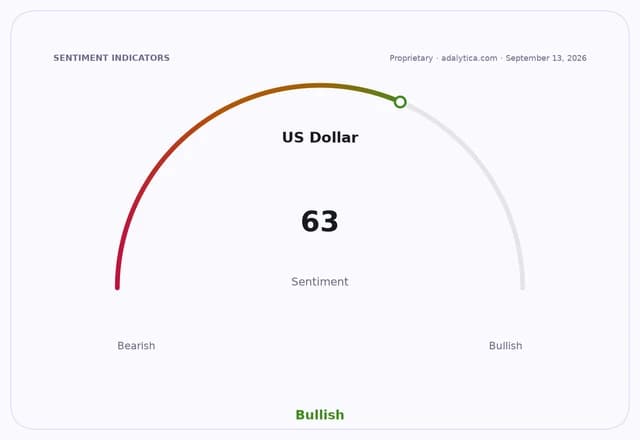
The US inflation surprise came just ahead of the August CPI release and the Federal Reserve’s September 15-16 meeting, leaving traders focused on whether policy will stay restrictive for longer. The prospect of a further rate hike above already elevated levels in US money markets has also reinforced a stronger dollar backdrop; Adalytica’s US dollar trade signals show sentiment remaining neutral but stable, while risk appetite in broader equity markets has deteriorated sharply.
For tin, the immediate consequence is a test of whether lower prices can trigger enough physical buying to cushion the market. Spot activity improved after the selloff, with downstream users and traders stepping in for low-price restocking, but transactions remained largely tied to rigid demand rather than a broad pickup in consumption. Seasonal peak demand has so far looked uneven, suggesting the market still lacks the end-use momentum needed for a durable rebound.
That leaves tin caught between macro pressure and selective support from physical restocking. If the upcoming CPI reading also runs hot, the case for tighter US policy and a firmer dollar could deepen the downside. If inflation cools, the contract may recover back toward the 415,000 yuan area that now acts as resistance. For investors, the key question is whether this break below 410,000 yuan marks a short-lived washout or the start of a broader repricing of industrial metals into a more restrictive US rates outlook.
| Entity | Gains | Losses |
|---|---|---|
| US dollar | ▲Benefits from tighter Fed expectations | ▼Faces weaker rate-cut hopes |
| SHFE tin buyers | ▲Get lower entry prices | ▼Lose mark-to-market value |
| Tin sellers / longs | ▲Can restock into weakness | ▼Suffer price declines |
| Industrial metals broadly | ▲Some physical demand may emerge | ▼Macro pressure from higher yields |