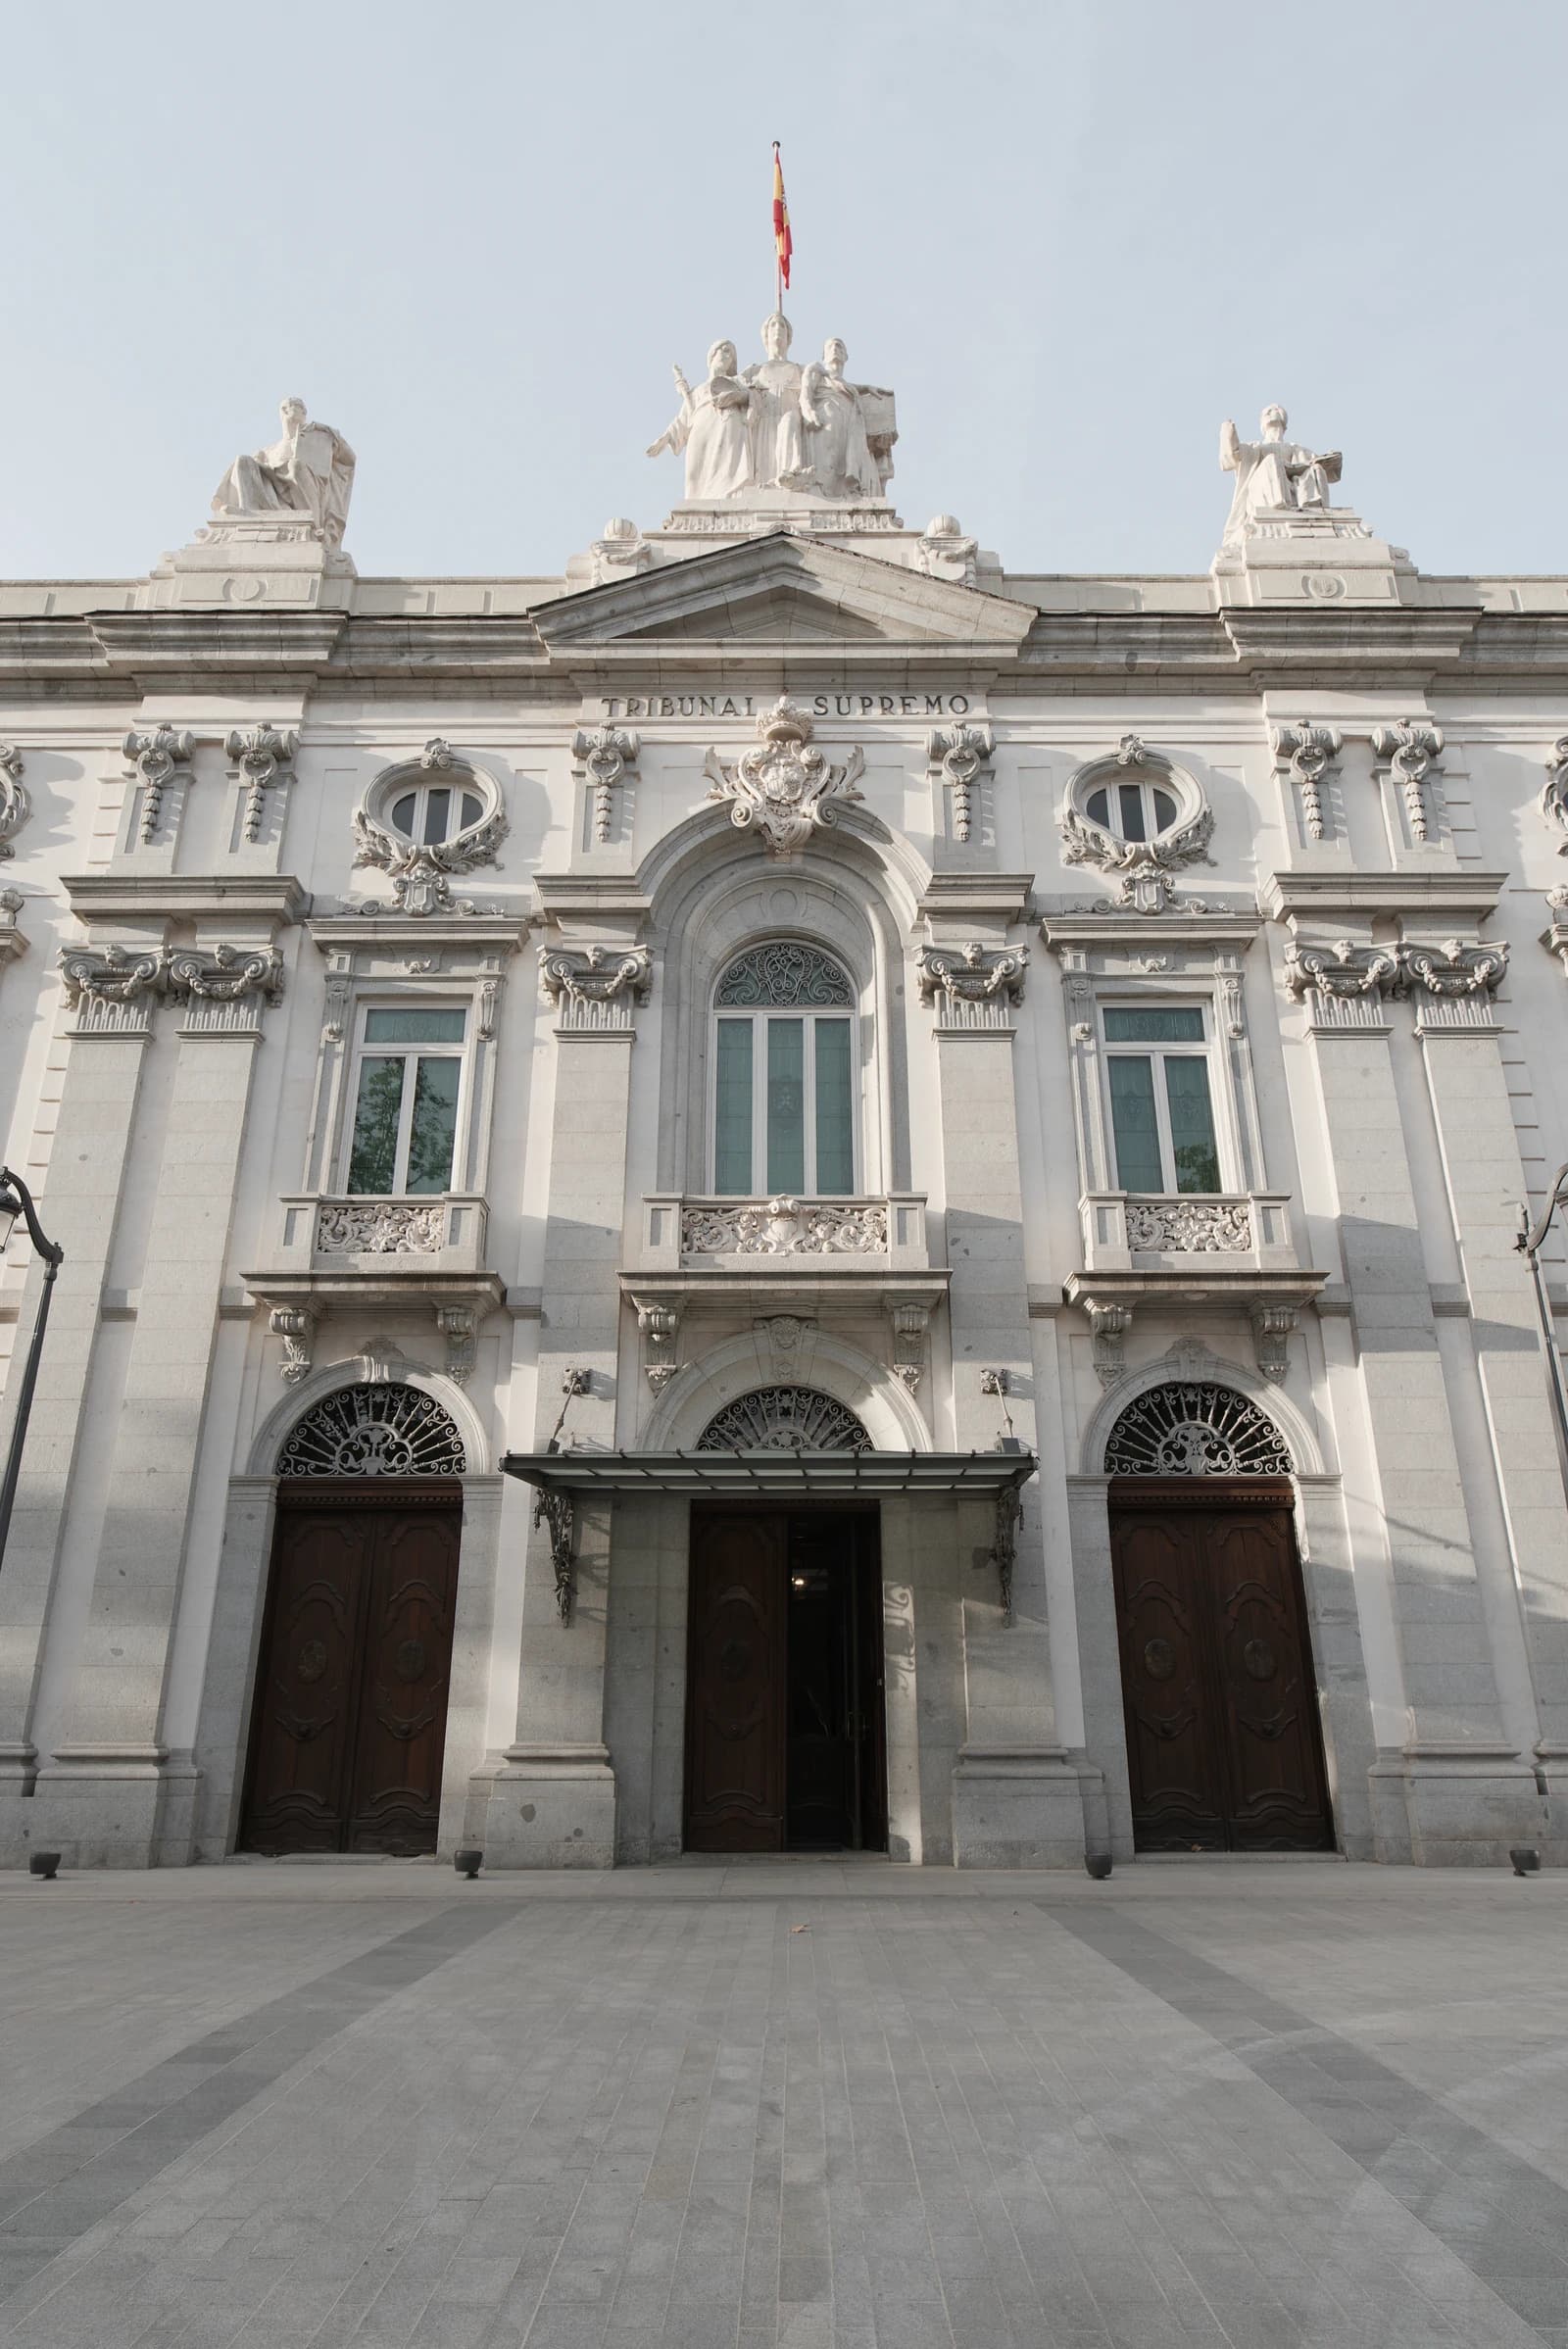
Spain’s Supreme Court has ruled that heirs must pay personal income tax on gains generated by an estate even before they formally receive the inheritance, tightening the tax treatment of “yacente” estates and closing off what the court saw as a potential shelter for untaxed gains.
Spain Supreme Court Taxes Gains in Undivided Estates
The decision matters because it confirms that investment income and capital gains earned by an estate during the waiting period remain taxable, even when the testator has delayed access to the assets for years. For families, that means a tax bill can arrive before they can actually control the money. For the tax authority, it removes a legal grey area that could otherwise leave gains in what one tax adviser called a “limbo” for fiscal purposes.
The case involved two brothers named as equal heirs by a relative, but barred by the will from taking possession for six years after the testator’s death in 2013. During that period, the inherited assets generated a €1.41 million gain. Before the heirs could accept the estate, the tax agency opened proceedings tied to their 2014 income tax return. One heir later sought a refund, arguing he was not yet legally an heir and that the gain had already been taxed under Spain’s inheritance tax.
The court rejected that argument and upheld a €23,403.79 penalty, saying the income tax and inheritance tax cover different events. Inheritance tax is due when ownership of assets passes to the beneficiary. Personal income tax, by contrast, applies to the returns those assets produce while the estate remains undivided. Because a pending estate has no legal personality of its own, the court said, those returns are allocated to the heirs.
Economically, the ruling reinforces a broader principle in Spain’s tax system: ownership and economic benefit are treated separately. That may increase tax certainty for the government and reduce the risk of unpaid gains accumulating in estates that sit unresolved for years. But it also raises the compliance burden on heirs, particularly in cases involving complex portfolios, family businesses or delayed succession plans where the beneficiaries cannot immediately liquidate assets to meet the tax bill.
For investors and wealthy families, the judgment is a reminder that succession planning is not only about inheritance tax rates but also about interim taxation on portfolio income, dividends and capital gains. The ruling may push advisers to review wills that postpone asset transfers, especially where asset appreciation can be material over several years. It may also encourage more conservative estate structures to avoid unexpected liabilities before legal title is transferred.
The broader policy relevance is hard to miss. As governments across Europe continue debating how to tax wealth and inheritance more aggressively, the Spanish court has drawn a line that favors fiscal collection over the timing arguments of heirs. The practical effect is that gains earned during an undivided estate will not escape the tax net simply because the beneficiary has not yet taken possession.
For now, the decision gives Spain’s tax authority a firmer legal footing and increases the likelihood that heirs will face income tax obligations earlier than many expect. The next questions are whether similar disputes emerge over other delayed inheritances and whether lawmakers see room to clarify or adjust the rules for estates that remain dormant for long periods.
| Entity | Gains | Losses |
|---|---|---|
| Spain tax authority | ▲Clearer tax collection | ▼Fewer untaxed gains |
| Heirs | ▲Legal certainty | ▼Earlier tax bills |
| Estate planners | ▲Rule clarity | ▼More complex succession planning |
| Wealthy families | ▲None | ▼Higher compliance burden |