Swiss National Bank Says Inflation Stayed Within Range
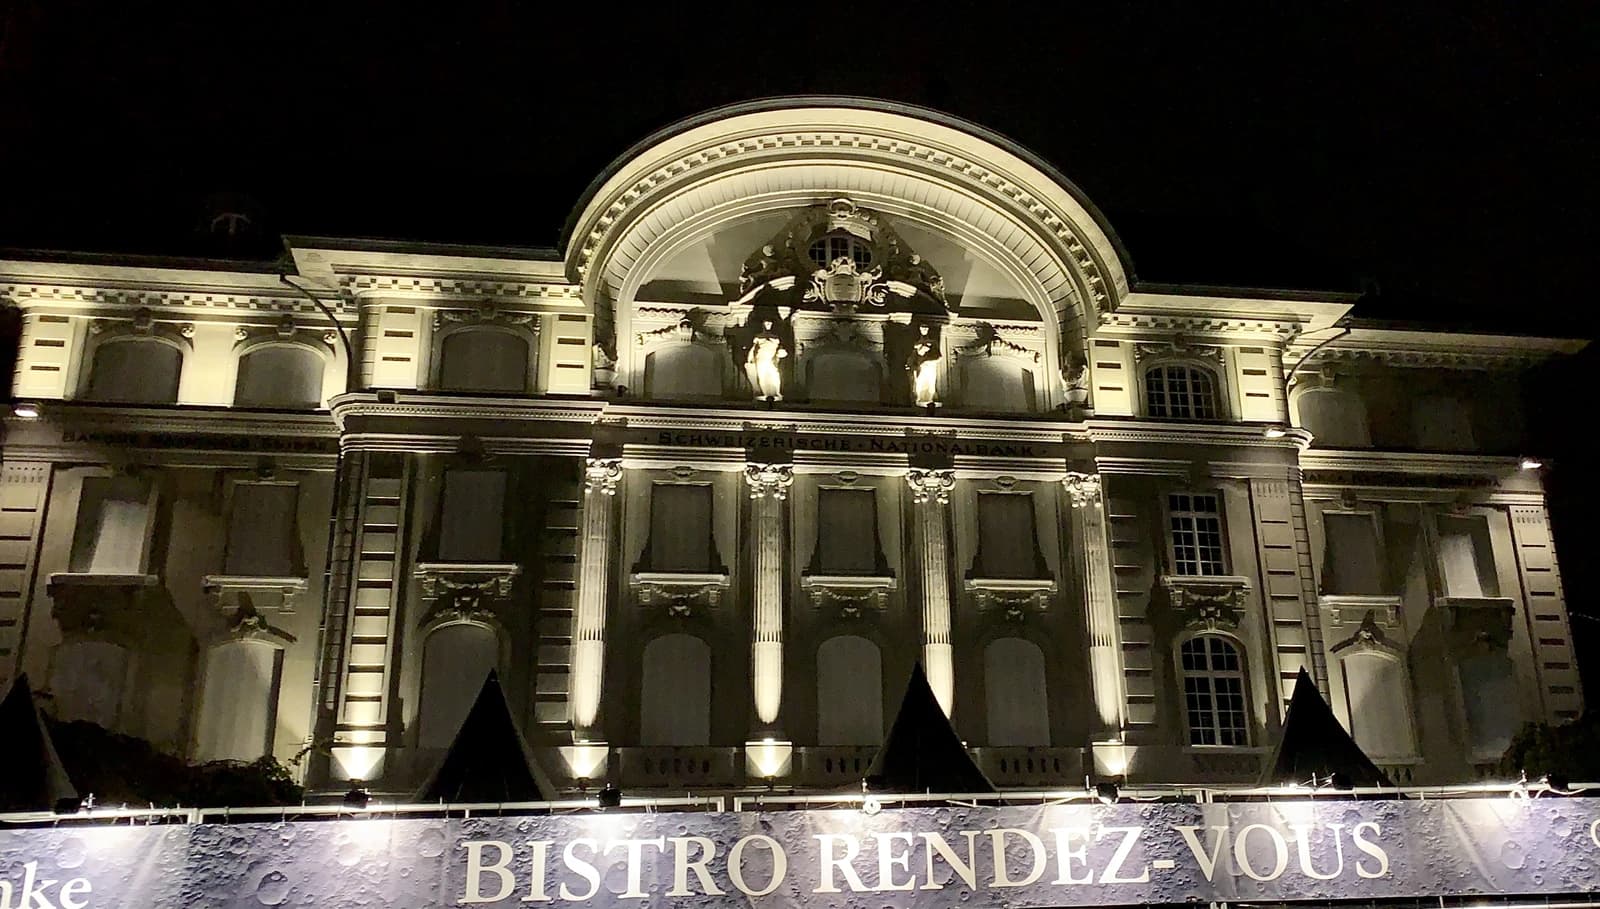
Swiss National Bank President Martin Schlegel said inflation has accelerated in recent months, but remains within the central bank’s stability range, keeping the focus on whether the next move in policy is still more likely to be caution than tightening.
That matters because Switzerland is balancing two competing forces: a firmer inflation pulse that argues against premature easing, and a strong franc that continues to weigh on exporters and broader growth. Schlegel’s comments suggest the SNB still sees price stability as intact, which gives policymakers room to tolerate a modest pickup in inflation without immediately changing course.
The message is important for markets because the Swiss franc is already acting as a de facto tightening channel. Schlegel said the exchange rate remains a challenge for the economy even as the real franc has been stable since 2020, underscoring how currency strength can suppress imported inflation while squeezing corporate margins. For investors, that keeps the SNB in the middle of a difficult trade-off: defend price stability without adding more pressure to an economy that is sensitive to currency moves and external demand.
The market backdrop also reinforces that tension. U.S. Treasury yields remain elevated, with the 10-year near 4.95% and the 2-year around 4.57%, a global rate backdrop that can support the dollar and complicate the SNB’s task of managing the franc. By contrast, the U.S. core inflation gauge rose only modestly in August in the supplied data, suggesting disinflation is not cleanly uniform across major economies and leaving central banks room to diverge in tone.
For Swiss equities and the franc-linked ETF FXF, the implication is straightforward: investors are likely to keep treating the currency as the key transmission mechanism for SNB policy rather than looking for an aggressive policy response to a small inflation pickup. FXF has slipped to 107.90, and the ETF’s price remains below its 200-day moving average, consistent with a market that is still wary of franc strength and growth pressure. UBS shares, meanwhile, have held up better, reflecting the bank’s diversified earnings base and less direct sensitivity to domestic inflation than the broader Swiss economy.
The bull case for the SNB’s current stance is that inflation remains contained, giving the central bank flexibility to avoid overreacting to short-term noise. The bear case is that a stronger franc and softer growth could eventually do the job of tightening for it, forcing the SNB to choose between protecting competitiveness and tolerating lower inflation.
For investors, the key next catalyst is whether recent inflation acceleration proves temporary or broadens enough to change the SNB’s language. If price gains stay inside the stability range, policy can remain measured. If the franc weakens or inflation firms further, markets may start to reassess how long the SNB can stay on hold.
| Entity | Gains | Losses |
|---|---|---|
| SNB | ▲Policy flexibility | ▼Pressure to react quickly |
| Swiss exporters | ▲Stronger price stability | ▼Strong franc, weaker margins |
| Swiss consumers | ▲Contained inflation | ▼If the franc weakens later |
| FXF holders | ▲Stability in policy outlook | ▼Further franc appreciation |