Treasury buybacks fail to lift bonds, yen
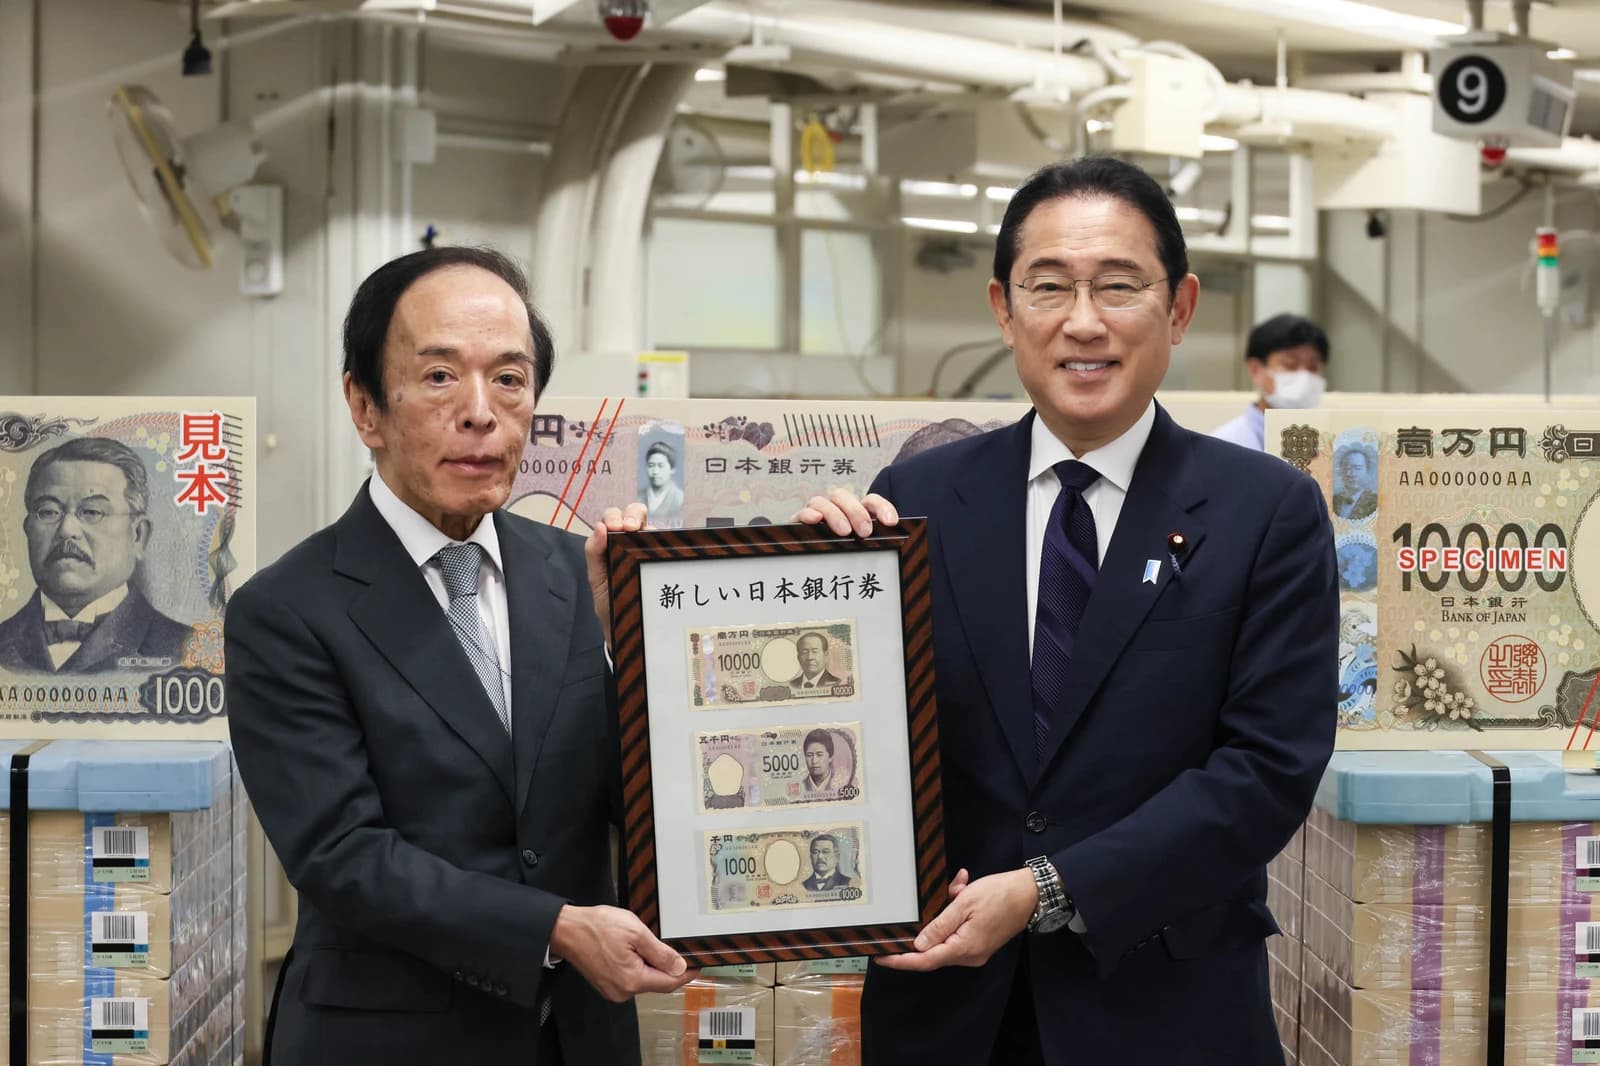
U.S. Treasury Secretary Scott Bessent’s push to use Washington’s balance sheet in currency and bond markets is drawing a skeptical market verdict, with investors saying the interventions have not yet delivered a durable break in long-dated Treasury yields or a convincing fix for the yen.
The question matters because the two markets Bessent is leaning on sit at the center of global capital pricing. A weaker dollar and lower Treasury yields can ease financial conditions, but if the interventions are seen as cosmetic, they risk adding volatility without changing the underlying drivers: stubborn U.S. growth, sticky inflation, a swelling fiscal deficit and, in Japan, the path of Bank of Japan policy.
Bessent has been unusually explicit about Treasury’s willingness to intervene. Speaking at SMU’s Cox School of Business on Sept. 8, he said the U.S. can use its balance sheet as a foreign-policy tool and pointed to a rare joint U.S.-Japan intervention on July 31 to support the yen. He also said he knew what Japanese officials and the BOJ were likely to do, and warned traders against betting against him.
Markets have not fully bought the argument. The yen strengthened from near 164 per dollar after the late-July intervention to above 155, but the move faded quickly and the currency slipped back toward 160 by the end of August. More recently, it has rebounded to around 153.6, near a seven-month high, though analysts say that advance has been driven more by expectations of a BOJ rate increase and short-covering than by the intervention itself.
That distinction matters for investors because it suggests the yen rally may not be a straight read-through of Treasury activism. If the BOJ tightens next week, the yen could keep gaining on domestic policy divergence. But if policy expectations disappoint, the currency could again be vulnerable once intervention effects wash out.
The bigger market test is in U.S. rates. On Sept. 9, Treasury said it would buy back $6 billion of longer-dated Treasuries in its first operation under Bessent’s expanded program, triple the original $2 billion size. Even so, investors had positioned for something closer to $8 billion to $10 billion, and the market response was telling: the 10-year yield rose 4 basis points to 4.845%, after briefly touching 4.935%, its highest since November 2023.
The long end remains under pressure for reasons a buyback programme cannot easily solve. The 30-year yield has recently climbed to its highest since 2007, reflecting not just supply concerns but still-solid growth and renewed inflation pressure from geopolitical shocks, including the Iran conflict, as well as the sheer scale of the U.S. budget deficit.
That is why the debate over Bessent’s approach is really a debate over whether Treasury can smooth market function or actually change price trends. Supporters argue the buybacks show Washington is attentive to disorderly moves in long bonds and to the risk that rising borrowing costs feed through to the economy and the government’s own debt service bill. They also say coordinated currency intervention can reinforce market expectations if it is backed by policy coordination in Tokyo.
Critics see something else: a Treasury moving away from its traditional slow, predictable playbook and into territory that may do more to manage headlines than yields. Mike O’Rourke of Jones Trading said the $6 billion figure disappointed and argued Bessent should abandon the policy. Evercore ISI’s Krishna Guha said markets were unimpressed because some investors had been looking for a much larger, market-shocking operation.
The credibility issue is as important as the immediate price action. If Treasury is seen as trying to lean against market pricing without addressing the fiscal arithmetic behind it, investors may conclude that intervention merely postpones repricing. Societe Generale’s Subadra Rajappa said the core issue is debt and deficits, not buybacks. BMO’s Ian Lyngen warned the moves could weaken the perception of Treasuries as a predictable safe asset.
For investors, the near-term setup is straightforward. Treasury intervention may slow or sharpen moves around the edges, but it is unlikely to overpower the fundamental forces keeping U.S. yields elevated unless fiscal and inflation dynamics improve. In Japan, the yen may remain supported if the BOJ moves toward tighter policy, though any appreciation would likely depend more on domestic rates than on Washington’s willingness to sell euros and buy yen.
| Entity | Gains | Losses |
|---|---|---|
| U.S. Treasury | ▲short-term market signaling | ▼credibility if yields stay high |
| BOJ / Japanese policymakers | ▲support for tighter policy path | ▼pressure to justify rate hikes |
| Yen bulls | ▲policy support and short covering | ▼if BOJ disappoints |
| Treasury bond bears | ▲higher yields and supply pressure | ▼if buybacks deepen and support bonds |