UK Gilt Yields Hit 18-Year High
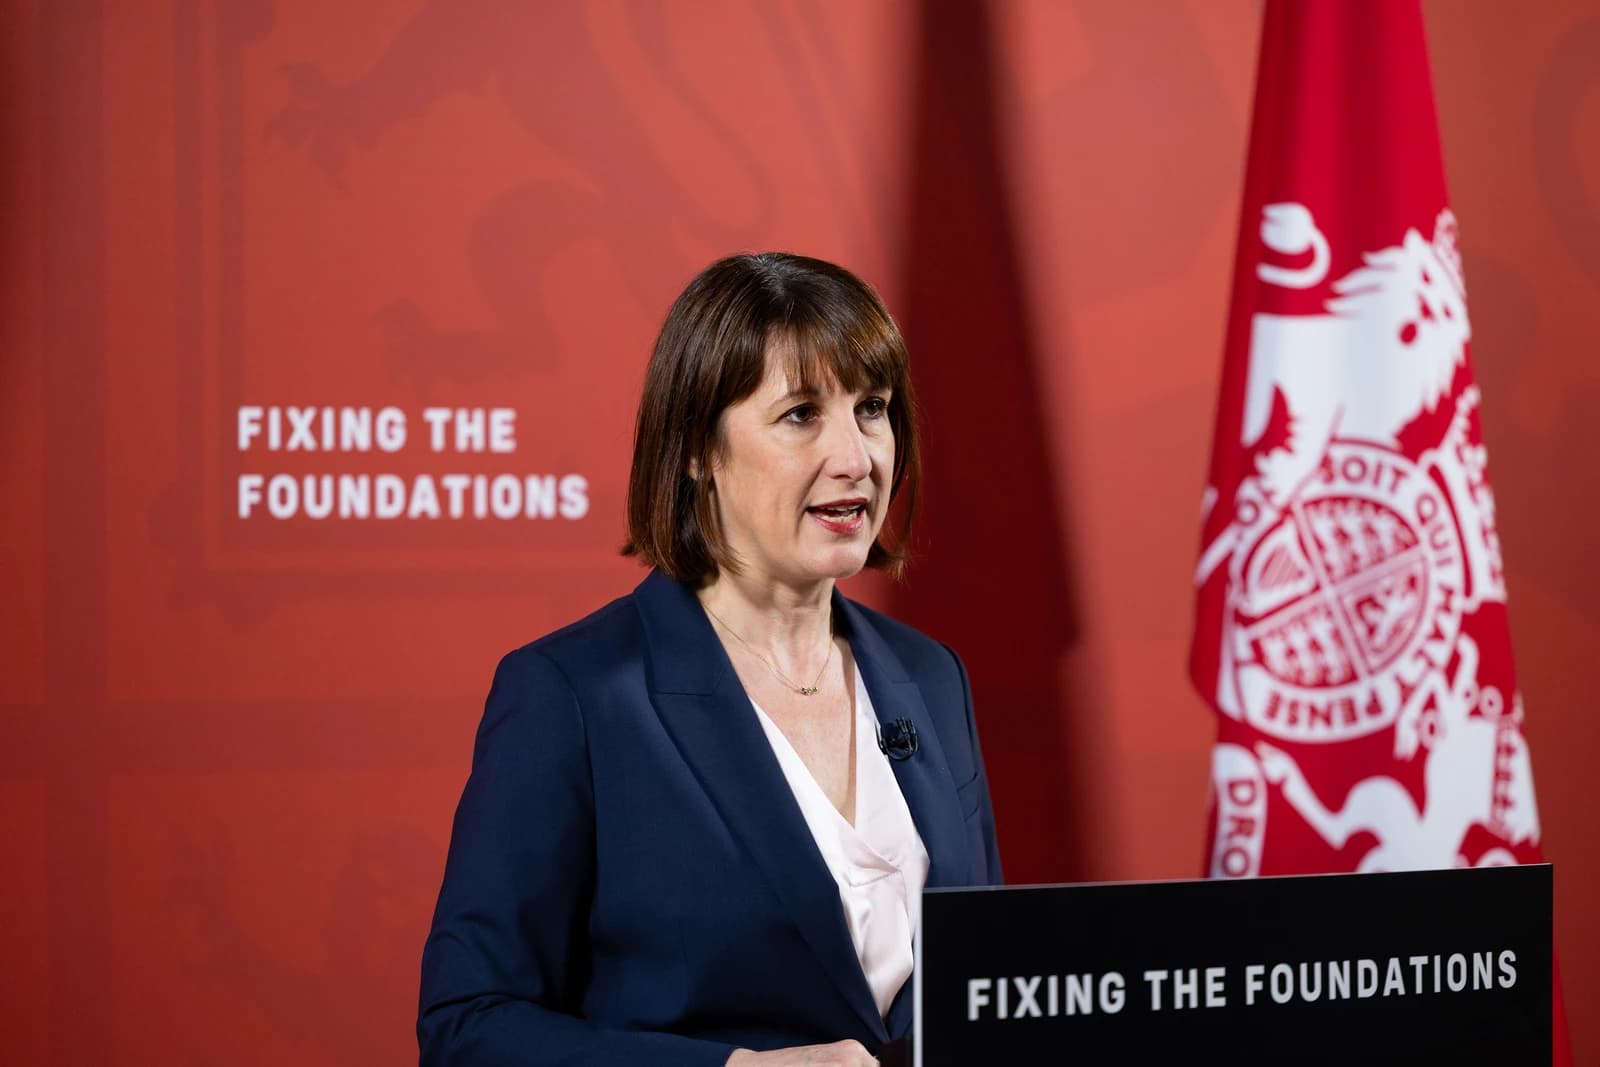
UK government borrowing costs have pushed to their highest level in 18 years, sharpening the fiscal squeeze on Chancellor Rachel Reeves and raising the stakes for investors who own British assets.
The move matters because higher gilt yields make it more expensive for the government to fund itself, and that can ripple quickly through the wider economy. When the 10-year yield climbs, as it has in the US and elsewhere, debt servicing costs rise, mortgage rates can stay sticky, and companies face a tougher backdrop for investment and refinancing. For Britain, that is especially uncomfortable given the government’s already tight fiscal headroom.
The pressure is clear in the broader bond market. US 10-year Treasury yields are sitting around 4.8%, while two-year yields are near 4.4%, showing global rates remain elevated even after the era of ultra-cheap money. Investors have also been demanding a higher premium to hold long-dated debt, with the bond market signaling less tolerance for large deficits and more concern about inflation sticking above central bank targets.
That dynamic is one reason gilt investors are focusing so closely on any signs of fiscal slippage in London. If the government is forced to borrow more at higher rates, it can crowd out spending plans or force tax decisions that weigh on growth. Either way, the market message is the same: the cost of credibility is rising.
For investors, the implications go beyond the headline. Higher yields can be a headwind for rate-sensitive sectors such as housing, utilities and infrastructure, while they can also pressure the valuation of long-duration growth stocks. At the same time, a persistent rise in borrowing costs can make UK equities look cheaper on paper, but only if earnings can hold up and policy stays predictable.
There is also a technical layer worth watching in bond markets. The iShares 20+ Year Treasury Bond ETF, or TLT, remains below its 50-day and 200-day moving averages, a sign that long-duration bonds have not yet won back investor confidence. Adalytica’s trade signals for Treasury bonds show “fear” sentiment, underlining how cautious the market remains even after recent swings.
The bigger story is that Britain is once again being forced to prove it can borrow without rattling investors. If gilt yields keep climbing, Reeves may have less room to maneuver on growth promises and more pressure to show budget discipline. For long-term investors, that makes UK bonds, sterling assets and domestic cyclicals worth watching closely rather than chasing.
| Entity | Gains | Losses |
|---|---|---|
| Gilt buyers | ▲Higher income | ▼Price volatility |
| UK government | ▲Potential demand for debt | ▼Higher borrowing costs |
| UK borrowers | ▲None | ▼Pricier mortgages and loans |
| Long-dated bond holders | ▲None | ▼Mark-to-market losses |