US Financial Sector Activity Falls in June
US financial-sector activity fell back in June after a brief rebound, even as the broader Treasury index posted a 3.51% gain in the month, underscoring that the sector’s growth is still being powered by transaction-heavy financial businesses rather than a clean, economy-wide acceleration.
That mix matters because financial activity is one of the clearest real-time barometers of demand for credit, trading, underwriting and other fee-generating services. A sector that is growing, but doing so unevenly, tells investors that banks and capital-markets firms are still finding volume, yet are operating in an environment where momentum is concentrated in specific lines of business rather than across the board.
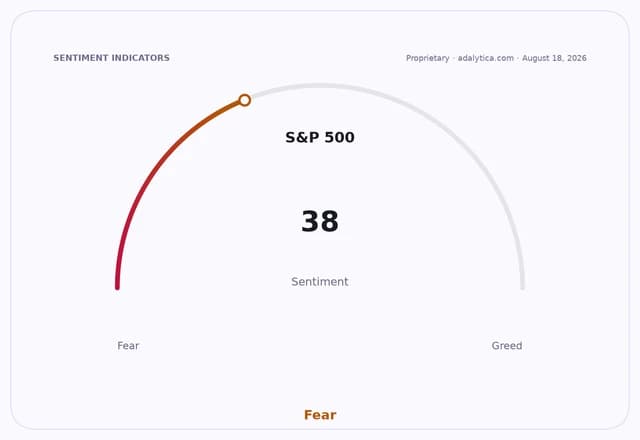
The Treasury’s ISE measure resumed its downward path in June, reversing the prior month’s gain and pointing to a softer tone in some parts of the financial complex. The sequence suggests that the June bounce was not the start of a new trend, but a pause in an otherwise fragile pattern. Against that backdrop, the 3.51% overall rise looks less like broad-based strength and more like the result of financial activity doing the heavy lifting.
That interpretation is consistent with company filings showing clients remained active in markets and transactions. Goldman Sachs said client activity was the primary driver of FICC intermediation revenues, while JPMorgan and Bank of America pointed to higher market-related volumes and rising assets. In other words, the sector is still being supported by trading, financing and advisory work, but the data do not yet point to a durable, all-seasons expansion in underlying financial conditions.
For investors, that makes the read-through more nuanced. Bullish holders of large diversified banks can point to continuing revenue support from market-sensitive businesses and the resilience of fee pools. Bears will note that a falling ISE index, even alongside overall growth, can precede slower loan demand, more uneven net interest income and a tougher backdrop for smaller lenders with less trading exposure.
The market reaction has echoed that split. Financial ETFs such as XLF remain above both the 50-day and 200-day moving averages, suggesting the group’s longer-term trend is still constructive, while regional-bank funds KBE and KRE have also held gains. But recent RSI readings around neutral levels and fading momentum in some sessions indicate the rally is no longer running on pure enthusiasm. Investors appear to be waiting for confirmation that June’s weakness in the ISE measure is temporary and that financial activity can broaden beyond a few strong pockets.
Macro conditions add another layer. The 10-year Treasury yield around 4.64% to 4.68% keeps funding costs elevated relative to the low-rate years and reinforces the importance of transaction income over balance-sheet spread expansion. At the same time, Adalytica’s US dollar trade signal shows “Extreme Fear,” a reminder that currency and rate volatility can continue to drive activity in markets businesses even if the underlying economic backdrop remains mixed.
The key question going into the next round of data is whether the sector can turn activity-led growth into something more durable. If client volumes stay firm and rates remain volatile, the largest banks should keep benefiting. If the June dip in the ISE index proves to be the start of a broader slowdown, however, the winners may narrow to the firms most dependent on trading, while more rate-sensitive lenders and smaller regional banks could see the pace of improvement fade.
| Entity | Gains | Losses |
|---|---|---|
| Large banks | ▲Trading and client activity | ▼Broader loan-growth weakness |
| Regional banks | ▲Higher sector sentiment | ▼Less market-driven revenue |
| Financial ETFs | ▲Support from resilient majors | ▼Slower momentum if activity cools |
| Borrowers | ▲Stable access to credit | ▼Higher-for-longer funding costs |