U.S. Treasury expands bond buyback program
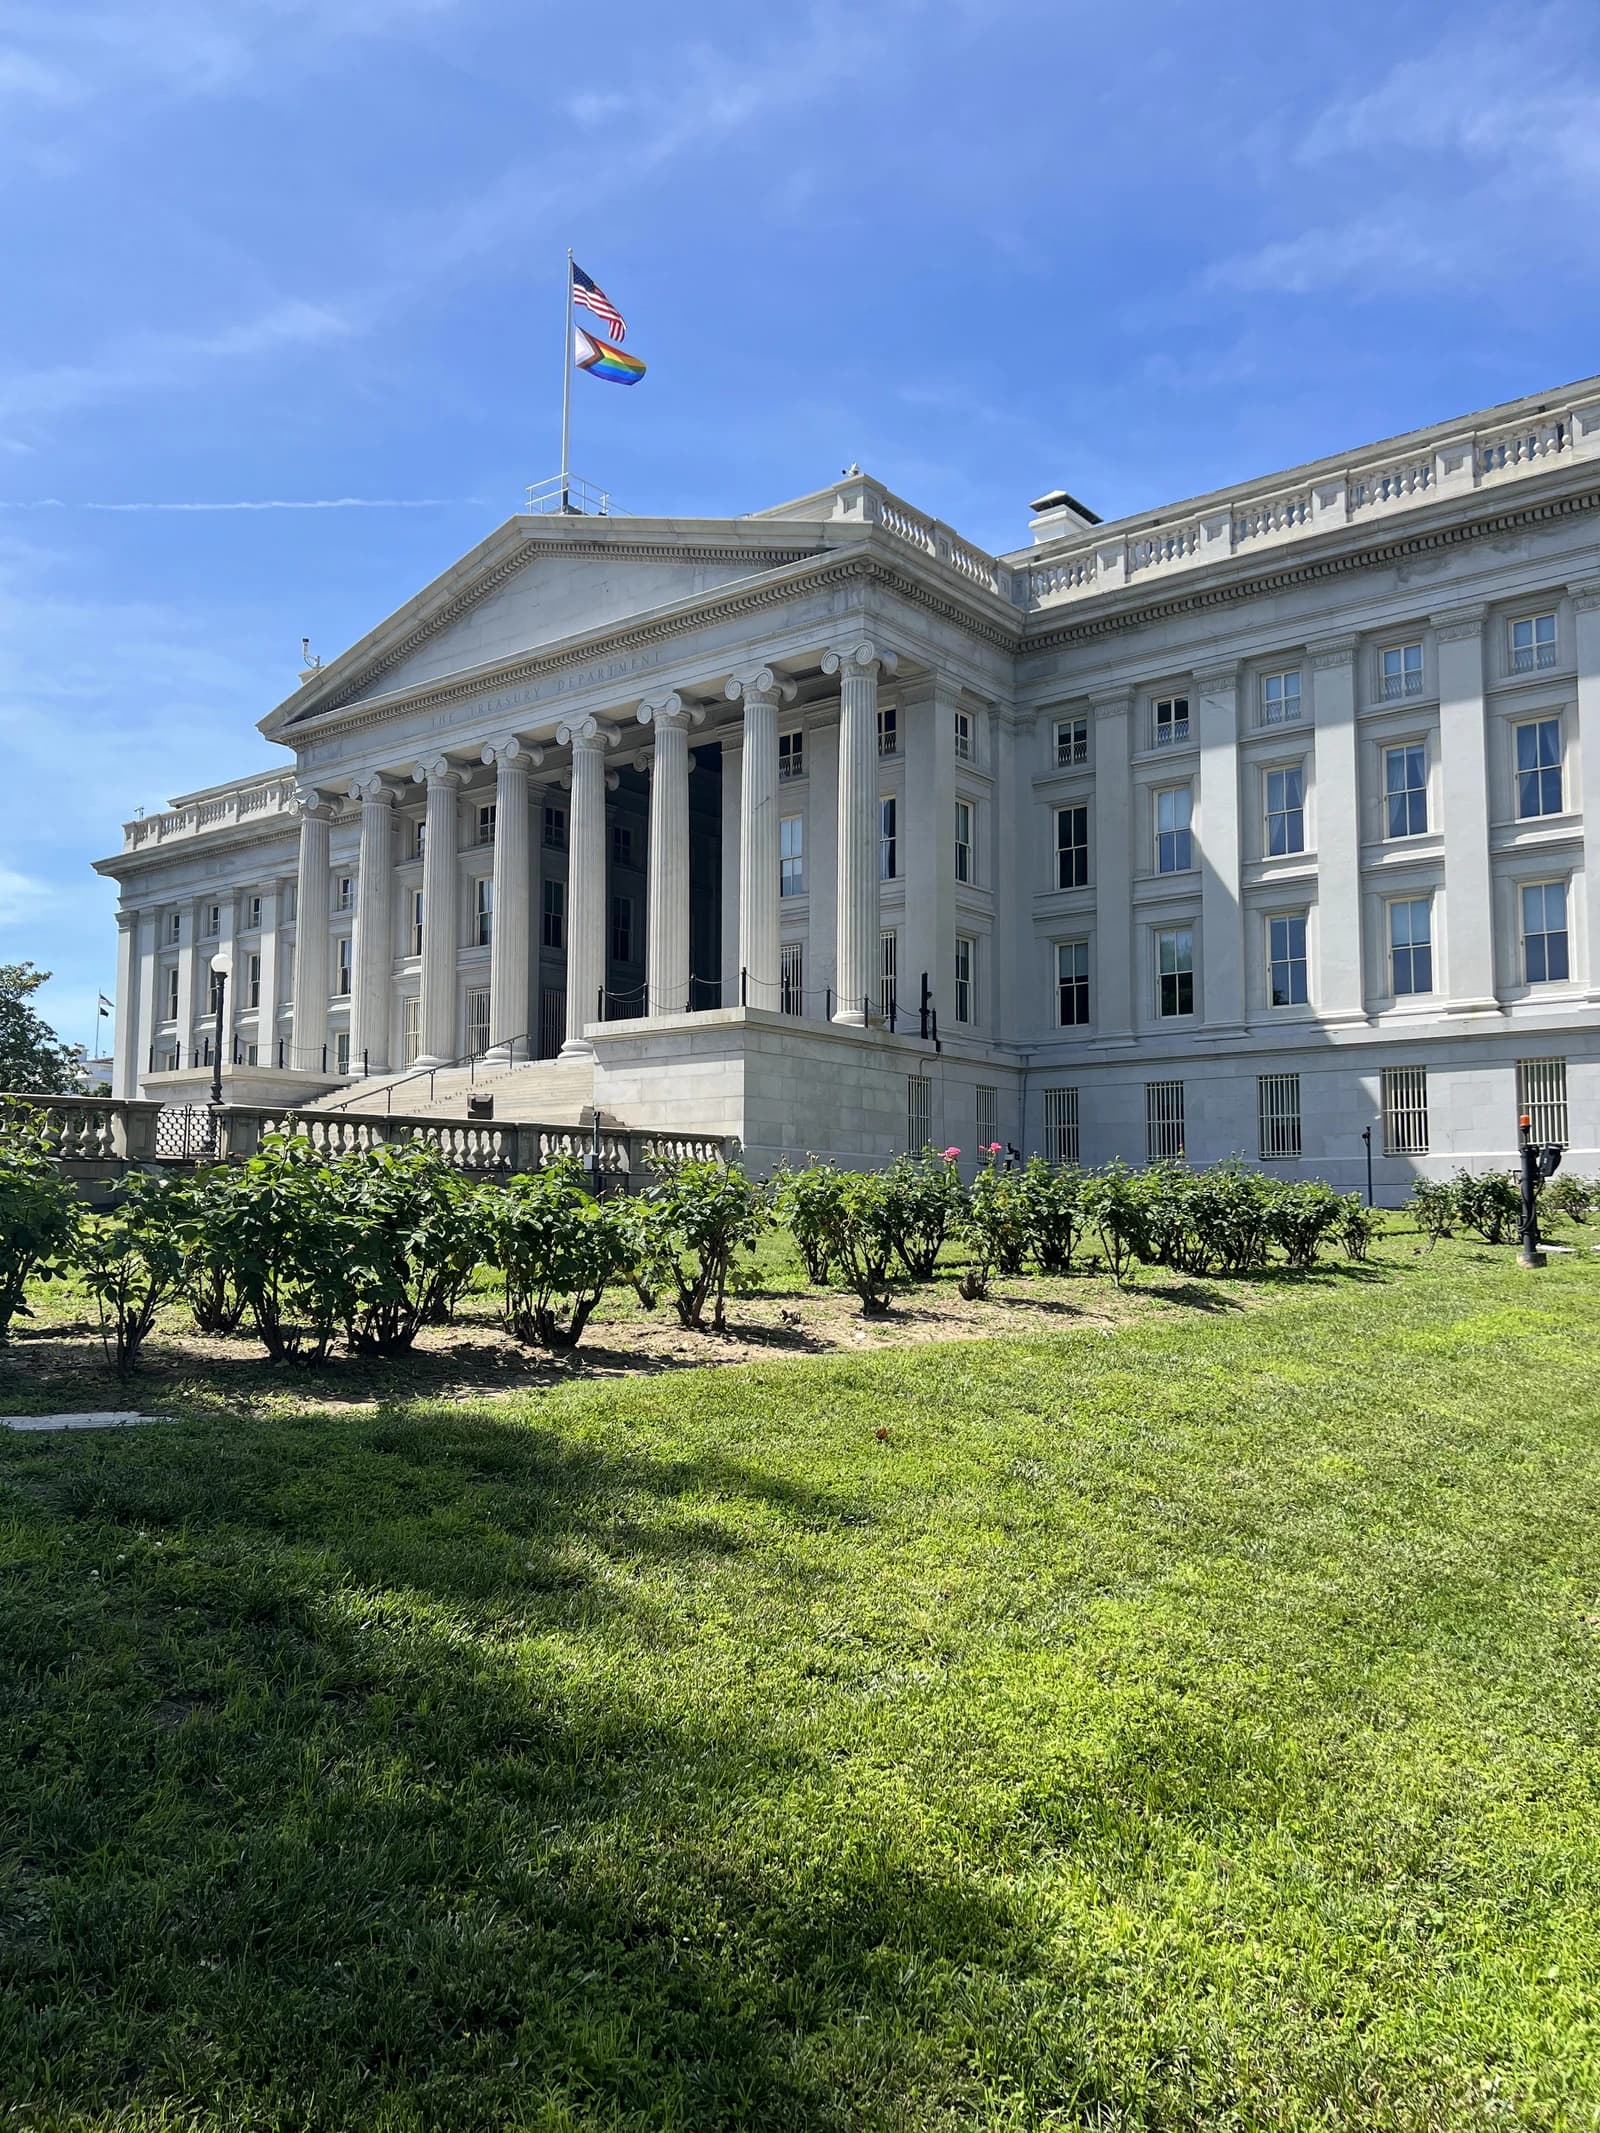
Scott Besant said the Treasury’s expanded buyback program is meant to cool an overheated bond market, not to mimic quantitative easing, as the U.S. prepares its first round of repurchases under a bigger long-dated debt plan.
The Treasury is set to buy back 10-year to 20-year bonds on Sept. 9, with the first operation expected to top $4 billion after Besant last month doubled the size of the program from the previous $2 billion minimum. Markets had been bracing for a larger move after the 30-year Treasury yield climbed to its highest level since 2007, underscoring how much pressure has built on long-dated government debt.
Besant, speaking in Washington, framed the effort as a market-stabilization tool rather than stimulus. He compared it more to a Treasury version of Operation Twist, saying the goal is to push the market back toward balance, while rejecting criticism that the buybacks amount to Fed-style quantitative easing.
That distinction matters for investors because Treasury repurchases can influence duration supply and term premiums without changing the policy rate. If the program absorbs enough long bonds, it can help steady yields at the long end, where borrowing costs for the government, corporations and households are most sensitive to swings in demand.
The move also lands at a moment when investor appetite for long-duration U.S. debt is being tested. The 10-year Treasury yield was at 4.77% in the latest reading, the 2-year at 4.34%, and the spread between them stood at 0.40 percentage point, while long-bond ETF TLT traded around 82.2 and remained below its 200-day moving average.
Adalytica’s Treasury bonds trade signals showed extreme greed around TLT, while the S&P 500 signal sat in extreme fear and the dollar registered greed, reflecting the tug of war between higher yields, risk aversion and a firmer greenback. The Treasury’s buyback expansion is intended to blunt that pressure, but it may also confirm that policymakers see the long end as fragile enough to require active support.
Investors will now watch the size and pace of the Sept. 9 operation, along with upcoming inflation data and Fed commentary, for signs that higher yields are becoming a more durable feature of the market rather than a temporary dislocation.
| Entity | Gains | Losses |
|---|---|---|
| U.S. Treasury | ▲More control over long-end yields | ▼Less flexibility if yields keep rising |
| Bond holders | ▲Short-term price support | ▼Risk of lower returns if buybacks fail |
| Borrowers | ▲Potentially steadier financing costs | ▼Still exposed to higher long rates |
| Short-duration assets | ▲Relative appeal if long yields stay elevated | ▼Less upside if the curve normalizes |