US Treasury Yields Near 5% Lift Borrowing Costs
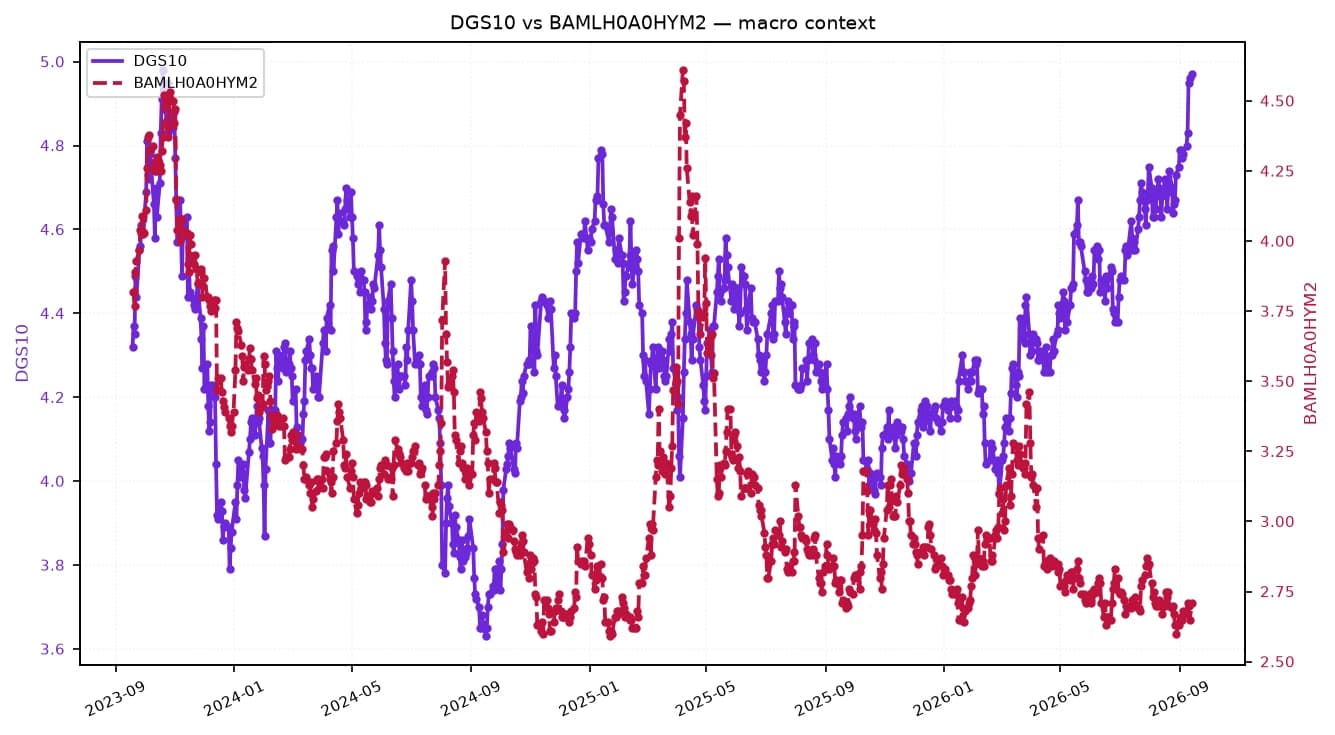
Global bond issuance is picking up just as US Treasury yields push above 5%, raising the cost of capital for governments and companies and forcing borrowers to move before financing windows tighten further.
The move in rates is the bigger story for markets. The US 10-year yield has climbed to 4.97%, with a forecast pointing to 5.043%, levels last seen around the 2007 financial crisis, while the 2-year note is at 4.65%, signaling investors are pricing a more aggressive Federal Reserve path.
That backdrop matters because higher benchmark yields quickly feed into global funding costs. When Treasuries rally in yield terms, new debt sales from sovereigns, banks and companies must clear at steeper coupons, which can slow issuance, pressure balance sheets and compress valuations across rate-sensitive assets.
Credit markets are already showing the strain. The Bloomberg high-yield spread index is around 2.71 percentage points, down from recent peaks but still wide enough to indicate cautious demand for lower-rated borrowers, while the broader bond market has been hit by negative total returns as investors absorb the shift in rate expectations.
Treasury ETFs are reflecting the pressure. TLT closed at 80.71 and IEF at 90.82, both well below their 50-day moving averages, while RSI readings for both funds are deeply oversold, a sign of heavy selling rather than stable demand for duration.
The pressure is not just a US story. Nigeria said it raised N728.9 billion in a second bond sale aimed at settling power-sector debts, showing that even emerging-market sovereigns are using the market to clean up liabilities before financing conditions worsen further.
For investors, the implication is a tougher environment for long-duration bonds, refinancing-heavy sectors and sovereign borrowers with large funding needs. Shorter-dated debt and cash-like assets are likely to retain favor if the Fed follows through on tightening and the 10-year Treasury holds near 5%.
The next test is whether more borrowers rush to market before rates climb again, and whether higher issuance meets enough demand to keep spreads contained.
| Entity | Gains | Losses |
|---|---|---|
| US Treasury sellers | ▲Lock in funding before yields rise further | ▼Face higher coupon costs |
| Bond investors in cash/short duration | ▲Better reinvestment yields | ▼Miss price upside in long bonds |
| Long-duration bondholders | ▲Potential carry if rates stabilize | ▼Mark-to-market losses |
| Nigeria and other issuers | ▲Address financing needs now | ▼Pay up in a tighter market |