USDA No-Down-Payment Mortgage Draws Renewed Attention
The USDA’s no-down-payment mortgage is drawing renewed attention because it offers one of the few ways cash-strapped buyers can still finance a home in full at a time when prices, insurance costs and borrowing expenses have made the upfront hurdle to homeownership unusually high.
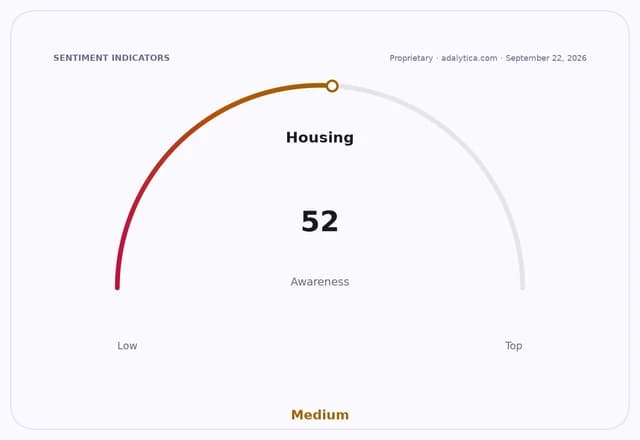
That matters economically because the biggest barrier for many first-time buyers is no longer just the monthly mortgage payment, but the lump sum needed to close. By allowing qualified borrowers to finance 100% of the purchase price, the USDA-guaranteed loan can keep households in the market that might otherwise be priced out, supporting demand in lower-density housing markets and parts of the suburban fringe where eligibility can extend beyond what most buyers think of as rural America.
The programme’s reach is broader than its name suggests. About 97% of U.S. land mass falls within eligible areas, according to Ashley Harris of Neighbors Bank, though income and occupancy tests still narrow the field sharply. Under current rules, areas with populations below 10,000 generally qualify, and some communities with as many as 35,000 residents can still be eligible if they previously had rural status or lack enough affordable housing and mortgage credit. In practice, USDA boundaries can slice through suburban neighborhoods, leaving homes on opposite sides of the same street with different financing options.
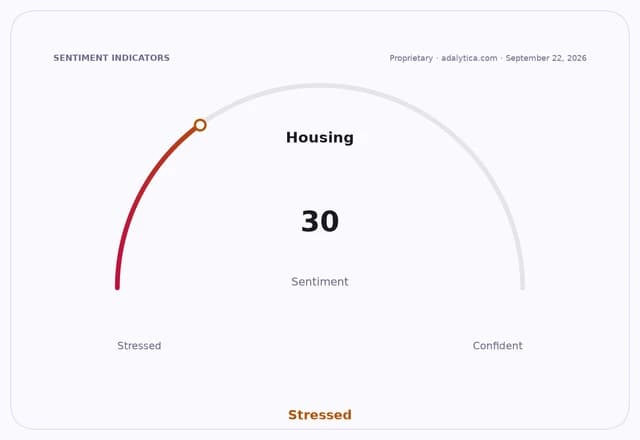
The attraction is obvious in today’s housing market. The Joint Center for Housing Studies at Harvard said about 43.5 million U.S. households were cost-burdened in 2024, spending more than 30% of income on housing. The median price of an existing single-family home was about $434,800 in the second quarter of 2026, according to the National Association of Realtors. Against that backdrop, the USDA loan is less a niche programme than a pressure valve for buyers who have steady incomes but limited savings.
Still, zero down does not mean zero cost. Borrowers pay a 1% upfront guarantee fee and a 0.35% annual fee, so the loan is not free leverage. On a $350,000 home, the upfront fee would be $3,500 and the annual fee would initially add $1,225 a year, spread through monthly payments. The programme also comes with constraints: the home must be the borrower’s primary residence, cannot be a vacation home or investment property, and must meet safety and structural standards. A standard USDA loan also cannot be used to buy a working farm, which limits its appeal for some buyers in agricultural areas.
For lenders and housing-finance firms, the programme can expand originations without the credit risk profile of subprime lending, because USDA guarantees backstop part of the loan. For builders and sellers in eligible markets, it can widen the pool of potential buyers at a moment when affordability remains strained. That helps explain why mortgage lenders and housing names such as Rocket Companies, New Residential Investment and Radian Group remain tied to shifts in affordability, even when broader mortgage demand is weak.
The bull case for USDA lending is that it improves access without requiring a large public subsidy at the point of sale, and it can keep rural and semi-rural housing markets liquid as traditional down-payment thresholds become harder to meet. The bear case is that it remains highly rules-based, geographically uneven and dependent on income caps that exclude many households who are otherwise housing-stressed.
For investors and homebuyers alike, the key point is that the USDA programme is not a broad fix for the housing shortage. But in a market where affordability has become the main constraint, it is one of the few federal tools that can still turn a buyer with income but little savings into a borrower with a path to ownership.
| Entity | Gains | Losses |
|---|---|---|
| USDA-eligible buyers | ▲Lower upfront cash need | ▼Fee burden and restrictions |
| Rural/suburban sellers | ▲Larger buyer pool | ▼Limited to eligible areas |
| Mortgage lenders/guarantors | ▲More originations | ▼Policy and credit-rule risk |
| Cash-poor non-eligible buyers | ▲Few immediate benefits | ▼Still shut out of ownership |