Venezuela Gold Transfer to New York
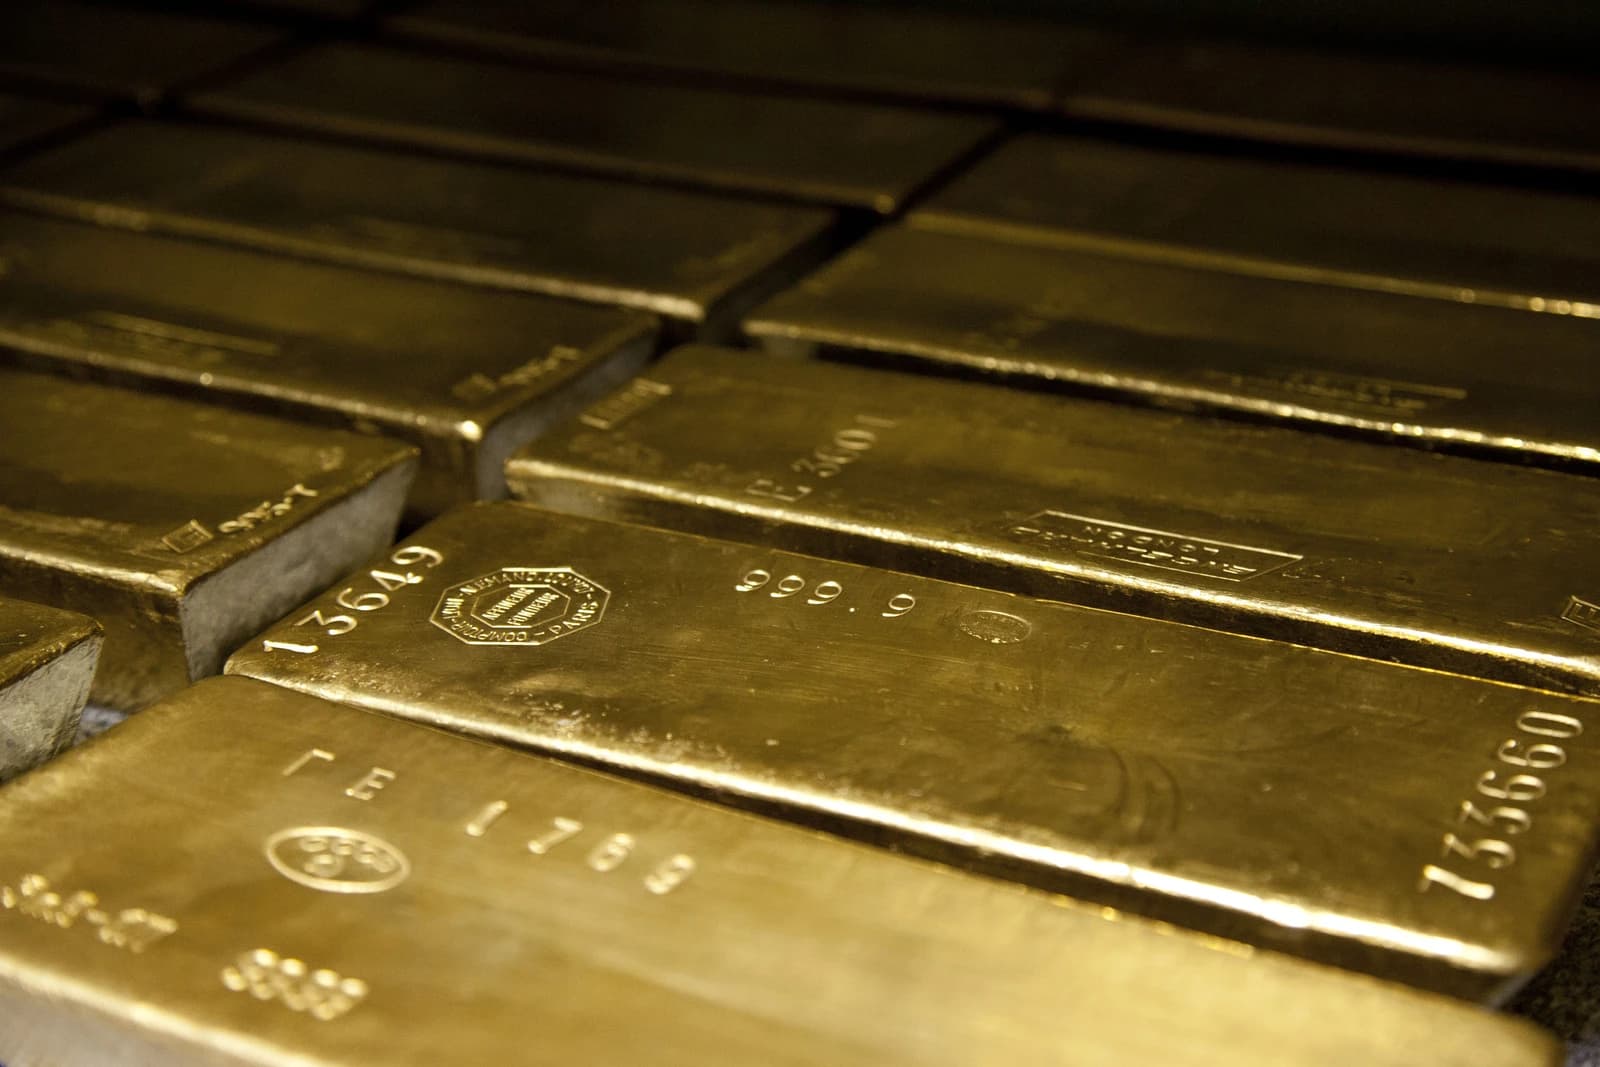
Venezuela is close to shifting about 31 metric tons of sovereign gold, valued at roughly $4 billion, from the Bank of England to New York in a rare accord that could unlock a long-frozen asset and reshape the country’s financing options.
The proposed transfer matters because it would move a politically trapped reserve into a custody structure that could be easier to use as collateral, while also ending a seven-year legal standoff in London that has left one of Venezuela’s most valuable external assets effectively immobilized since 2019. For Caracas, the deal offers a path to turn bullion into financing rather than dead capital. For creditors, counterparties and sanctions lawyers, it is a test case for how contested sovereign assets can be handled when political recognition is unresolved.

According to the reporting cited in the Spanish-language account, the Venezuelan government and the opposition platform have reached the final phase of an agreement after technical committees cleared major legal, regulatory and sanctions-compliance hurdles. Reuters and the Financial Times have both reported that high-security transport firms have already mapped out the logistics, underscoring that the transaction has moved beyond politics and into execution.
Under the terms being discussed, Venezuela would retain legal title to the metal but would not gain immediate discretionary access to sell the bars. Instead, the gold would be held in the United States and potentially pledged as collateral for international loans aimed at domestic development projects. That arrangement is significant because it preserves the asset while creating a financing mechanism that could appeal to lenders seeking tighter custody and audit controls. The expected deposit structure at the U.S. Treasury, with oversight by international auditors, appears designed to reduce the risk of diversion and make the asset more bankable.

Economically, the move reflects how constrained emerging-market sovereigns are trying to convert reserve assets into usable funding without a conventional sovereign bond market. Venezuela’s access to external capital has been heavily impaired by sanctions, litigation and political fragmentation, leaving reserve assets among the few remaining sources of leverage. If the deal holds, the country could gain a financing bridge for infrastructure and reconstruction at a time when its domestic economy remains starved of investment.
For investors, the immediate impact is less about bullion supply than about precedent and optionality. Gold itself would not be entering the market for sale, but the ability to mobilize reserve assets could matter for Venezuela’s broader asset recovery and debt-negotiation prospects. It may also influence pricing of Venezuela-linked claims and litigation assets, as well as sentiment around other frozen sovereign reserves caught between courts, sanctions and rival political claims.
The development lands in a gold market already supported by strong investor demand and elevated risk aversion. SPDR Gold Shares, or GLD, has been trading near $400, while technical readings show the fund below its 200-day moving average and with RSI in mid-range territory, suggesting that the market has recently cooled after a strong run. Gold miners tracked by GDX have also pulled back from earlier highs but remain well above many of their longer-term trend levels. That backdrop suggests investors are still treating bullion as a strategic hedge even as the market digests whether political and custody changes abroad can alter supply dynamics at the margins.
The broader narrative is that Venezuela is trying to turn a frozen symbol of state wealth into a functioning financial instrument. If the transfer is completed, it would mark a pragmatic compromise between a government that needs liquidity and an opposition that wants legal safeguards, while giving U.S.-based custody a central role in the stewardship of one of the most politically sensitive gold hoards in the world. The key question now is whether the agreement survives final legal and regulatory scrutiny — and whether the gold, once in New York, can actually be used to finance anything meaningful without reigniting the same disputes that immobilized it in London.
| Entity | Gains | Losses |
|---|---|---|
| Venezuelan government | ▲Financing flexibility | ▼Immediate discretionary access |
| Opposition platform | ▲Oversight safeguards | ▼Political leverage |
| US custodians/Treasury | ▲Larger custody role | ▼Compliance burden |
| Bank of England | ▲Less legal exposure | ▼Custody revenue and relevance |