Vietnam Banks Credit Grows 10.24% by Aug. 28
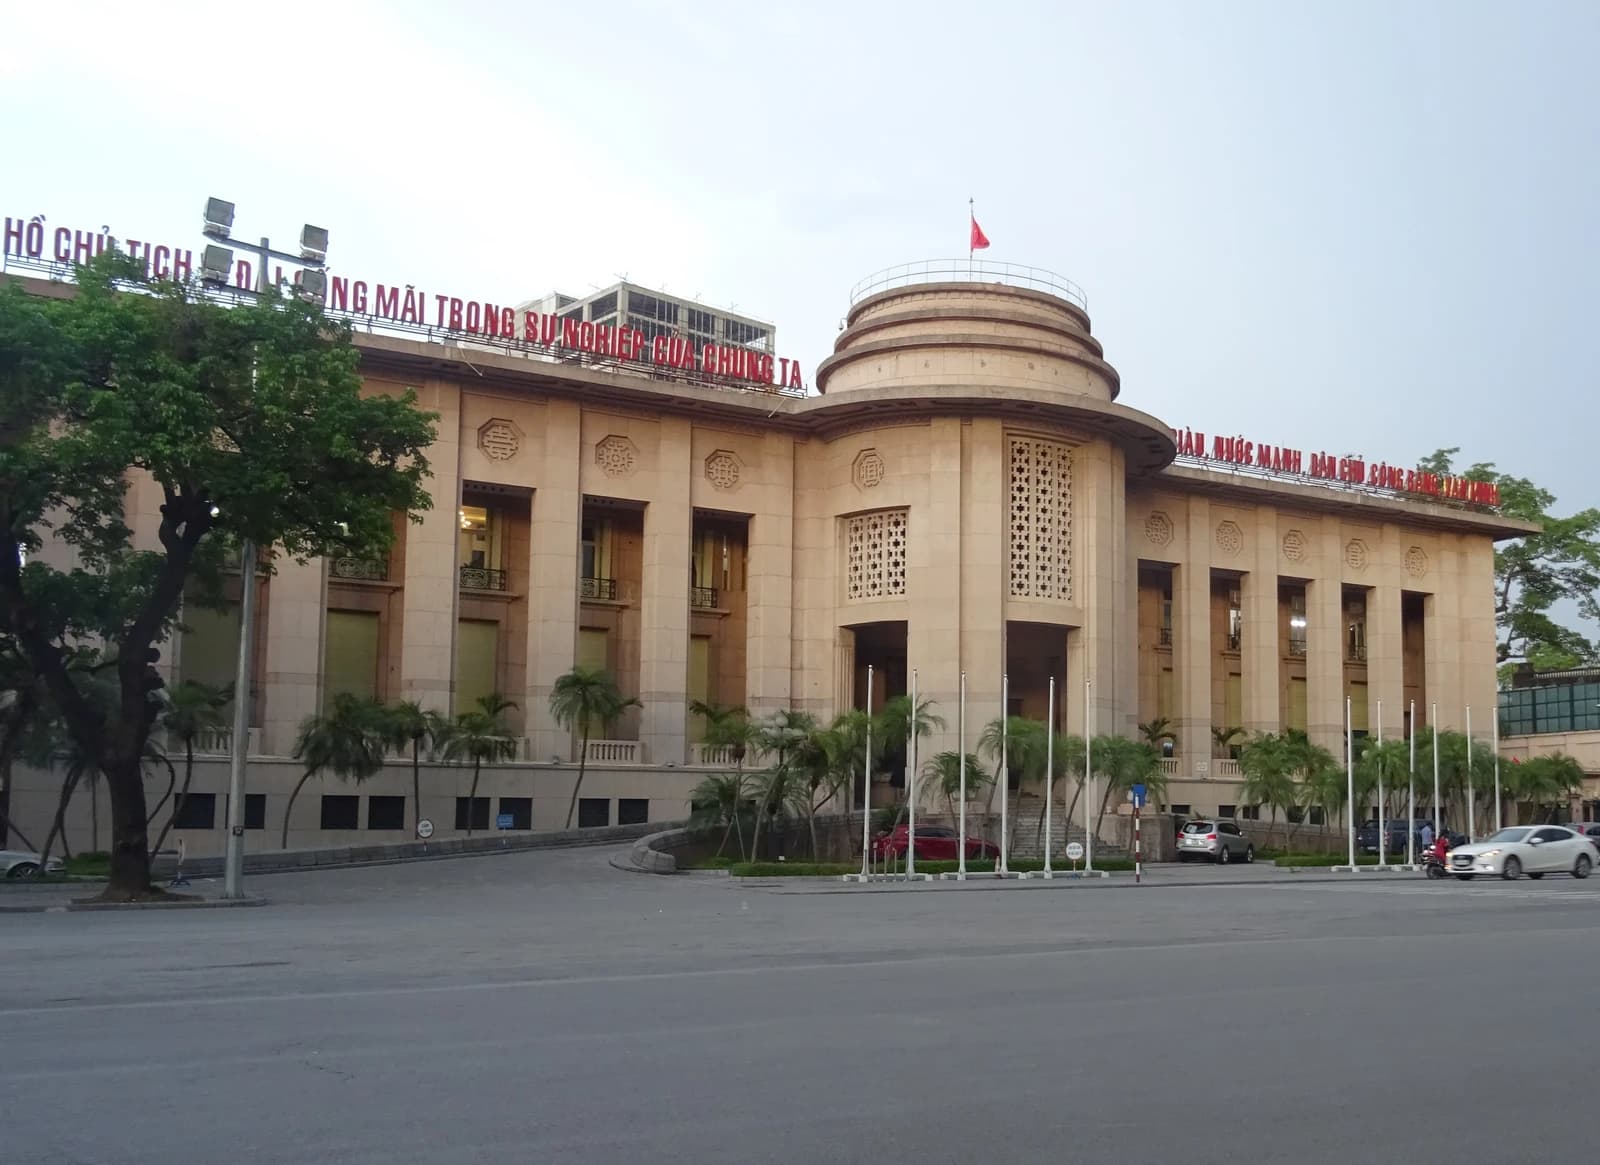
Vietnam’s banking system had outstanding credit of nearly 21 quadrillion dong by Aug. 28, underscoring how fast lenders are expanding balance sheets as the government leans on credit to support growth.
The State Bank of Vietnam said total outstanding loans rose 10.24% from the end of 2024, with small and medium-sized enterprises accounting for more than 4.1 quadrillion dong, or about 20% of the total. That puts bank lending at the center of Vietnam’s policy effort to sustain investment and consumption at a time when officials are trying to balance expansion with rising debt risks.
The scale matters because credit remains one of Vietnam’s main transmission channels for growth. Faster lending can help fund working capital, real estate activity, manufacturing and consumer demand, but it also increases pressure on banks to assess borrowers’ repayment capacity, particularly as global borrowing costs stay elevated and domestic credit quality comes under closer scrutiny.
To support that push, 19 banks have announced preferential lending packages worth more than 407 trillion dong after more than a month of implementation. The loans carry rates 1 to 2 percentage points below average market levels for similar tenors, signaling regulators’ willingness to nudge capital toward productive sectors without resorting to a broad-rate cut.
The loan expansion comes as Vietnam also prepares to court international investors through a non-deal roadshow, part of efforts to keep funding channels open as the government weighs future overseas bond issuance. At the same time, local equities remain sensitive to foreign flows, liquidity and the country’s upcoming FTSE Russell emerging-market upgrade, with financial shares and banks at the center of investor positioning.
For investors, the message is two-sided: stronger credit growth supports earnings for lenders and can help keep the economy on a firmer footing, but it also raises the stakes for asset quality, margin discipline and regulatory oversight if borrowing accelerates faster than cash flow.
| Entity | Gains | Losses |
|---|---|---|
| Vietnamese banks | ▲Loan growth, interest income | ▼Higher credit risk |
| SMEs and borrowers | ▲Easier access to capital | ▼More debt burden |
| Economy / policymakers | ▲Faster growth support | ▼Greater financial stability pressure |
| Conservative lenders / short credit | ▲Lower risk exposure | ▼Missed lending upside |