Vietnam’s National Assembly on Nov. 6 began debating amendments to the corporate income tax and personal income tax laws, a step that could reshape the country’s fiscal take, corporate investment incentives and household tax burden.
Vietnam Assembly Debates Corporate and Income Tax Reforms
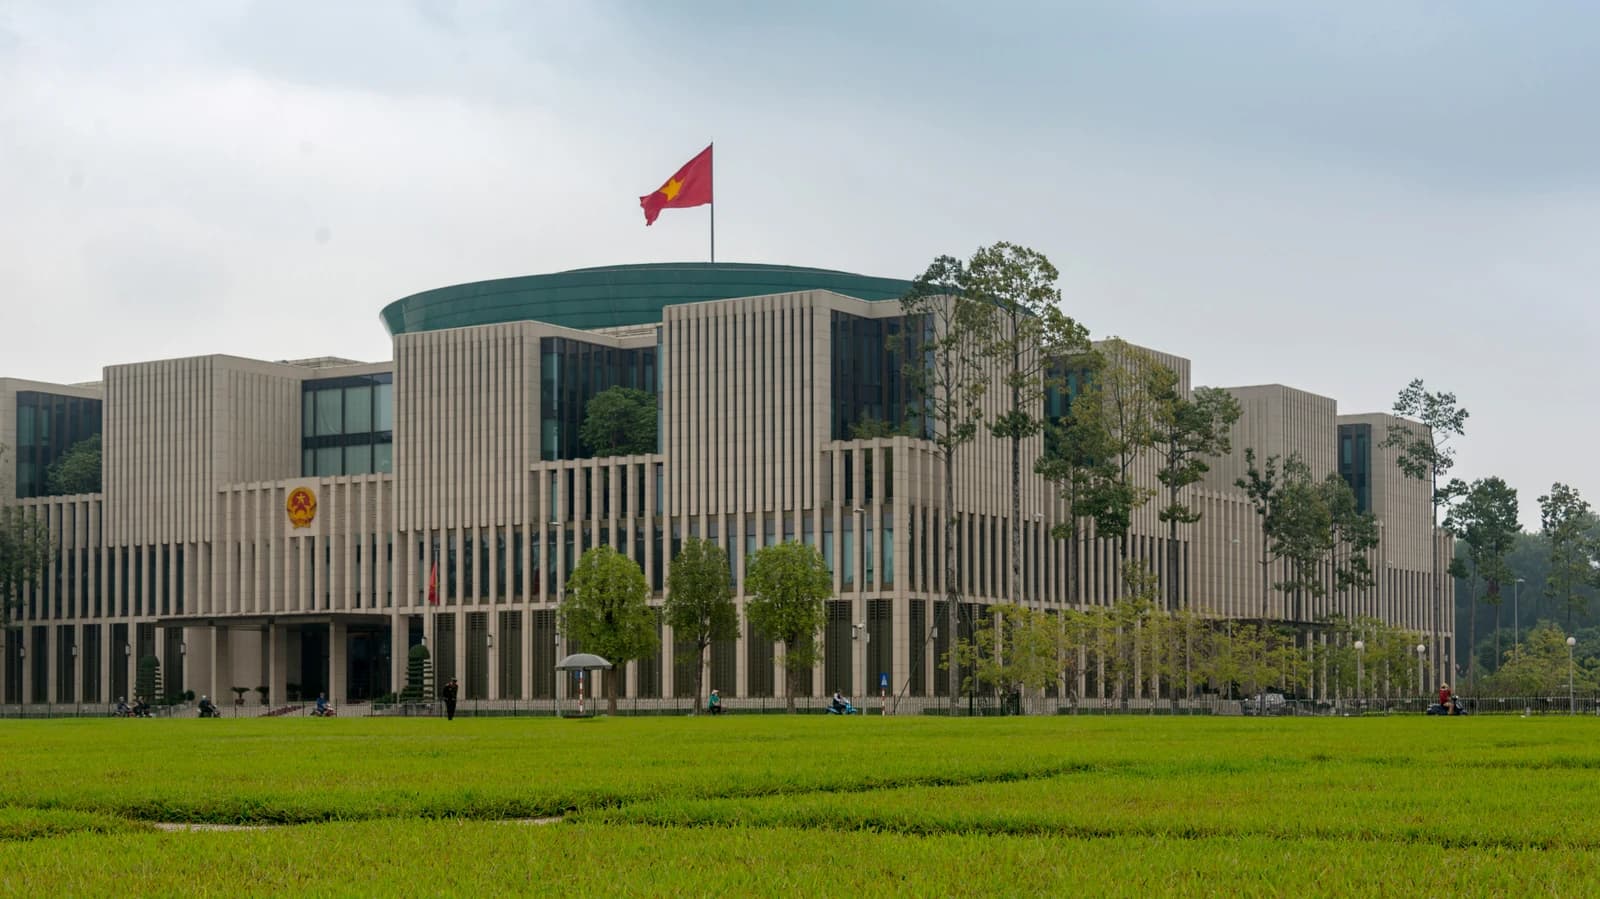
The discussion matters because tax policy is one of Hanoi’s main levers for supporting growth while protecting state revenue. Any change to corporate tax rates, deductions or tax preferences would feed directly into company earnings, capital spending decisions and the competitiveness of Vietnam’s export- and manufacturing-led economy. For consumers, revisions to personal income tax would affect disposable income at a time when policymakers are trying to balance domestic demand with fiscal discipline.
The session was part of a broader legislative agenda that also covered revisions to land-use tax, public procurement rules and environmental laws, underscoring how the government is trying to tighten the policy framework across growth, investment and sustainability priorities at once. Finance Minister Nguyen Van Thang was scheduled to explain issues raised by lawmakers, suggesting the debate is still in the negotiation phase rather than a settled package.
For investors, the key question is whether the reforms become pro-growth tax relief or a revenue-raising exercise. A lower or more targeted corporate tax burden could support listed companies’ after-tax profits and improve the appeal of Vietnam as a destination for foreign direct investment. But if lawmakers broaden the tax base or trim exemptions, sectors reliant on incentives could see margins and valuation assumptions come under pressure. Personal tax changes would also matter for retail, consumer discretionary and banking names tied to spending power and household credit demand.
The market impact is likely to be felt first through expectations rather than immediate numbers. Companies with heavy domestic exposure, as well as exporters using Vietnam as a production base, will be watching for signals on whether the legislature preserves tax breaks that support investment or shifts toward a more uniform regime. The eventual outcome will help define how aggressively Vietnam wants to use the tax code to compete for capital while managing budget needs.
| Entity | Gains | Losses |
|---|---|---|
| Corporates seeking tax relief | ▲Lower tax bills | ▼Smaller cash outflows |
| State budget | ▲Broader tax base, if reforms tighten loopholes | ▼Revenue if exemptions are expanded |
| Consumers and wage earners | ▲Higher take-home pay, if PIT eases | ▼Less disposable income, if deductions are cut |
| Foreign investors | ▲Clearer tax rules | ▼Incentive-heavy sectors, if preferences are reduced |