AI-driven capital spending is beginning to show up in U.S. inflation data, forcing central banks to decide whether a technology boom that may eventually lift productivity is also making it harder to get prices back to target.
AI Spending Adds to U.S. Inflation Pressures
That is the core dilemma for the Federal Reserve and its peers: the AI buildout is boosting demand for chips, electricity and data-center construction at a time when inflation is still running hot. Economists at Goldman Sachs estimated earlier this month that AI-related price pressures are adding about 0.5 percentage point to annual inflation in the United States, or roughly 0.3 point after adjusting for some statistical distortions. That is not enough to redefine the inflation backdrop on its own, but it is meaningful when policymakers are trying to push inflation lower by fractions of a point.
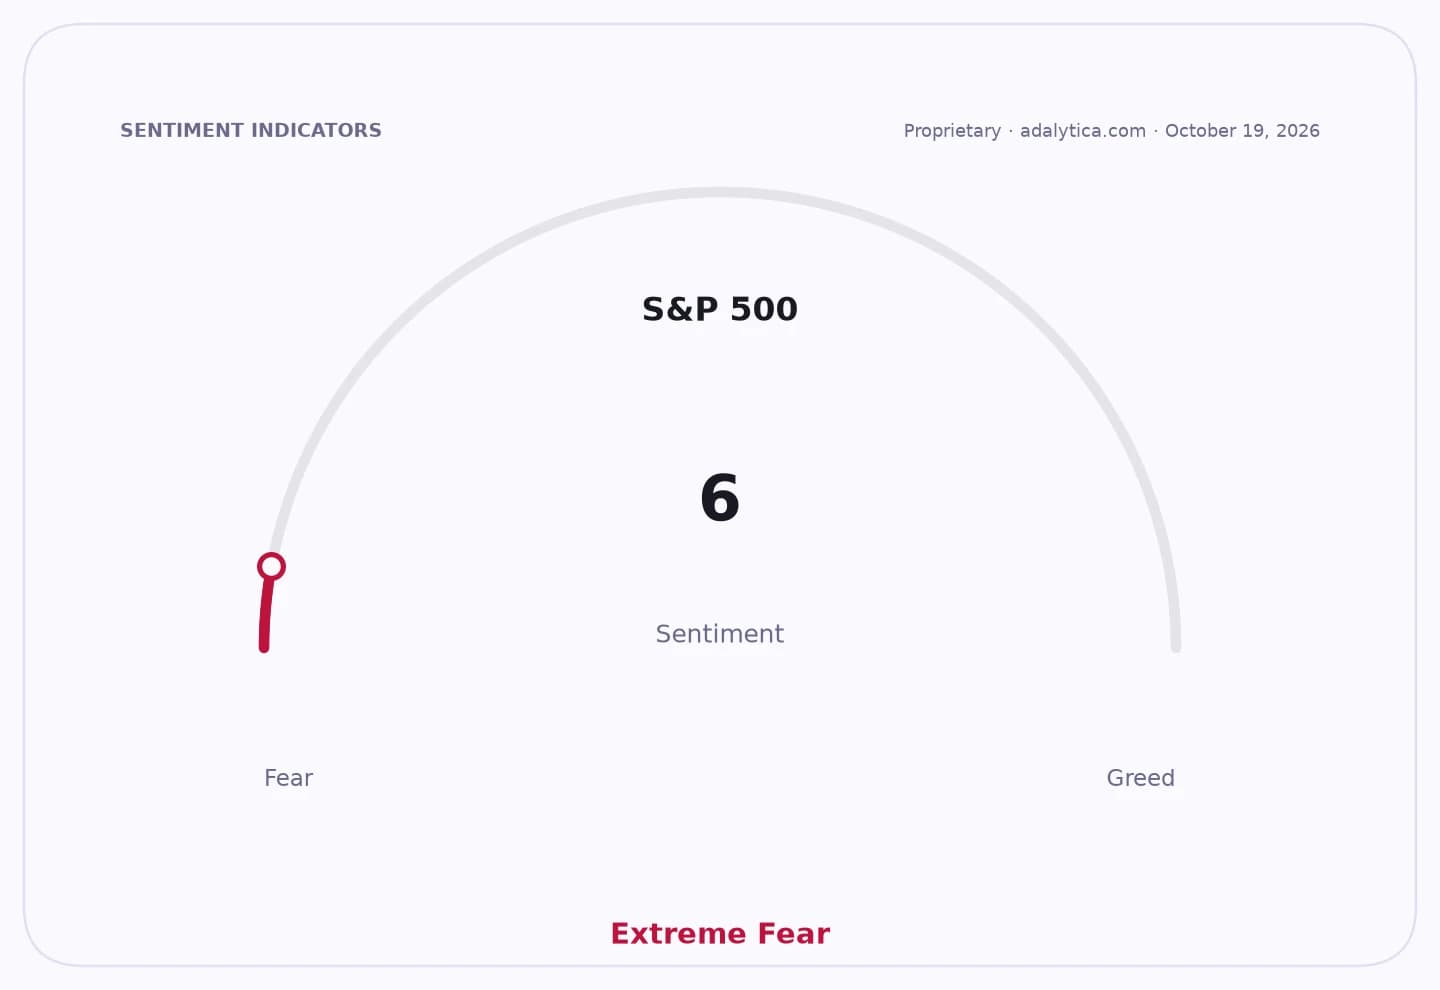
Sentiment Indicators
CPI
The pressure is most visible in the U.S. producer-price chain. Prices for chips used in data centers have jumped, while software and computer-accessory prices have also risen. Goldman said the effects spread beyond semiconductors to electricity and materials used to build data centers, underscoring how an AI investment cycle can ripple through multiple parts of the economy rather than stay confined to the tech sector.
For investors, that matters because it complicates the outlook for interest rates and valuations across the market. Higher AI-related demand can support tech earnings and capex-heavy names, but it can also keep monetary policy tighter for longer if it feeds into broader inflation. The Nasdaq-100 tracker QQQ and the semiconductor ETF SMH have both stayed well above their 200-day moving averages, but both have also seen recent swings, with SMH’s relative strength index sliding to 38.1 and QQQ’s to 39.4, a sign that the trade is still vulnerable to any shift in rate expectations.
The policy question is not whether AI is inflationary in the abstract, but whether the inflation it creates is temporary and sector-specific or broad enough to force a harder central-bank response. In Europe, the effect looks more muted because the AI-linked goods basket is smaller. In the U.S., however, the scale of spending by companies such as Microsoft and Alphabet is large enough to matter. Both groups flagged in recent filings that demand for cloud and AI services is hard to forecast and that capacity investment carries the risk of underutilization if demand disappoints.
That uncertainty is why central bankers are unlikely to welcome AI as a clean disinflation story just yet. If the productivity gains arrive, they could eventually lower costs and cool prices. But if companies and households spend ahead of those gains, the near-term result is likely to be stronger growth, stickier inflation and a harder job for the Fed.
The next test is whether the AI investment wave keeps pushing up energy, construction and hardware costs into late 2026, and whether the Fed treats those price gains as a temporary supply shock or a reason to keep policy restrictive for longer.
| Entity | Gains | Losses |
|---|---|---|
| AI chipmakers | ▲Higher demand | ▼Margins if policy tightens |
| Microsoft/Alphabet/Oracle | ▲Cloud and AI revenue growth | ▼Higher capex and scrutiny |
| Federal Reserve | ▲Time to assess inflation mix | ▼Easier path to rate cuts |
| Consumers and borrowers | ▲Potential future productivity gains | ▼Sticky prices and borrowing costs |