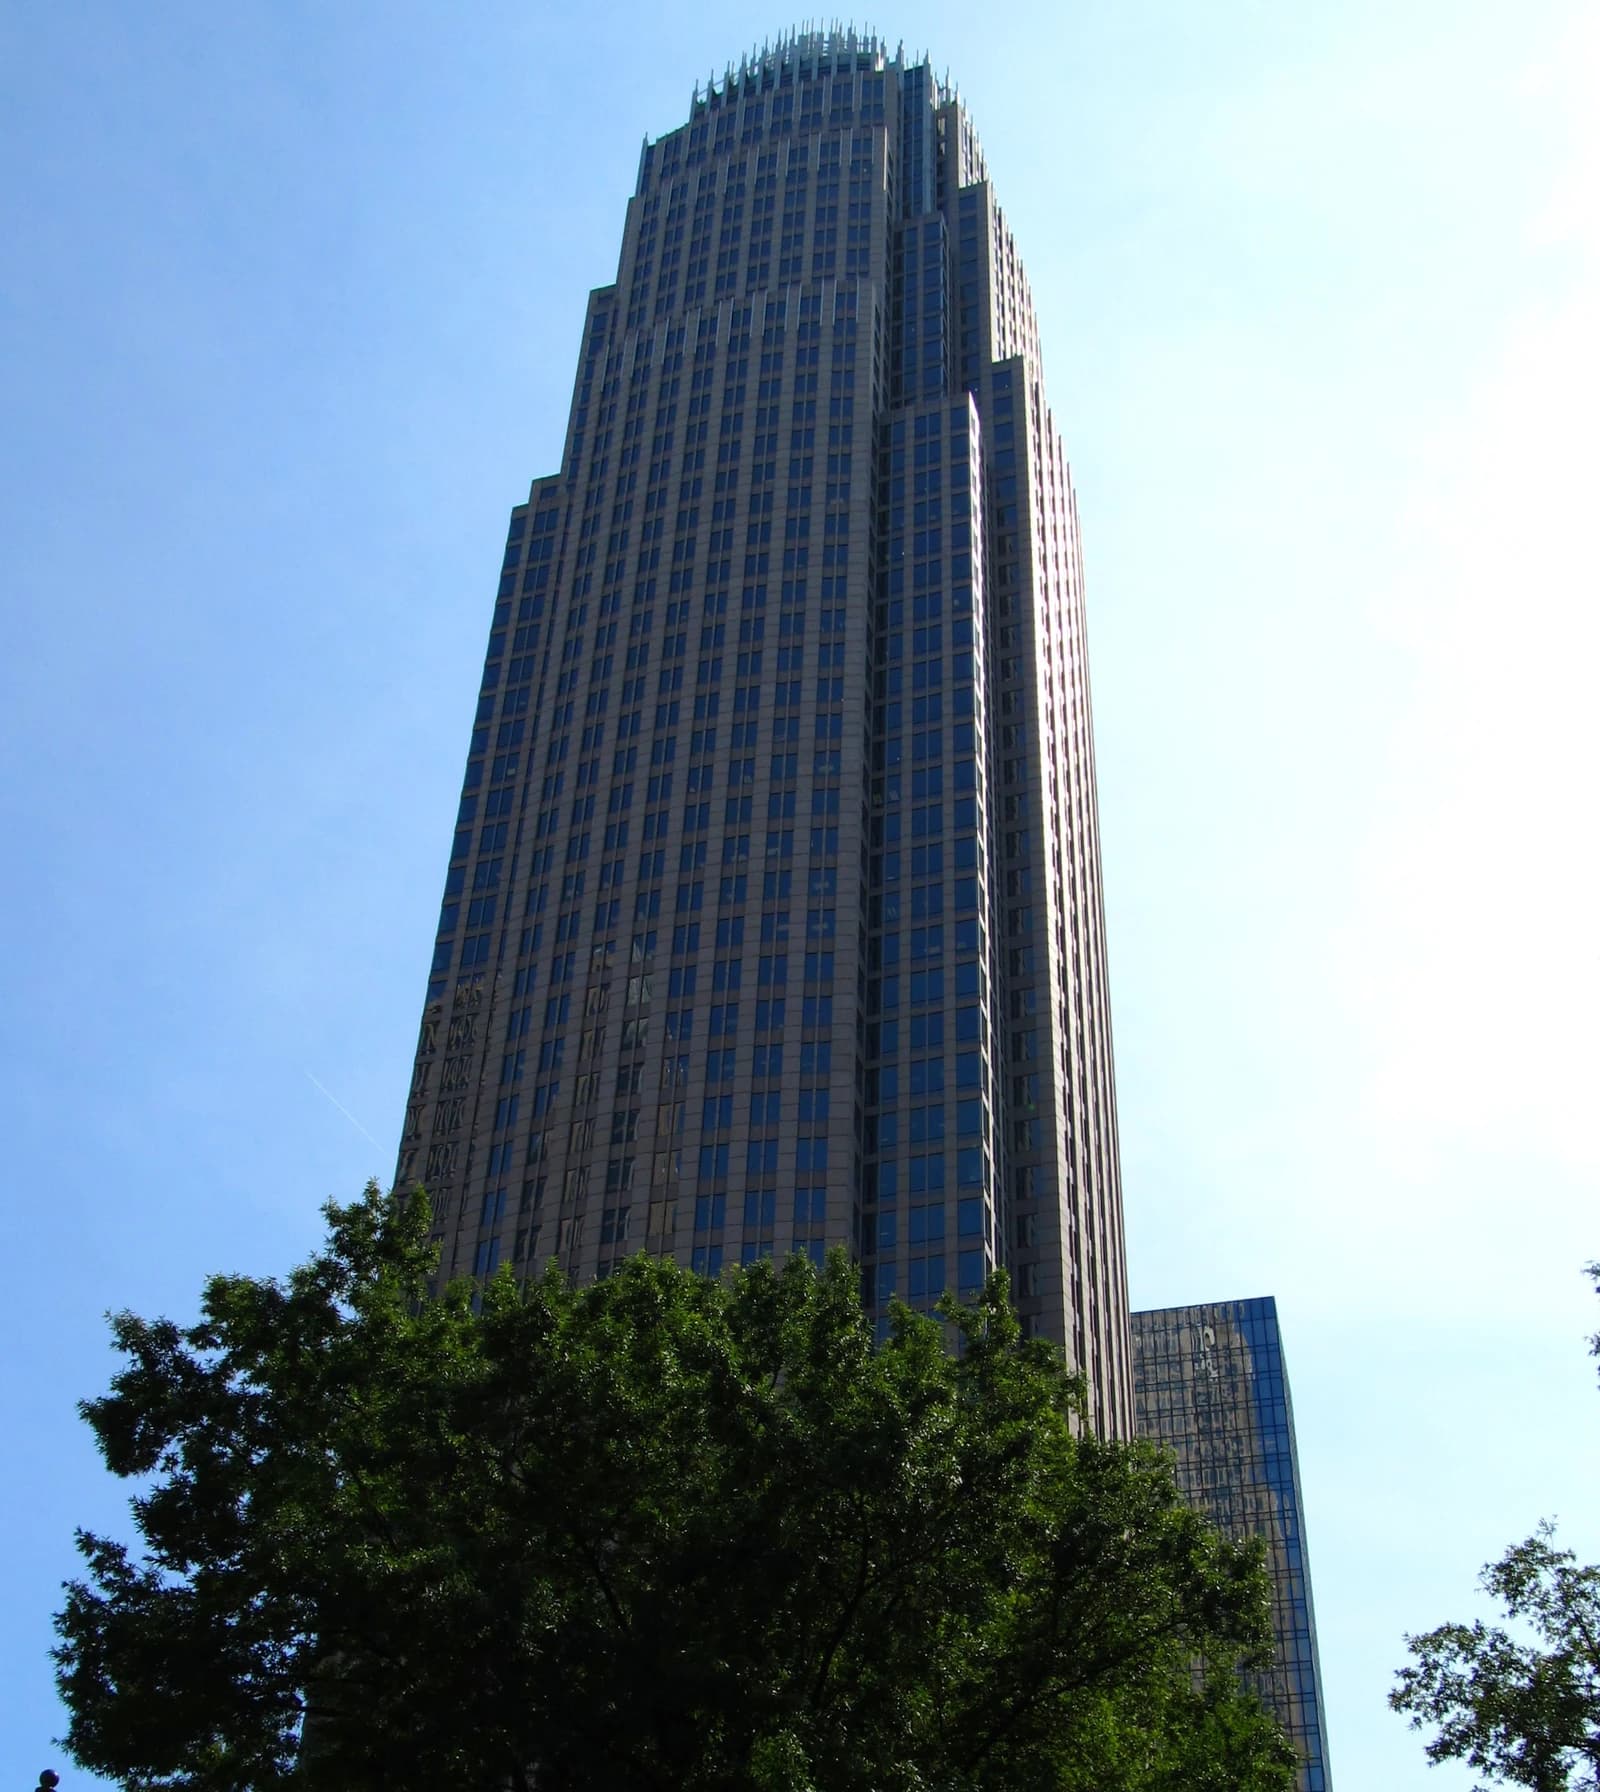
Bank of America’s third-quarter charge-offs were essentially flat from a year earlier, a sign that one of the biggest U.S. lenders is still managing credit losses without the kind of sharp deterioration that often alarms investors.
Bank of America Charge-Offs Stay Flat in Q3
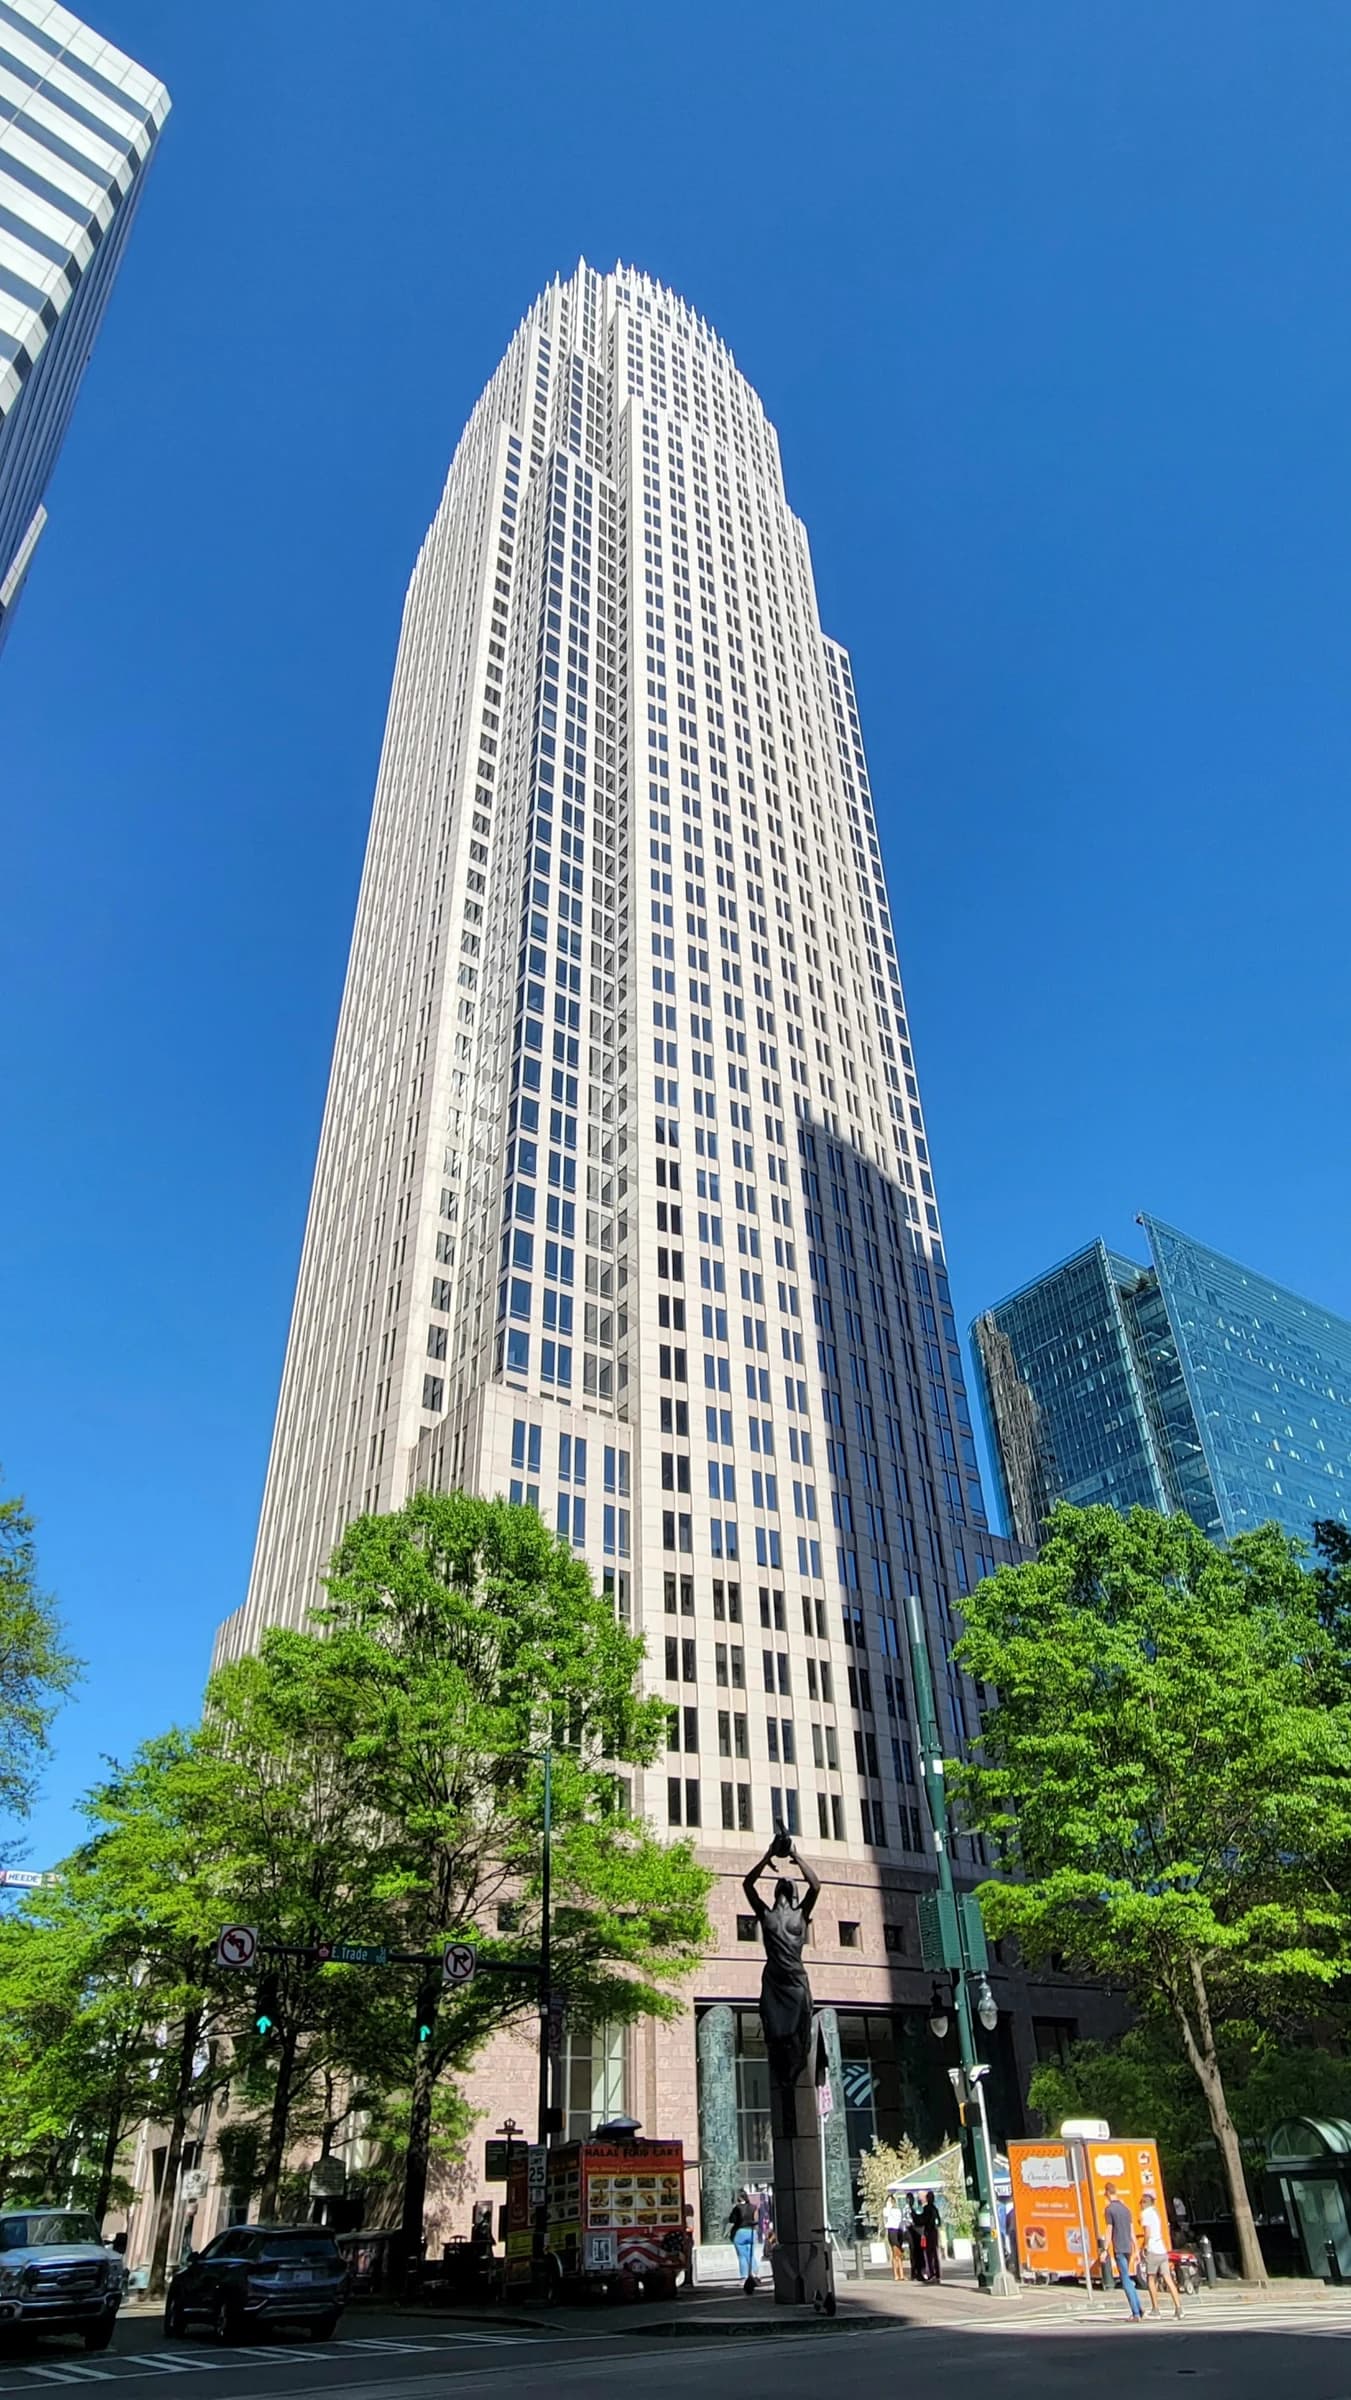
The bank said net charge-offs in the quarter ended Sept. 30 were $1.349 billion, just below the $1.367 billion it posted a year ago. For investors, that matters because charge-offs are one of the clearest windows into borrower health: when they rise quickly, banks usually have to set aside more capital for losses, which can crimp profits and slow buybacks or dividend growth.
Sentiment IndicatorsⓘProprietary · adalytica.com · October 16, 2026
This is a snapshot — live sentiment, awareness and momentum for 130+ markets update continuously in the dashboard.Open AlphaPulse
On the surface, that is a reassuring message for Bank of America and the broader banking sector. Credit quality appears to be holding up even as consumers and businesses continue to navigate higher borrowing costs, uneven growth and pockets of stress in parts of the economy. That makes the third quarter less about a credit scare and more about resilience.
The stock market has already been rewarding that resilience. Bank of America shares had climbed sharply through the summer, reaching above $64 in August before slipping back into the low $50s in October. The recent pullback leaves the stock below both its 50-day and 200-day moving averages, while the relative strength index has fallen into oversold territory. That kind of technical setup often reflects investor caution after a strong run, not necessarily a change in the underlying story.
The bigger question for long-term investors is whether the current credit backdrop can last. So far, Bank of America’s numbers suggest the answer is yes, at least for now. Net charge-offs are still elevated in absolute terms because this is a massive lender with a huge consumer book, but the year-over-year comparison shows no sign of a sudden break. That is important because banks do not need loan losses to disappear to make money; they just need them to stay contained while they keep growing deposits, lending and fee income.
Adalytica’s trade-signal snapshot for the S&P 500 also points to a market that is cautious but not panicked, while Treasury-bond sentiment has turned more positive. That combination usually fits a backdrop in which investors are looking for quality balance sheets and dependable earnings rather than chasing the most cyclical parts of the market. Large banks with diversified revenue streams can benefit from that shift.
For shareholders, the takeaway is straightforward: stable charge-offs support the case that Bank of America remains a durable franchise, not a credit story in distress. If earnings later show the same steadiness in loan growth, net interest income and capital returns, the stock can keep compounding over time. For now, it remains a name worth watching for investors who want exposure to a resilient U.S. financial giant and are willing to hold through inevitable market swings.
| Entity | Gains | Losses |
|---|---|---|
| Bank of America shareholders | ▲Credit stability | ▼Faster loss provisioning |
| Bank of America management | ▲Earnings visibility | ▼Pressure to overbuild reserves |
| Long-term bank investors | ▲Durable franchise thesis | ▼Short-term volatility |
| Credit-sensitive borrowers | ▲Ongoing lending access | ▼Tighter underwriting if losses rise |