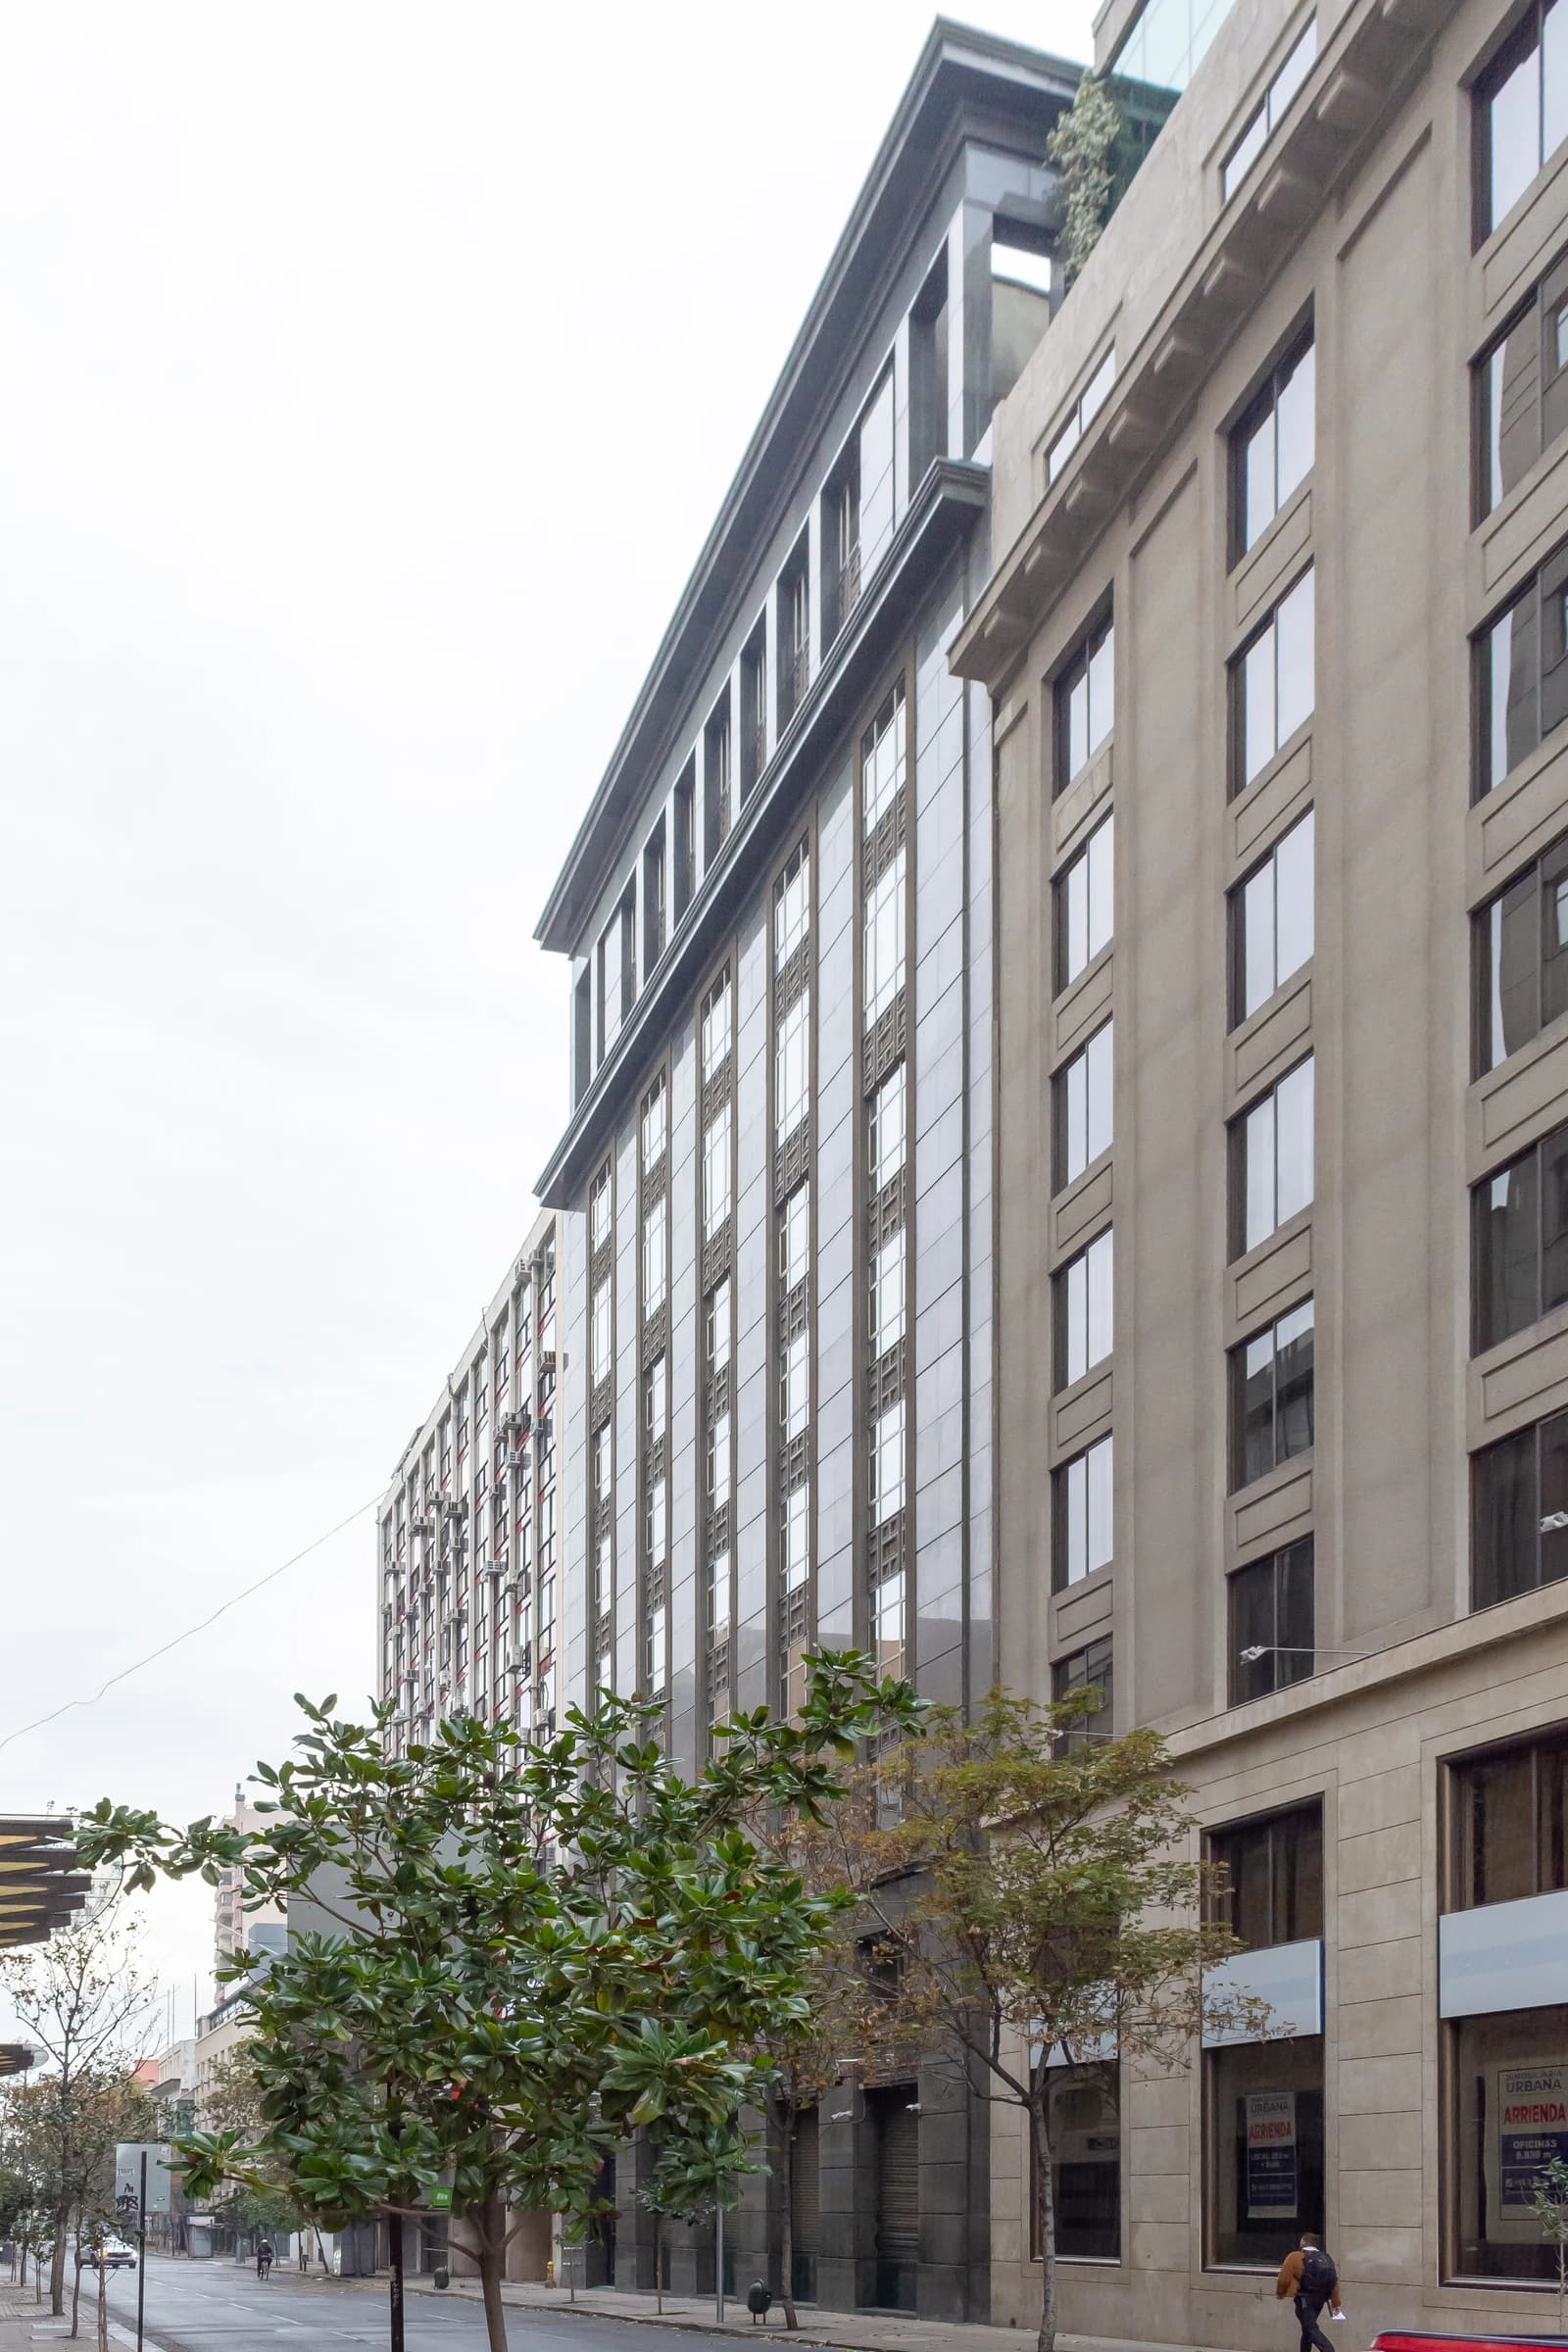
Carrefour Brasil has sold 22 store properties to a real estate fund and will keep operating in the locations by paying rent, a move that gives the retailer an immediate cash-raising option while increasing its fixed lease obligations.
Carrefour Brasil Sells 22 Stores in Leaseback Deal
The transaction is a classic sale-and-leaseback, a financing structure that lets companies unlock capital tied up in property without giving up day-to-day control of the sites. For Carrefour, which is under pressure to preserve flexibility in a competitive Brazilian retail market, the deal can help support liquidity, cut balance-sheet intensity and potentially finance operations or debt needs. But it also shifts the company from owner to tenant, reducing future asset backing while adding recurring rent expense that can weigh on margins if sales weaken.
Carrefour did not disclose the value of the transaction, and the buyer was identified as Pátria Renda Urbana, a real estate fund. The deal still requires approval from Brazil’s antitrust regulator Cade, underscoring that the transaction is not yet final.
For investors, the key question is whether the proceeds outweigh the longer-term cost of rent. In the near term, the sale could be read as a sign of financial discipline and asset monetization at a time when retailers are trying to protect returns on capital. Over time, though, the benefit depends on how much cash is released, what it is used for and whether the rental burden remains manageable in a sector where gross margins are already sensitive to pricing pressure.
The move also fits a broader pattern in retail, where large chains increasingly use property transactions to improve capital efficiency rather than hold real estate on their books. That can be supportive for equity holders if it strengthens the balance sheet, but it tends to favor creditors and property investors more than operating leverage.
Carrefour Brasil’s portfolio includes Atacadão, Sam’s Club, Carrefour Hiper, Carrefour Bairro and Carrefour Express. The market will now watch whether management treats the transaction as a one-off balance-sheet tool or the start of a broader property monetization strategy.
| Entity | Gains | Losses |
|---|---|---|
| Carrefour Brasil | ▲Cash proceeds | ▼Higher rent costs |
| Pátria Renda Urbana | ▲Prime retail assets | ▼Capital tied up in properties |
| Equity holders | ▲Better liquidity profile | ▼Less asset backing |
| Landlords/real estate funds | ▲Steady rental income | ▼Retail tenant risk |